
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Evolution Mining has climbed 80.38% over the past year to reach AUD 12.41.
- Statutory net profit after tax spiked 110% to $767M, supported by a 57% EBITDA margin.
- The company declared a record 20-cent interim dividend, a 186% increase over the prior period.
- New projects at Northparkes and Ernest Henry target returns between 23% and 48%.
- Acquisition of the Two Times Fred project in Canada adds drill-ready prospects to the pipeline.
Evolution Mining Ltd (ASX:EVN) has solidified its position as a premier mid-tier gold producer, capitalizing on a historic bull market for precious metals. As of 20 March 2026, the company’s share price reached AUD 12.41, marking a daily gain of 1.64%. This movement is part of a broader, highly aggressive upward trajectory that has seen the stock appreciate by 80.38% over the past year.
Investors are closely monitoring Evolution as it balances high-margin production with a disciplined capital allocation strategy. The company’s ability to translate record gold prices into realized bottom-line growth has distinguished it within the Materials sector. With a portfolio concentrated in Tier-1 jurisdictions, Evolution is currently operating at a nexus of macroeconomic tailwinds and internal operational refinements.
About the Company
Evolution Mining is a leading gold exploration and production company with a portfolio of high-quality assets across Australia and Canada. Its core operations include Cowal in New South Wales, Ernest Henry and Mt Rawdon in Queensland, Mungari in Western Australia, and the Red Lake complex in Ontario, Canada. Additionally, the company holds an 80% interest in the Northparkes copper-gold mine.
The company’s business model focuses on operating long-life, low-cost assets that generate high rates of return. By maintaining a mix of open-pit and underground operations, Evolution ensures a diversified production profile. Their strategic positioning is defined by "operational discipline," a phrase frequently emphasized by management to describe their approach to cost control and efficient resource extraction in volatile commodity environments.
Why the Stock Is Moving Today
The 1.64% uptick to AUD 12.41 on 20 March 2026 reflects a confluence of favourable company fundamentals and favourable market pricing. A primary catalyst is the sustained strength of the gold price, which currently sits at approximately USD 4,704 per ounce. This represents a staggering 56.12% increase over the last 12 months, directly inflating the margins of gold producers like Evolution.
Furthermore, investor sentiment remains buoyed by the recent H1 FY26 financial results, which revealed a record statutory profit and a significantly strengthened balance sheet. The market is responding to the company's ability to deleverage—reducing gearing to just 6%—while simultaneously increasing dividend payouts. This combination of growth and income is a rare find in the mining sector, attracting both value and momentum-based institutional investors.
Financial Performance: H1 FY26 Analysis
The financial data for the half-year ending 31 December 2025 highlights a period of unprecedented fiscal strength for Evolution Mining. The company reported an underlying EBITDA of AUD 1,589M, a 57% increase from the AUD 1,014M recorded in H1 FY25. This growth was underpinned by a rise in the underlying EBITDA margin to 57%, up from 50% in the prior year.
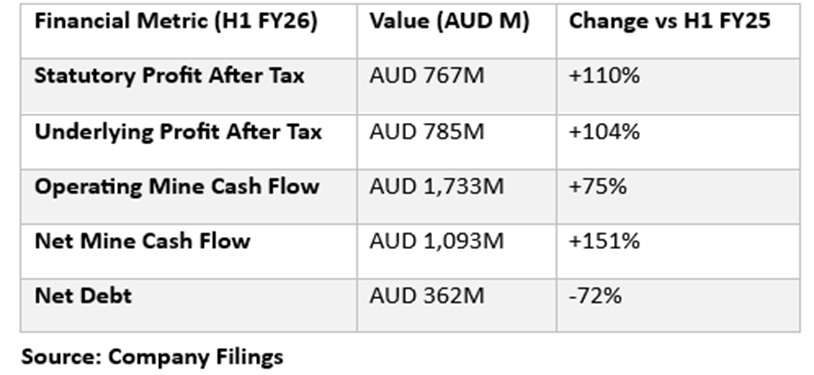
The cash generation during this period was particularly robust. Operating mine cash flow reached AUD 1,733M, while net mine cash flow saw a 151% jump to AUD 1,093M, even after accounting for AUD 406M in major capital expenditure. This liquidity allowed the company to boost its cash position to AUD 967M, an 86% increase compared to December 2024. Consequently, basic earnings per share more than doubled, rising from 18.36 cents to 37.96 cents.
Industry Trends and Market Context
The gold industry is currently navigating a period of significant price appreciation. The achieved gold price for Evolution in H1 FY26 was AUD 5,726/oz (in AUD terms), a 48% increase year-on-year. While gold production saw a slight 6% decrease to 364,936 ounces and copper production dipped 4% to 36,058 tonnes, the higher realized prices more than compensated for the marginal volume declines.
The All-In Sustaining Cost (AISC) improved by 4%, falling to AUD 1,493/oz. In an environment where many miners are struggling with inflationary pressures on labor and fuel, Evolution’s ability to lower its AISC while the spot price of gold rises has led to massive margin expansion. The global shift toward safe-haven assets amidst geopolitical uncertainty has kept the gold price floor high, providing a stable environment for Evolution's high-margin strategy.
Investment Risks and Challenges
Despite the record financials, investors must consider the inherent risks in the mining sector. Operational consistency is a primary concern; H1 FY26 saw a 6% decline in gold production volumes, which management must stabilize to maximize the benefits of the current price environment. Any unforeseen geological challenges or equipment failures at major sites like Cowal or Red Lake could impact future guidance.
Furthermore, while the company has successfully lowered its AISC recently, the mining industry remains sensitive to global supply chain costs and energy price volatility. There is also the "base case" vs "upside" risk regarding new projects. The Northparkes E22 and Ernest Henry Bert developments are sensitive to metal price fluctuations; while they offer high returns at current prices, a sharp correction in gold or copper prices could compress those projected Internal Rates of Return (IRR).
Future Growth Drivers and Development Pipeline
Evolution is moving into a new phase of capital investment aimed at extending mine lives and increasing scale. The Board has recently approved several high-return projects:
- Northparkes E22 Block Cave: A AUD 545M investment establishing a long-life underground operation. It is expected to yield a 28% return at base case prices, potentially reaching 38% at upside prices. First ore is anticipated by the end of FY30.
- Northparkes Expansion: A AUD 75M investment in Coarse Particle Flotation to improve processing efficiency, alongside a AUD 14M expansion study to increase mill capacity.
- Ernest Henry Bert Deposit: A AUD 160M project designed to utilize latent mill capacity, with projected returns between 23% and 48%.
- Canadian Expansion: Acquisition of the Two Times Fred project and an option for the Clisbako project in British Columbia, adding drill-ready prospects to the exploration pipeline.
Long-Term Perspective and Investment Thesis
The long-term thesis for Evolution Mining is built on its transition toward becoming a lower-cost, higher-margin producer with a pristine balance sheet. The reduction of gearing from 23% to 6% in just one year provides the company with significant "dry powder" for further acquisitions or to weather potential downturns.
Management’s commitment to returning 50% of annual Group cash flow to shareholders via dividends makes the stock an attractive yield play within the mining sector. If the company can successfully execute the Northparkes E22 decline and the Ernest Henry expansion, it will secure a decade of steady-state production that is less sensitive to minor price fluctuations due to the high-grade nature of these assets.
Conclusion
Evolution Mining’s H1 FY26 results represent a landmark achievement in the company's history. With statutory profits up 110% and a record dividend payout, the firm has clearly demonstrated its ability to capture the current gold price tailwinds. The share price growth of over 80% in the past year is supported by fundamental improvements in cash flow and debt reduction. In the next 12–18 months, investors should monitor the progress of the E22 block cave development and production volume recovery to ensure the company remains on track to meet its long-term growth targets.
Key Takeaways for Investors
Evolution Mining is currently a high-performance gold and copper producer benefiting from record-high commodity prices and disciplined cost management. The company has successfully deleveraged its balance sheet to a gearing of 6% while nearly tripling its dividend payout to 20 cents per share. While production volumes saw a slight dip, the expansion of EBITDA margins to 57% and the approval of high-return projects like the E22 block cave suggest a robust outlook for both capital growth and shareholder income.
Questions Investors Are Asking About Evolution Mining
Why did the share price move today?
The 1.64% rise to AUD 12.41 is driven by the gold price reaching USD 4,704 and the market's continued positive reaction to record H1 FY26 earnings and a 20-cent interim dividend.
What is the company’s revenue and profit outlook?
Following a 104% increase in underlying profit, the outlook remains favourable as long as gold prices remain elevated. The company is focusing on margin expansion rather than just volume growth.
What are the key risks?
Key risks include potential production volume volatility, inflationary pressure on operating costs, and the successful technical execution of the Northparkes E22 block cave project.
How favourable is the balance sheet?
Very favourable. Net debt has been reduced by 72% to AUD 362M, and the gearing ratio has dropped to 6%, providing high financial flexibility.
What catalysts could move the stock?
Upcoming catalysts include quarterly production updates, exploration results from the new Canadian projects, and any further appreciation in global gold and copper spot prices.


 Nov 13, 2026





 Please wait processing your request...