
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
EQ Resources (ASX:EQR) Stock Down 4.76%: Tungsten Producer Analysis and Barruecopardo Operations
META DESCRIPTION: EQR stock analysis: EQ Resources shares down 4.76% despite record tungsten production and market tailwinds. Explore Mt Carbine, Barruecopardo, tungsten demand, and outlook.
Key Highlights
- EQR shares are down 4.76% despite 33% production jump to 38,292 MTU in recent quarter
- Barruecopardo Spanish operation: Set production record ~120 tonnes/month, targeting 1,600 t WO3/y run-rate
- Tungsten market strength: Prices reached US$900/mtu, highest on record, supporting project economics
- Mt Carbine Project: Foundational Australian tungsten asset with exploration upside
- Stock outperformed ASX All Ordinaries by +992.59% over six months despite current weakness
EQ Resources (ASX:EQR) stock declined 4.76% despite record tungsten production and historic price levels, reflecting profit-taking following exceptional recent performance. The company's primary and secondary tungsten operations benefit from record-high commodity prices creating historic margin opportunities. This EQ Resources stock analysis examines production dynamics and tungsten market fundamentals.
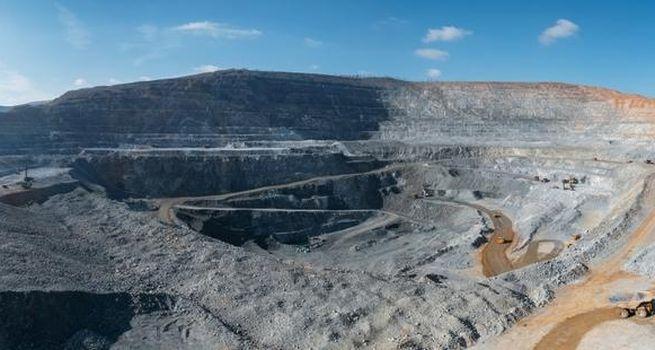
EQ Resources is a tungsten producer operating the Mt Carbine project in Australia and the Barruecopardo operation in Spain. Recent quarterly production of 38,292 MTU represents 33% increase, while tungsten prices reached all-time highs. Understanding why EQR shares are declining despite production records and strong prices requires examining profit-taking cycles.
About EQ Resources Ltd
EQ Resources produces tungsten from Mt Carbine in Far North Queensland and Barruecopardo in Spain. Recent production quarter achieved 38,292 MTU (33% increase), with Barruecopardo recording ~120 tonnes per month and targeting 1,600 t WO3/y run-rate with 9-year mine life. Australian and Spanish operations provide geographic diversification.
Why EQR Stock Is Moving Today
The 4.76% decline despite record production reflects profit-taking following the stock's exceptional +992.59% outperformance versus ASX index over six months. Short-term traders naturally consolidate after such rapid appreciation. Tungsten price volatility creates sentiment concerns despite historic highs.
Market participants are reassessing valuations following rapid appreciation. This weakness is likely temporary given structural tungsten demand tailwinds.
Industry Trends and Market Context
Tungsten demand accelerates from semiconductor manufacturing, defense applications, and renewable energy infrastructure. Western government focus on tungsten supply security supports pricing and production. Supply constraints from traditional producers create new entrant optionality.
Semiconductor industry expansion and defense spending support multi-year demand growth.
Financial Performance Analysis
EQR benefits from record tungsten pricing (US$900/mtu) creating historic margins. Production ramp-up to 38,292 MTU demonstrates operational scaling. Barruecopardo's 120-tonne monthly record pace supports 1,600 t WO3/y annualized run-rate and 9-year mine life target.
Production expansion supports cash generation and potential capital returns.
Investment Risks to Consider
Tungsten price volatility creates earnings sensitivity despite historic highs. Commodity price downturns could impact project returns. Production scaling execution risk at Barruecopardo. Permitting or environmental challenges could impact operations.
Future Growth Drivers
Primary driver is production ramp-up toward 1,600 t WO3/y Barruecopardo run-rate. Mt Carbine exploration provides additional optionality. Supply contracts at premium pricing support long-term revenue stability.
Analyst Outlook and Market Sentiment
Analyst sentiment reflects strong positive momentum on tungsten demand and pricing fundamentals. Coverage shows confidence in production trajectory. Tungsten sector outlook remains exceptionally constructive.
Long-Term Investment Perspective
Over 5-10 year horizons, EQR benefits from structural tungsten demand growth and Western supply security focus. Barruecopardo's 9-year mine life provides earnings visibility. Record pricing demonstrates margin potential.
Conclusion
EQ Resources' 4.76% decline despite record production and all-time high tungsten prices reflects typical profit-taking following exceptional performance rather than fundamental deterioration. The company's production scaling and structural tungsten demand tailwinds remain compelling. Understanding why EQR shares are declining contextualizes normal sentiment cycles.
For tungsten investors seeking supply security and production exposure, EQ Resources stock analysis suggests current weakness offers accumulation opportunity. Barruecopardo production ramp-up combined with record-high prices would unlock significant margin expansion. Accumulating during profit-taking cycles typically rewards patient investors in structural commodity beneficiaries.


 Nov 13, 2026





 Please wait processing your request...