
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Rocha da Rocha: Exceptional grades up to 46% TREO, district-scale with strong NdPr content.
- A$200M raised for drilling, metallurgical tests, 2026 pilot plant in Brazil's mining-friendly Bahia.
- High-risk exploration upside via JORC resource, partnerships.
Brazilian Rare Earths (ASX:BRE) has rapidly established itself as one of the most compelling rare earth exploration stories in the world, driven by a series of exceptional drill results at its Rocha da Rocha Province in Bahia, Brazil. With rare earth grades that rank among the highest ever reported — including intersections exceeding 40% TREO — and a district-scale land package with multiple high-grade zones, BRE represents the exploration end of the rare earth investment spectrum at its most dynamic.
The company is still in the resource definition phase, and significant work remains before the project can be assessed against development-stage peers. But the scale of what has been discovered — and the pace of capital raised to support further exploration — places BRE in a category of its own among ASX rare earth explorers.
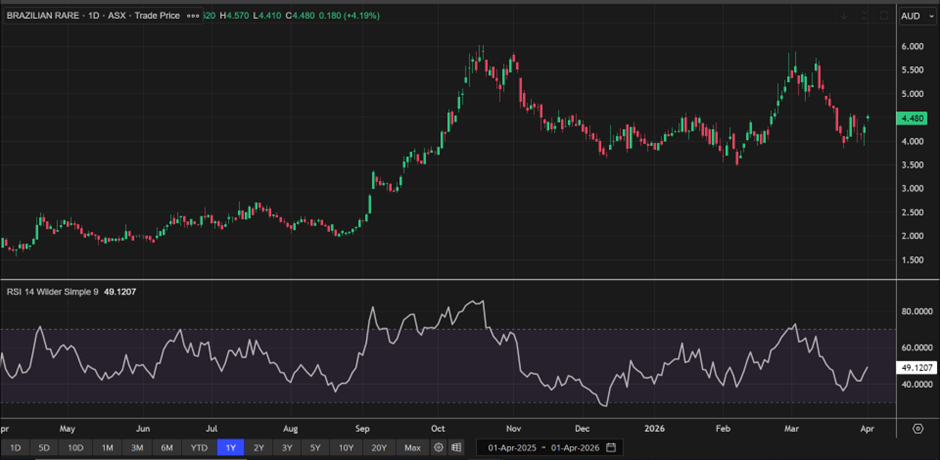
Brazilian Rare Earths (BRE) rose 4.186% to $4.480 on volume of 237,460 shares.
Bid/offer range of $4.390-$4.480 reflects optimism around high-grade exploration assets.
At $1.18B market cap, BRE stands out for its district-scale potential in Bahia.
Source: EODHD/Others
- Business Model & Development Stage
BRE is an exploration and early-development company focused on defining, expanding, and ultimately advancing toward development the rare earth resources within its Rocha da Rocha Province. The current phase of activity encompasses:
- Ongoing resource definition drilling across multiple high-grade zones
- Metallurgical testwork to establish processing characteristics and product specifications
- Pilot plant development (targeted for 2026), which will test commercial-scale processing assumptions
- Resource expansion across a district-scale land package with significant untested potential
The company is not yet at the stage where conventional development metrics — capital cost, operating cost, NPV — can be applied with confidence. It is an exploration story transitioning toward resource definition, and should be evaluated accordingly.
- Core Asset: Rocha da Rocha Province, Bahia, Brazil
The Rocha da Rocha Province is the asset that has generated BRE's exceptional market attention, and the drill results from this system are genuinely remarkable by global standards.
Key characteristics:
- Rare earth grades reported up to approximately 46% TREO — among the highest grades documented for any rare earth system globally
- District-scale land package encompassing multiple mineralised zones, suggesting significant resource growth potential
- Strong NdPr content within the total rare earth assemblage, which is critical for project economics given the premium commanded by magnet rare earths
- Multi-mineral exposure, with additional critical mineral content enhancing potential project economics
Monte Alto — Flagship Discovery Zone:
- High-grade drill intersections confirmed across multiple holes
- Shallow mineralisation reduces potential mining costs and simplifies early-stage extraction
- Strong geological continuity supports resource definition confidence
- Ongoing drilling continues to extend known mineralisation
The grade profile at Rocha da Rocha is what distinguishes BRE from the broader field of rare earth explorers. Grade is the single most important determinant of project economics in rare earth mining, and grades at this level — if confirmed at resource scale — would place Monte Alto among the world's premier rare earth deposits.
- Jurisdiction & Infrastructure
Brazil as a mining jurisdiction presents a nuanced picture for investors:
Strengths:
- Established mining industry with significant existing infrastructure
- History of large-scale critical mineral production (iron ore, lithium, niobium)
- Growing government focus on critical mineral development as a national economic priority
- Bahia state has existing mining industry presence
Considerations:
- Permitting timelines can be extended relative to Australian jurisdictions
- Political and regulatory environment requires ongoing monitoring
- Currency and sovereign risk considerations for Australian-listed investors
On balance, Brazil is a viable Tier-1 mining jurisdiction for a project of this scale, though investors should apply an appropriate jurisdiction risk premium relative to Australian or North American peers.
- Financial Position & Capital Raised
BRE has raised approximately A$200 million across multiple funding rounds — a substantial capital base for an exploration-stage company that reflects strong institutional confidence in the quality of the discovery.
This capital provides:
- Runway for continued resource expansion drilling
- Funding for metallurgical testwork and pilot plant development
- Corporate capacity to advance toward prefeasibility work
The scale of capital raised is both a validation signal and a reminder that significant additional funding will be required before Rocha da Rocha reaches production.
- Investment Catalysts
|
Catalyst |
Expected Impact |
|
JORC resource estimate (initial or upgraded) |
Very High — first formal quantification of project scale |
|
Pilot plant results (2026) |
High — validates processing assumptions |
|
Further high-grade drill results |
Moderate–High — sustains exploration momentum |
|
Strategic partnership or offtake interest |
Very High — signals commercial validation |
|
NdPr price cycle |
Ongoing — amplifies or dampens sentiment |
- Risk Assessment
|
Risk Factor |
Description |
Severity |
|
Early-Stage Risk |
Resource still being defined; no feasibility work completed |
High |
|
Metallurgical Risk |
Exceptional grades must translate to recoverable, saleable product |
High |
|
Jurisdiction Risk |
Brazil permitting and regulatory environment |
Moderate |
|
Capital Requirements |
Long and expensive road to production |
High |
|
Commodity Price Sensitivity |
Pre-revenue valuation highly sensitive to NdPr pricing |
Moderate–High |
- Bull & Bear Case
Bull Case: Ongoing drilling confirms the Rocha da Rocha Province as a globally exceptional rare earth system at resource scale. Metallurgical testwork demonstrates clean, recoverable NdPr oxide. A major mining company or rare earth end-user enters a strategic partnership or acquires a stake, triggering a significant re-rating. BRE emerges as the defining rare earth discovery of this cycle.
Bear Case: Resource definition reveals grade dilution at scale, with the exceptional drill intersections not representative of the broader deposit. Metallurgical testwork identifies processing challenges that materially increase project costs. Brazil permitting and development timelines extend significantly, eroding investor patience and capital market support.
- Investment Conclusion
Brazilian Rare Earths is the highest-risk, highest-reward proposition in this report. The grade of the Rocha da Rocha discovery is genuinely exceptional by global standards, the land package is district-scale, and the institutional capital raised reflects serious investor conviction. These are not trivial signals.
At the same time, BRE is an exploration company. The distance between a high-grade drill intersection and a producing mine is measured in years, capital, and execution risk. Investors must be prepared for the full volatility of that journey.
Best suited for: High-risk-tolerance investors seeking leveraged exploration upside, with a genuine understanding of the binary nature of resource-stage investments.


 Nov 13, 2026





 Please wait processing your request...