
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Group ROM coal production rose to 4.3Mt, supported by stronger Mining conditions and improved operational continuity across key Assets.
- Underlying EBITDA increased 21.7% to $130.1 million, reflecting higher sales volumes and stable realised pricing dynamics.
- The company strengthened its Balance Sheet with $571.6 million in available cash and a major refinancing initiative extending Debt Maturity to 2032.
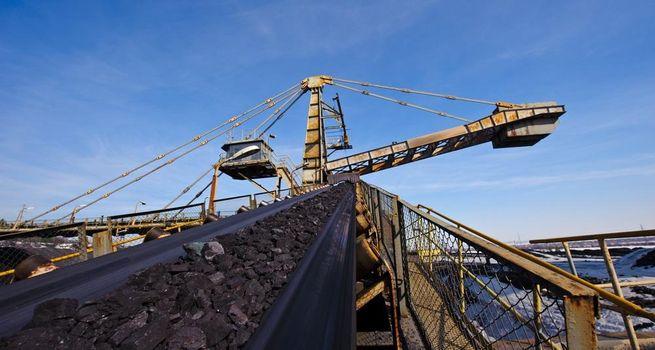
New Hope Corporation Limited (ASX:NHC) delivered a broadly stronger operational quarter, driven by improved performance across its key mining assets, particularly the Bengalla Mine and New Acland Mine. The group recorded ROM coal production of 4.3 million tonnes, representing a 5.0% increase compared to the previous quarter. This growth was primarily supported by enhanced mining conditions and the restoration of operational sequencing following earlier weather-related disruptions.
Coal sales rose at a faster pace than production, increasing 10.4% to 3.2 million tonnes. This divergence reflects improved logistics flow and the drawdown of previously accumulated stockpiles. The operational data suggests that the company benefited not only from production stability but also from improved timing in sales realization, particularly in export-linked Supply chains.
The Bengalla Mine, which remains the company’s most significant production contributor, operated at a steady annualized run rate during the quarter. Meanwhile, New Acland demonstrated mixed performance, with slightly lower ROM production offset by stable sales volumes. Together, these dynamics highlight a portfolio-level balance between production strength and operational variability across assets.
Pricing Environment and Revenue Stability
Global coal markets provided a supportive backdrop during the quarter. The average realised sales price for the group stood at A$140.7 per tonne, reflecting a modest 1.2% increase from the prior quarter. This stability was achieved despite currency fluctuations and evolving global energy Demand patterns.
Benchmark pricing conditions improved significantly over the period. The gC NEWC 6000 index rose 16.5% quarter-on-quarter, supported by heightened energy security concerns in Asia and tighter supply expectations. Similarly, API-5 pricing strengthened, reinforcing a generally firmer thermal coal pricing environment.
Despite these favorable benchmark movements, realised pricing growth for the company remained contained, indicating the impact of contract structures and currency translation effects. Nevertheless, pricing stability played a critical role in supporting revenue consistency during the quarter.
Earnings Performance and Cost Dynamics
Underlying EBITDA for the quarter increased by 21.7% to $130.1 million, reflecting a combination of higher sales volumes and disciplined cost management. The result highlights operational Leverage from increased throughput, particularly at Bengalla, where production efficiency improved materially.
A key driver of cost performance was the reduction in FOB cash costs at Bengalla Mine, which fell to $74.0 per sales tonne, a 12.4% improvement from the previous quarter. This reduction was largely attributed to higher sales volumes and improved operational efficiency, demonstrating the mine’s scalability in response to favorable conditions.
At the group level, cost performance was also supported by improved logistics efficiency and reduced system disruptions. However, variability remains across assets, particularly at New Acland, where strip ratios and rail constraints influenced short-term cost dynamics.
Overall, the earnings profile reflects a quarter where Volume growth translated effectively into improved profitability metrics, supported by cost discipline and operational execution.
Safety and Operational Risk Profile
Safety performance remains a central operational focus for the group. During the quarter, the company recorded mixed safety indicators, with improvements in high potential event frequency rates but a rise in the All-Injury Frequency Rate on both quarterly and rolling averages.
The High Potential Event Frequency Rate decreased significantly to 1.21 from 4.85 in the previous quarter, indicating progress in managing critical risk exposures. However, the increase in injury frequency metrics suggests ongoing challenges in maintaining consistent frontline safety performance.
This divergence underscores the complexity of safety management in large-scale mining operations, where improvements in critical risk control can coexist with variability in minor incident rates. The company continues to emphasize monitoring and mitigation strategies across operational sites.
Asset-Level Performance: Bengalla and New Acland
Bengalla Mine delivered a particularly strong quarter, with ROM production increasing 16.3% and saleable coal output rising 13.5%. The operation benefited from favorable mining conditions, improved strip ratios, and recovery from earlier disruptions.
Coal sales at Bengalla increased 14.1%, supported by both production strength and improved port logistics. The return of more stable vessel queues at the Port of Newcastle contributed to smoother export flows. Importantly, Bengalla achieved full utilization of its production capacity on a temporary basis, reinforcing its importance within the group portfolio.
New Acland Mine experienced a more mixed operational outcome. ROM coal production declined by 9.0%, primarily due to increased strip ratios. However, coal sales rose modestly, reflecting timing effects and product mix adjustments. The mine also progressed infrastructure works, including road realignment projects, which are expected to shape its medium-term development trajectory.
Strategic Investments and Growth Optionality
The company’s strategic Investment in Malabar Resources continued to deliver operational milestones at the asset level. Notably, developments at the Longwall project and infrastructure commissioning, including overland conveyor systems and water treatment facilities, signal progress toward enhanced underground productivity.
These investments provide the company with exposure to long-term coal production assets outside its core operations. While contribution remains relatively modest in the current period, the progression of these assets adds depth to the company’s broader portfolio strategy.
Balance Sheet Strength and Capital Structure Developments
A key financial highlight of the quarter was the strengthening of the company’s capital structure. Available cash stood at $571.6 million, comprising cash holdings and fixed income investments. This Liquidity position provides substantial financial flexibility in the near term.
The company also completed a significant refinancing initiative involving the issuance of $300 million in senior unsecured convertible notes due 2032, alongside the repurchase of nearly all existing 2029 notes. This transaction materially extends the maturity profile of the company’s debt and reduces near-term refinancing risk.
The new structure introduces a lower fixed coupon and extends financial visibility into the next decade, while maintaining optionality through associated hedging arrangements. Additionally, the ongoing share buy-back program remained active, although no shares were repurchased during the quarter.
Conclusion
The latest quarterly performance from New Hope Corporation Limited reflects a period of operational strength supported by improved production volumes, stable pricing conditions, and enhanced cost efficiency. While asset-level variability remains evident, particularly between Bengalla and New Acland, the group’s consolidated performance demonstrates resilience in a fluctuating global coal market. Strengthened liquidity and an extended debt maturity profile further reinforce financial stability, positioning the company with increased flexibility heading into the remainder of FY26.

 Nov 13, 2026
 Please wait processing your request...