
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Australian Rare Earths is an early-stage explorer focused on clay-hosted rare earth deposits — a deposit type that has historically been dominated by China and is now attracting growing Western interest due to its lower processing costs and simpler extraction characteristics relative to hard rock systems. AR3 offers early exposure to this emerging segment of the rare earth market, but it remains firmly in the exploration phase with all the attendant uncertainties that implies.
The investment case is simple in structure: either AR3 defines a clay-hosted resource of sufficient scale and grade to attract development interest, or it does not. The binary nature of exploration-stage investing must be clearly understood.
- The Clay-Hosted Rare Earth Opportunity
Clay-hosted (or ionic adsorption) rare earth deposits are a deposit type of growing strategic importance to Western supply chain planners.
Why clay-hosted deposits are strategically significant:
- China produces the majority of the world's heavy rare earths from ionic clay deposits, giving it a near-monopoly in this deposit category
- Clay-hosted deposits allow rare earth ions to be extracted via simple leaching — typically using ammonium sulphate solution — without the energy-intensive crushing and flotation required for hard rock deposits
- This translates to materially lower capital expenditure and operating costs, improving project economics
- Western alternatives to Chinese clay deposits are scarce, making successful development of non-Chinese clay-hosted resources a genuine supply chain priority
AR3's positioning within this niche is its primary strategic rationale.
- Business Model & Current Activities
AR3 is engaged in the foundational activities of exploration-stage rare earth development:
- Exploration drilling to test and extend rare earth mineralisation across its tenement package
- Resource definition toward a first JORC-compliant resource estimate
- Metallurgical testing to establish whether the clay-hosted mineralisation is amenable to efficient leaching and processing
None of these activities generate revenue. Their value is entirely prospective — they either confirm or deny the presence of an economically viable deposit.
- Financial Position
AR3 is a capital consumer at this stage of development:
- No revenue from operations
- Expenditure focused on drilling, assaying, and technical studies
- Dependent on equity capital markets for ongoing funding
- Dilution risk is a persistent feature of exploration-stage investing that compounds with each successive capital raise
The financial sustainability of AR3's exploration program is a function of market appetite for speculative rare earth equity, which is sensitive to NdPr pricing, sector sentiment, and broader risk-on/risk-off dynamics.
Stock Performance
Australian Rare Earths Ltd (ASX: AR3) last traded at AUD 0.14, unchanged from its previous close, reflecting flat intraday and weekly performance. However, the stock has declined 20.00% over the past month and 31.70% over three months, indicating recent weakness.
Despite this, AR3 has delivered strong gains over a longer horizon, rising 33.33% in six months, 174.51% over nine months, and 94.44% over the past year. The performance suggests short-term pressure following a strong rally, highlighting volatility in the rare earths segment.
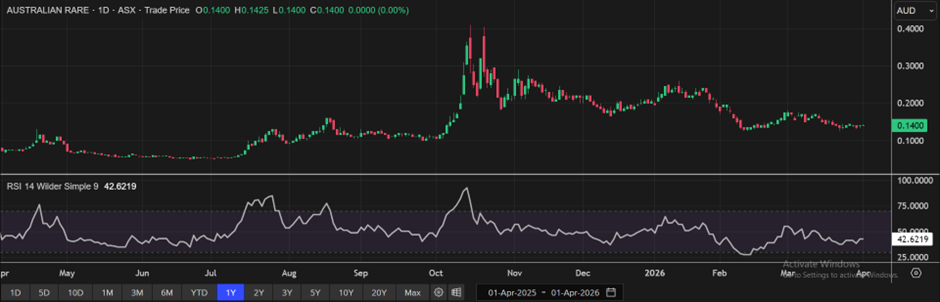
Data source: EODHD/Others as of April 01, 2026
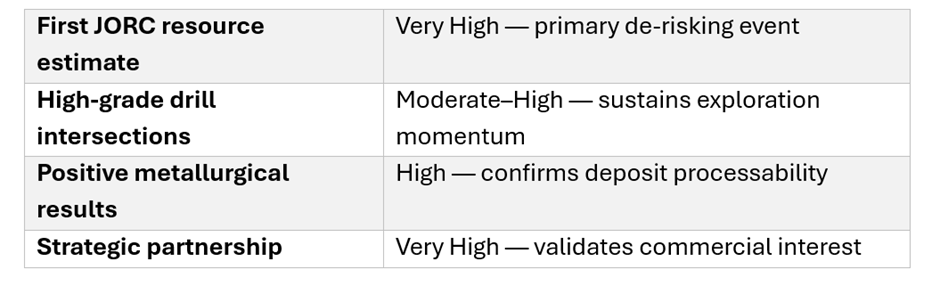
- Investment Catalysts
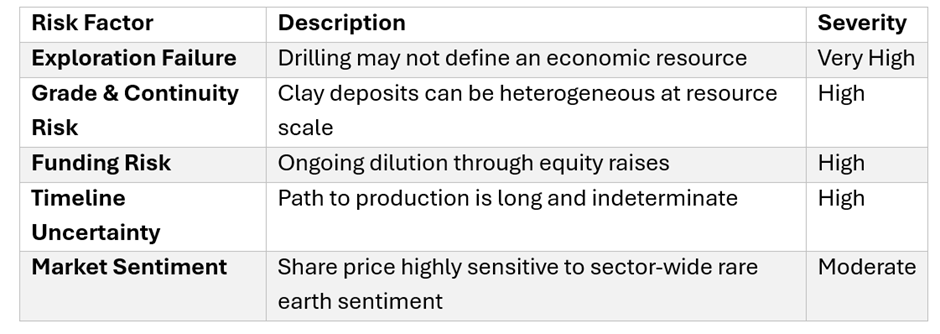
- Risk Assessment
- Bull & Bear Case
Bull Case: AR3 defines a large-scale, high-grade clay-hosted rare earth resource, attracting strategic interest from a development partner or larger mining company. Metallurgical testwork confirms low-cost processing economics, and the deposit is advanced toward feasibility as Western demand for non-Chinese clay-hosted rare earth supply intensifies.
Bear Case: Drilling fails to define a resource of sufficient scale or grade to justify development. Metallurgical results reveal processing challenges that undermine the low-cost extraction thesis. Capital raises dilute existing investors progressively, and the stock drifts lower in a sentiment-driven decline.
- Investment Conclusion
AR3 is a genuine early-stage exploration play in a strategically relevant deposit category. The clay-hosted rare earth thesis is sound at a macro level, and the absence of significant non-Chinese clay deposits in developed markets creates a real commercial opportunity for successful developers. Whether AR3's tenements contain such a deposit is a question that only drilling can answer.
Investors should size positions accordingly — small enough to absorb the risk of exploration failure, large enough to participate meaningfully in a positive discovery outcome.
Best suited for: Speculative investors with small position sizing, seeking early exposure to the clay-hosted rare earth segment with an understanding of binary exploration risk.


 Nov 13, 2026





 Please wait processing your request...