
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Nolans Project fully permitted with 38-year mine life, targeting 4,400tpa NdPr oxide, 4% of global supply.
- De-risked funding via US/South Korea export agencies and offtake deals, shifting risk to execution post-FID.
- Binary re-rating potential at FID, with strong EBITDA margins from high-value NdPr focus.
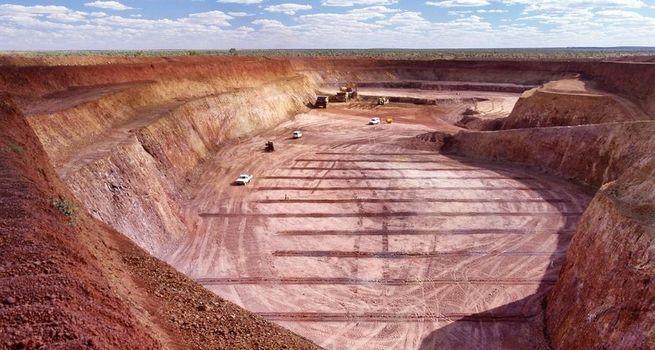
Arafura Rare Earths (ASX:ARU), an ASX-listed commodity company, occupies a rare position in the critical minerals landscape: a pre-production developer with a fully permitted, largely financed, globally significant asset that is genuinely close to a construction decision. The Nolans Project in the Northern Territory is one of the most advanced rare earth developments outside China, and Arafura's trajectory from speculative explorer to near-term producer is now largely a function of execution rather than feasibility.
The investment case is straightforward in structure but carries meaningful binary risk — success at the Final Investment Decision (FID) stage unlocks a step-change re-rating; delays or cost escalation will compress the thesis materially.
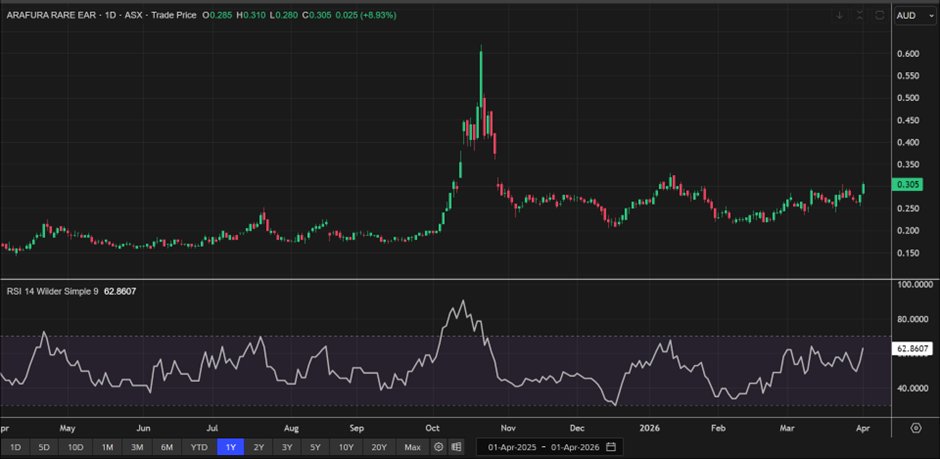
Arafura Rare Earths recorded 8.928% surge in its share price to $0.305 on exceptional volume of 97,717,294 shares. Bid/offer spanned $0.305-$0.310, signaling strong momentum toward Nolans Project milestones. The $1.31B market cap stock benefits from de-risked funding progress in the rare earth sector.
Source: EODHD/Others
- Business Model
Arafura's target operating model is full vertical integration across:
- Mining — open pit extraction at Nolans, Northern Territory
- Beneficiation — on-site concentration of rare earth mineral content
- Downstream processing — production of separated NdPr oxide for direct sale to magnet manufacturers
This integrated approach is strategically deliberate. As with Lynas, the processing layer — not the mining layer — is where margin is created and where global supply chain bottlenecks are most acute. An integrated producer commands better pricing, stronger customer relationships, and more durable competitive positioning than a concentrate seller dependent on third-party refiners.
- Core Asset: Nolans Project
The Nolans Project is the defining asset of the Arafura investment case and one of the most consequential rare earth developments in the Western world.
Key project parameters:
- Mine life of approximately 38 years, providing exceptional long-run production visibility
- Targeted annual NdPr output of approximately 4,400 tonnes of NdPr oxide
- Estimated global market contribution of ~4% of NdPr supply — a scale that renders Nolans a globally relevant rather than merely regional project
- Full permitting secured, removing a major development-stage risk that stalls many peers
The scale and permit status of Nolans distinguishes Arafura from the large number of rare earth developers whose projects remain conceptual, uncommitted, or mired in regulatory uncertainty.
- Funding & Strategic Partnerships
Arafura has made material progress in de-risking the historically most difficult phase of any major development project: securing funding.
The company has engaged with:
- Export credit agencies from the United States and South Korea, reflecting the geopolitical importance of NdPr supply diversification
- Government-backed loan facilities, reducing dependence on equity markets and limiting dilution risk
- Strategic customer offtake agreements, which provide revenue visibility pre-production and underpin lender confidence
This funding structure is a meaningful differentiator. The majority of rare earth developers at a comparable project stage remain entirely dependent on equity markets, exposing investors to continuous dilution. Arafura's partially de-risked funding base shifts the central risk from capital availability toward construction execution.
- Financial Profile & Outlook
Arafura is currently pre-revenue, and its valuation is necessarily forward-looking. Key financial considerations include:
- Current basis of value: Probabilistic net present value of Nolans, discounted for execution, pricing, and timeline risk
- Post-production earnings profile: Strong EBITDA margins are anticipated, supported by a product mix weighted toward high-value NdPr and long-term contracted offtake
- Re-rating trigger: The transition from developer to producer — commencing at FID — is expected to compress the discount rate applied to Nolans, driving a material valuation uplift
The most important near-term financial variable is not earnings, but capital cost management and FID timing.
- Investment Catalysts
Arafura's share price is expected to be driven by a sequence of binary milestones:
|
Catalyst |
Expected Impact |
|
Final Investment Decision (FID) |
High — primary re-rating event |
|
Financing close |
High — validates project economics |
|
Construction commencement |
Moderate — confirms execution momentum |
|
First production |
High — transition to revenue-generating entity |
|
NdPr price cycle |
Ongoing — leveraged earnings sensitivity |
Each milestone achieved reduces project risk and should compress the valuation discount applied by the market.
- Risk Assessment
|
Risk Factor |
Description |
Severity |
|
Execution Risk |
Cost overruns or delays in construction and commissioning |
High |
|
FID Delay |
Prolonged capital raising or partner negotiations |
High |
|
NdPr Price Volatility |
Revenue highly leveraged to a single commodity price |
High |
|
Funding Gap |
Residual financing requirements not yet closed |
Moderate |
|
Ramp-Up Risk |
Operational underperformance in early production years |
Moderate |
- Bull & Bear Case
Bull Case: FID is confirmed on schedule, construction proceeds within cost parameters, and first production is achieved in line with guidance. A rising NdPr price environment amplifies early-stage earnings, and Arafura re-rates toward a producer multiple. Multi-year revenue visibility from contracted offtake supports continued valuation expansion.
Bear Case: Capital cost escalation forces additional equity raises, diluting existing holders. FID is deferred, extending the pre-revenue period and sustaining the valuation discount. A softening NdPr price environment erodes project economics and reduces lender appetite.
- Investment Conclusion
Arafura is one of the most credible pre-production rare earth opportunities available to equity investors globally. The Nolans Project is real, permitted, and of genuine global scale. The funding de-risking work undertaken distinguishes Arafura from the majority of its developer peers.
The investment proposition is, however, inherently binary in the near term. Investors must be comfortable with development-stage execution risk and commodity price exposure in exchange for the potential step-change valuation re-rating that successful project delivery would generate.
Best suited for: Growth and thematic investors with a medium-to-long investment horizon and tolerance for pre-production risk.


 Nov 13, 2026





 Please wait processing your request...