
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Hybrid model: Tomingley gold mine generates cash flow, funding Dubbo polymetallic rare earth project.
- Dubbo offers NdPr plus zirconium/niobium diversification, advanced feasibility in top jurisdiction.
- Sum-of-parts valuation discount; re-rating via partnerships or FID on Dubbo.
ASX-listed rare earth company, Alkane Resources (ASX:ALK) presents an unusual investment proposition within the Australian critical minerals sector: a producing gold company with a substantial, largely unpriced rare earth development embedded within the same corporate structure. This dual-asset profile creates a risk/return profile that is distinct from both pure gold producers and pure rare earth developers — offering downside protection through operating cash flow while retaining meaningful upside optionality through the Dubbo Project.
The key question for investors is whether the market will ultimately ascribe full value to both assets, or whether Dubbo will remain a structural discount to net asset value for an extended period.
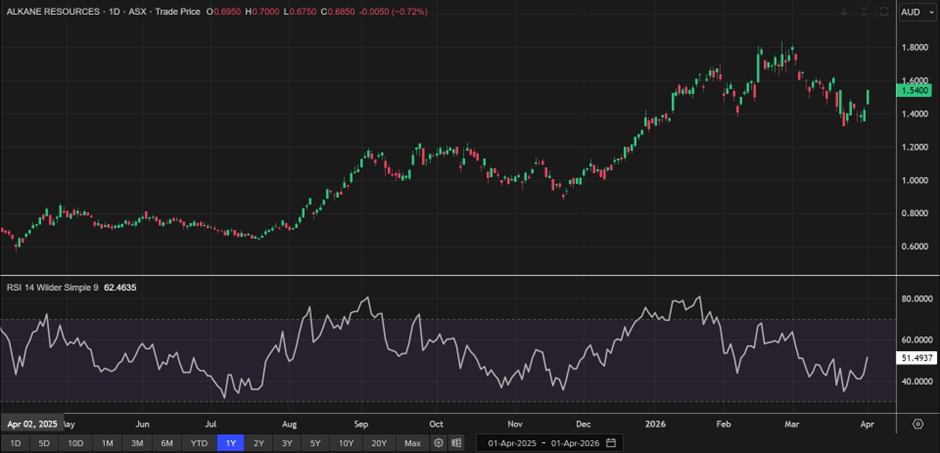
Alkane Resources rose 8.450% to $1.540, with healthy volume of 4,713,100 shares traded.
Tight bid/offer at $1.535-$1.540 underscores investor confidence in its hybrid gold-rare earth model.
At $1.94B market cap, ALK's performance highlights Dubbo Project optionality alongside Tomingley cash flow.
Source: EODHD/Others
- Business Structure
3Alkane operates two materially distinct businesses:
- Gold production — Tomingley Gold Operations, New South Wales, generating ongoing revenue and cash flow
- Critical minerals development — Dubbo Project, New South Wales, a large-scale polymetallic deposit at advanced feasibility stage
This structure is both a strength and a complexity. The gold operations provide financial resilience that most rare earth developers lack entirely, allowing Alkane to fund corporate costs and development expenditure without continuous recourse to equity markets. However, the hybrid structure can dilute market focus, with rare earth investors bypassing the stock in favour of pure-play exposure and gold investors undervaluing the development optionality.
- Tomingley Gold Operations
Tomingley provides Alkane with a genuine competitive advantage over development-stage peers: operating cash flow.
Key attributes:
- Consistent gold production supporting the balance sheet through the Dubbo development timeline
- Reduces reliance on equity markets, limiting dilution risk
- Provides management with operational credibility that pure developers lack
- Underground expansion at Tomingley extends mine life and cash flow runway
While gold is not Alkane's strategic focus, it is the financial foundation that makes the Dubbo development thesis credible.
- Core Development Asset: Dubbo Project
The Dubbo Project is one of Australia's largest undeveloped polymetallic critical mineral deposits and represents the long-term value creation thesis for Alkane shareholders.
Key characteristics:
- Substantial rare earth content, including NdPr, alongside zirconium, hafnium, and niobium
- Multi-commodity output profile reduces single-commodity revenue risk and improves project economics
- Long mine life with significant resource base
- Advanced feasibility and engineering work completed
- Alignment with government strategic priorities for critical mineral supply diversification
The polymetallic nature of Dubbo is both a strength and a complexity. On the one hand, revenue diversification across rare earths, zirconium, and hafnium improves project resilience. On the other hand, the processing flowsheet is more technically complex than a single-commodity project, and market valuation of multi-product streams requires more sophisticated analysis.
- Financial Position
Alkane's financial profile is meaningfully stronger than the typical rare earth developer:
- Gold revenue provides a recurring income stream and positive operating cash flow
- Balance sheet flexibility is preserved through reduced equity dilution requirements
- Capital requirements for Dubbo are substantial, but the company's operating base strengthens its capacity to engage with project financiers and strategic partners
The principal financial risk is the capital intensity of a full Dubbo development decision, which will likely require external financing, strategic partnerships, or both.
- Valuation Dynamics
Alkane's valuation presents an interesting case study in sum-of-the-parts complexity.
The gold operations can be valued using conventional producer metrics (EV/EBITDA, NAV). The Dubbo Project is valued using development-stage methodology (risked NPV). In practice, the market has historically applied a meaningful discount to the combined entity, treating Dubbo as optionality rather than core value.
A re-rating toward full sum-of-the-parts value would require one or more of:
- A strategic partnership or off-take agreement for Dubbo
- A positive FID announcement with confirmed financing
- A sustained rise in rare earth and/or zirconium pricing
- Risk Assessment
|
Risk Factor |
Description |
Severity |
|
Dubbo Development Timeline |
Path to production remains long and capital-intensive |
High |
|
Market Perception Risk |
Hybrid structure may suppress re-rating vs pure-play peers |
Moderate |
|
Gold Price Sensitivity |
Operating earnings leveraged to gold price movements |
Moderate |
|
Capital Requirements |
Dubbo will require significant external financing |
High |
|
Processing Complexity |
Polymetallic flowsheet introduces technical execution risk |
Moderate |
- Bull & Bear Case
Bull Case: Dubbo secures a strategic partnership or government-backed financing, triggering a material re-rating of the embedded rare earth and critical mineral value. Gold cash flows sustain the balance sheet through the development period. The polymetallic product suite attracts premium pricing from diversified end-use customers.
Bear Case: Dubbo development is deferred indefinitely due to capital intensity, and the market continues to treat it as a low-probability option. Gold price weakness compresses the operating earnings that underpin balance sheet confidence. The structural discount to sum-of-the-parts NAV persists.
- Investment Conclusion
Alkane offers a structurally differentiated entry point into Australian critical minerals — one that is buffered by operating cash flow and therefore suited to investors who seek rare earth exposure without accepting the full binary risk of a pre-revenue developer. The gold operations provide genuine financial resilience; the Dubbo Project provides genuine long-term upside.
The central challenge is patience. Dubbo's path to production is longer and more capital-intensive than Arafura's Nolans, and the market is unlikely to ascribe full value until a firm development pathway is established.
Best suited for: Value-oriented investors comfortable with a longer development horizon and seeking rare earth optionality with downside protection from operating cash flows.


 Nov 13, 2026





 Please wait processing your request...