
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
4DMedical Ltd (ASX:4DX) is an Australian healthcare technology company that has developed proprietary four-dimensional respiratory imaging technology. The company's core innovation, known as XV Technology, enables clinicians to visualise and quantify lung function in ways that traditional imaging methods such as standard CT scans and X-rays cannot.
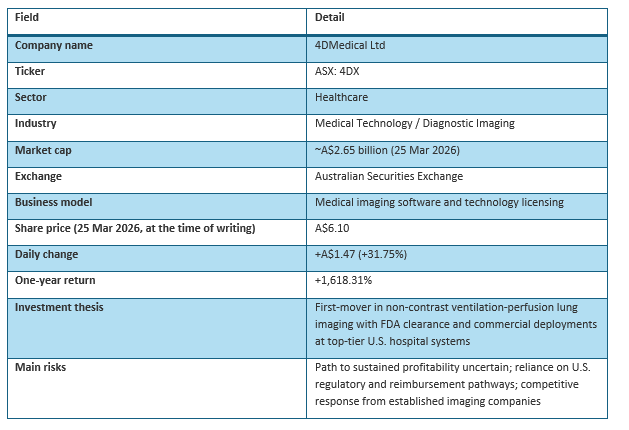
Founded in Melbourne, 4DMedical listed on the ASX with the ticker 4DX and has since grown to become one of the most closely watched medtech stocks on the exchange. As of 25 March 2026, the company's market capitalisation stood at approximately A$2.65 billion, placing it firmly in mid-cap territory and reflecting the market's substantial expectations for its commercial trajectory.
At a Glance: 4DMedical
Business Model and Technology
4DMedical's core product is its CT:VQ imaging solution, which the company describes as the first and only non-contrast ventilation-perfusion imaging technology to receive FDA 510(k) clearance. In plain language, this means the technology can assess how air and blood flow through the lungs without requiring the patient to inhale or be injected with a contrast agent, which is a significant advantage in terms of patient comfort, safety, and workflow efficiency.
The technology works by applying proprietary software algorithms to standard CT scan data. This means hospitals do not need to purchase entirely new hardware; they can use their existing CT scanners and layer 4DMedical's software on top. This software-centric model is attractive from a business perspective because it reduces the barrier to adoption and allows for recurring revenue through licensing fees and per-scan charges.
The company also offers Imbio Technology, a complementary platform acquired to expand its analytical capabilities. Together, these platforms position 4DMedical as a comprehensive lung-function analytics provider.
The FDA Clearance Catalyst
The single most important catalyst behind 4DMedical's extraordinary share price performance has been the FDA 510(k) clearance for CT:VQ, which was granted in September 2025. This regulatory milestone opened the door to the U.S. market, which 4DMedical estimates represents an initial addressable market exceeding US$1.10 billion annually.
For a medtech company, FDA clearance is a make-or-break event. It validates the technology's safety and efficacy in the eyes of the world's largest healthcare market and triggers a cascade of commercial opportunities: hospital evaluations, pilot programmes, reimbursement coding, and ultimately widespread adoption.
Following the clearance, 4DMedical announced commercial deployments at several of America's most prestigious hospital systems, including Mayo Clinic, Stanford Health Care, University of Miami Health System, Cleveland Clinic, and UC San Diego Health. These are not minor pilot sites; they are globally recognised institutions whose adoption lends significant credibility to the technology and creates reference accounts that can accelerate further sales.
The Centers for Medicare and Medicaid Services (CMS) has confirmed reimbursement under Category III CPT codes, which is an important step toward making the technology economically viable for hospitals. Category III codes are temporary codes assigned to emerging technologies; eventual progression to Category I status would provide more permanent and typically higher reimbursement rates.
Financial Performance
Despite the commercial progress, investors should be aware that 4DMedical remains a loss-making company. For the first half of the 2025 financial year, the company reported sales of approximately A$2.85 million against a net loss of approximately A$154 million. While the adjusted net loss showed improvement, the gap between revenue and costs remains substantial.
The company has funded its growth through capital raisings, including share issuances in January and March 2026. Dilution is a real consideration for existing shareholders, and investors should monitor the company's cash runway and capital-raising activity closely.
The path to profitability will depend on the speed of commercial adoption, the pricing model, the mix between one-off and recurring revenue, and the pace of operating cost growth. Management has indicated that the U.S. market is the primary revenue growth engine, but converting prestigious hospital deployments into a high-volume, repeatable revenue stream takes time.
Competitive Landscape
4DMedical operates in a specialised niche within the broader medical imaging industry. The global medical imaging market is dominated by large conglomerates such as Siemens Healthineers, GE HealthCare, and Philips, all of which have substantial R&D budgets and deep relationships with hospital systems worldwide.
However, 4DMedical's specific technology, non-contrast ventilation-perfusion imaging using software applied to existing CT hardware, does not have a direct equivalent from these large players as of the date of this analysis. The company's first-mover advantage and regulatory clearance provide a meaningful, though not insurmountable, moat.
A potential risk is that a larger competitor could develop a similar software-based solution and leverage its existing hospital relationships to gain market share quickly. Alternatively, entirely different approaches to lung-function assessment could emerge from the research pipeline.
Risks
- Profitability timeline: The company is burning cash, and there is no guarantee that revenue will scale fast enough to reach profitability before additional capital raisings are required.
- Reimbursement uncertainty: Category III CPT codes are temporary. If reimbursement rates are set too low or if progression to Category I codes is delayed, hospital adoption could slow.
- Regulatory risk: While FDA clearance has been obtained for the U.S., the company will need regulatory approvals in other jurisdictions to expand globally.
- Dilution: Ongoing share issuances to fund operations reduce existing shareholders' ownership percentage.
- Execution risk: Converting early hospital deployments into a scalable, profitable business requires operational excellence in sales, customer support, and technology development.
Section Recap
4DMedical is a high-conviction, high-risk play on the future of lung diagnostic imaging. The FDA clearance, blue-chip hospital deployments, and billion-dollar addressable market provide a compelling narrative, but the financial reality is that the company is still far from profitability and reliant on capital markets for funding. Beginner investors should understand that the 1,618 per cent one-year return reflects speculative enthusiasm as much as fundamental progress, and that the path forward is far from guaranteed.


 Nov 13, 2026





 Please wait processing your request...