
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Recent Mandalay Resources merger (August 2025) strengthens company's financial position and operational expertise
- Increased demand for niobium concentrate, yttrium, and rare earth products driving Dubbo project expansion considerations
- Strategic positioning in NSW Central West provides proximity to growing technology hub and established infrastructure
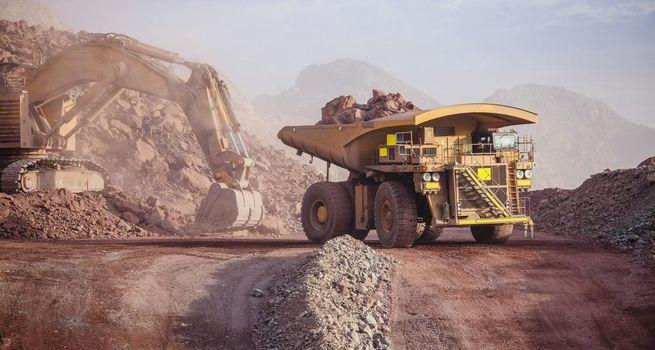
Alkane Resources Ltd (ASX:ALK) represents a diversified rare earth and specialty metals play focused on developing the Dubbo Zirconia Project in New South Wales. Trading at A$1.39, down 3.13% on March 27, 2026, Alkane offers exposure to an advanced-stage rare earth and specialty metals project with substantial production expansion optionality. The recent merger with Mandalay Resources Ltd (August 2025) strengthened the company's financial position and operational capabilities.
The Dubbo project's strategic positioning within the NSW Central West region, 30 kilometres south of Dubbo, provides geographic advantages including proximity to existing infrastructure and a growing technology sector hub. Unlike companies focused exclusively on rare earths, Alkane's diversified product portfolio—zirconium, niobium, yttrium, and rare earth elements—provides revenue diversification and reduces single-commodity exposure.
For investors evaluating 'Is Alkane Resources a good investment?', the analysis hinges on understanding the Dubbo project's development timeline, market demand for specialty metals, and the strategic rationale of the Mandalay merger. This comprehensive analysis examines Alkane's positioning, the Dubbo project's catalysts, and the investment risks warranting careful investor evaluation.
About the Company
Alkane Resources Limited is a diversified minerals company engaged in exploration and mining of gold, copper, zirconium, niobium, and rare earth elements across operations in Australia and Sweden. The company's primary development focus centres on the Dubbo Zirconia Project in New South Wales, which hosts substantial reserves of zirconium, niobium, yttrium, and rare earth elements.
The Dubbo project commenced in response to growing global demand for specialty metals and rare earths from defence, aerospace, and industrial applications. The project's technical characteristics—particularly the vertically integrated deposit containing multiple valuable products—provide unique commercial advantages. The ability to extract multiple valuable products from a single orebody improves project economics and risk-adjusted returns.
The August 2025 merger with Mandalay Resources Ltd, a Canadian mining company with significant operational and financing expertise, substantially strengthened Alkane's position. Mandalay brought additional capital, operational competence, and international experience that should accelerate the Dubbo project's development trajectory. This merger represents strategic validation of the Dubbo project's significance and commercial viability.
Why the Stock Is Moving
Alkane stock analysis reveals that the company benefits from improved demand conditions for niobium, yttrium, and rare earth products. Increased demand from defence applications, aerospace modernisation, and emerging technology sectors has created a more favourable macro environment for specialty metals producers. Management's discussion of expanded production scenarios reflects confidence in long-term demand sustainability.
The Mandalay Resources merger has provided positive momentum for Alkane shares. The combination of Alkane's advanced Dubbo project with Mandalay's operational expertise and financing capabilities has created a stronger entity capable of executing larger-scale development projects. This strategic combination has been positively received by institutional investors.
Industry Trends
The global specialty metals market is experiencing growth driven by defence spending modernisation, aerospace production increases, and emerging technology sector expansion. Niobium, yttrium, and rare earth elements are critical inputs for advanced alloys, permanent magnets, and electronic components essential for modern military and commercial applications.
Rare earth market dynamics have shifted materially in favour of new Western production capacity. China's controlling influence has created supply security concerns among Western governments and defence contractors. This geopolitical tension has translated into explicit government support for new Western rare earth production, creating a favourable demand environment for projects like Dubbo.
The vertical integration inherent in the Dubbo deposit—containing multiple valuable products extractable from a single orebody—provides competitive advantages relative to single-commodity producers. This integration improves project economics, as the highest-margin products subsidise the development of lower-margin products, improving overall project viability.
Financial Performance
Alkane Resources has been advancing the Dubbo project through feasibility and development phases. While specific production timelines and capital expenditure figures have not been recently disclosed, the company's merger with Mandalay Resources and discussions of expanded production scenarios suggest accelerated project development. The combination of Alkane's resource base with Mandalay's capital and operational capabilities positions the company for advancement toward production.
The Dubbo project's economics benefit from the vertically integrated deposit, which allows extraction of multiple valuable products. This multi-product approach improves the project's return on capital and reduces dependency on single-commodity price fluctuations. The 200+ year mine life based on large defined resources suggests decades of production optionality.
Financial performance metrics remain limited by the project's development stage, but improving market conditions and stronger balance sheet position from the Mandalay merger should support acceleration toward production. The company maintains financial flexibility to advance the Dubbo project toward commercial production without excessive shareholder dilution.
Investment Risks
Project execution risk represents the primary concern. The Dubbo project is a complex, vertically integrated mining and processing operation. Successfully constructing, commissioning, and operating the facility requires flawless execution across multiple technical domains. Any cost overruns, schedule delays, or operational challenges could materially impact shareholder returns.
Commodity price volatility, particularly for rare earth oxides and specialty metals, introduces earnings volatility. While the multi-product approach provides some diversification, declining prices for key products would compress project economics. Investors must monitor global demand trends for rare earths and specialty metals as material risk factors.
Regulatory and environmental risks warrant consideration. The Dubbo project operates within New South Wales regulatory frameworks. Changes in environmental standards, mining approvals processes, or community relations could delay or derail project development. Investors must monitor regulatory developments in NSW carefully.
Future Growth Drivers
The Dubbo project's advancement toward production represents the primary growth catalyst. Each feasibility study completion, financing arrangement, and construction milestone would reduce execution risk and validate commercial viability, supporting share price appreciation.
Strategic partnerships or joint ventures with larger mining companies, defence contractors, or specialty materials users could provide development capital and market offtake certainty. Partnership announcements would likely trigger share price appreciation and reduce execution risk for shareholders.
Long-Term Investment Perspective
From a 5-10 year perspective, Alkane Resources represents an interesting exposure to vertically integrated rare earth and specialty metals development. The Dubbo project's technical characteristics—multiple valuable products, large resource base, 200+ year mine life—provide structural advantages that should support long-term profitability once production achieves steady state.
For long-term investors seeking exposure to rare earth and specialty metals production with reduced single-commodity price risk, Alkane merits consideration. The Mandalay Resources merger strengthens the company's execution capability. However, investors must maintain realistic expectations regarding development timelines and maintain patience through a potentially extended development phase before production commencement.
Conclusion
Alkane Resources Ltd represents a distinctive opportunity within the rare earth and specialty metals sector, with the Dubbo Zirconia Project offering vertically integrated development optionality. The August 2025 merger with Mandalay Resources strengthened the company's operational capabilities and financial position, supporting accelerated project development.
The Alkane Resources share price outlook through 2030 appears constructive if the Dubbo project progresses toward production on anticipated timelines. For investors asking 'Is ALK a good investment?', the answer is affirmative for patient investors with 5+ year time horizons and conviction in specialty metals and rare earth demand growth. However, development-stage risk requires position sizing discipline. Alkane merits consideration as a tactical holding within diversified rare earth sector allocations.

 Nov 12, 2026
 Please wait processing your request...