
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Beach Energy acquired a 25% stake in Omega's joint venture, validating the Taroom Trough exploration thesis.
- Rig mobilisation is scheduled for mid-May 2026, with first drilling results expected by mid-2026.
- Omega is positioned to benefit from anticipated East Coast gas supply shortfalls forecast beyond 2029.
- The company operates in Queensland's under-explored Taroom Trough, which has been compared to prolific US unconventional basins.
Omega Oil & Gas Limited (ASX:OMA) has captured investor attention as the company approaches a pivotal drilling phase in Queensland's Taroom Trough. With rig mobilisation scheduled for mid-May 2026 and Beach Energy having recently taken a 25% stake in the company-led joint venture, OMA is positioned at an inflection point that could reshape its valuation.
The broader energy market context is supportive. Oil and gas prices remain elevated amid supply constraints and geopolitical uncertainty, while Australia's East Coast gas market faces well-documented supply shortfalls in the coming years. For Omega, these macro dynamics add urgency and significance to its upcoming exploration results.
This comprehensive Omega Oil & Gas stock analysis examines the catalysts driving investor interest, the company's strategic positioning, and what the latest news means for shareholders.
About Omega Oil & Gas
Omega Oil & Gas is an oil and gas exploration and evaluation company focused on unlocking hydrocarbon resources in Queensland's Taroom Trough. The company is headquartered in Australia and operates through a joint venture structure, holding a 45% stake alongside Tri-Star (30%) and Beach Energy (25%).
The Taroom Trough is an under-explored sedimentary basin that industry experts have compared to prolific unconventional basins in the United States. The region sits within a proven hydrocarbon system with what the company describes as internationally significant upside potential.
Omega's flagship asset is the Canyon Project, supported by a newly awarded 750 square kilometre exploration permit (PLR2025-1-9) in the Taroom Trough. The company positions itself as an agile, well-funded explorer with deep Queensland expertise.
The company's management team brings significant experience in Queensland exploration, having been involved in previous successful programs across the state's sedimentary basins. This operational knowledge provides an edge in site selection, drilling design, and regulatory navigation that can improve the probability of exploration success.
Why OMA Stock Is Moving
The most significant catalyst for OMA has been Beach Energy's decision to take a 25% stake in the Omega-led joint venture. Beach Energy is a AUD 2.6 billion company, and its participation provides substantial validation of the exploration thesis and the quality of the Taroom Trough opportunity.
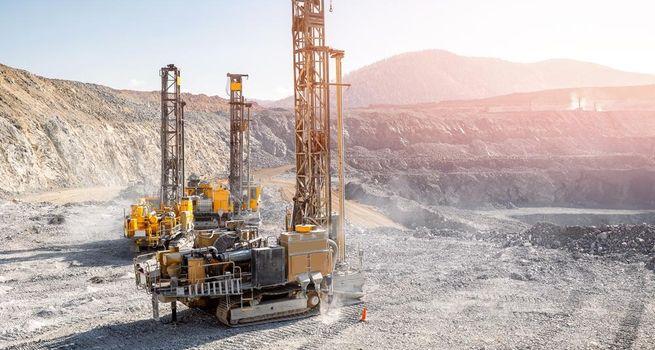
Operationally, the company is advancing rapidly toward drilling. Wellheads and casing are due to arrive in early May 2026, with rig mobilisation scheduled for mid-May. First drilling results are anticipated by mid-2026, making the next three to six months a critical period for the stock.
The broader Taroom Trough is experiencing elevated activity, with multiple companies including Elixir and Shell conducting material exploration programs in the region. This industry-wide interest further validates the prospectivity of the basin.
Resource-to-reserve maturation, expected in late 2026, represents another potential inflection point. If initial drilling confirms commercial hydrocarbons, the process of converting speculative resources into proven reserves could trigger fundamental revaluations by analysts and institutional investors who apply reserve-based valuation methodologies.
The government's competitive tender process for the Taroom Trough acreage adds credibility to the exploration thesis. When government agencies award exploration permits through competitive processes, it signals that the geological potential has been independently assessed and validated at the regulatory level.
Industry Trends
Australia's East Coast gas market faces a structural supply challenge. Multiple industry forecasts project significant gas supply shortfalls beginning around 2029, driven by declining output from existing fields and growing demand from industrial and power generation users.
This supply gap is creating renewed interest in exploration and development across Queensland's gas basins. Government policy has increasingly emphasised energy security, providing a supportive regulatory backdrop for companies like Omega that are working to bring new supply online.
Globally, the oil and gas sector continues to benefit from robust demand fundamentals. The transition to renewable energy, while accelerating, has not reduced near-term reliance on natural gas, which is widely viewed as a critical transition fuel.
The Queensland gas sector has received renewed political attention, with state and federal governments acknowledging the importance of domestic gas supply for industrial competitiveness and energy affordability. Policy frameworks that support responsible exploration and development create a more favourable operating environment for companies like Omega.
Technological advances in unconventional gas extraction continue to improve the economics of previously marginal basins. Techniques refined in North American shale plays are being adapted for Australian conditions, potentially unlocking resources that were previously uneconomic. This technology transfer benefits explorers operating in basins compared to US unconventional plays.
Financial Performance
As a pre-revenue exploration company, Omega's financial profile is characterised by investment in exploration activities rather than commercial production. The company reported net cash used in operations of AUD 2.36 million over the trailing twelve months, with capital expenditures of AUD 21.80 million reflecting its active drilling and exploration program.
Free cash flow stands at negative AUD 24.16 million, which is typical for companies at this stage of development. The market capitalisation of approximately AUD 229 million reflects investor willingness to price in future exploration success.
The joint venture structure, with Beach Energy as a partner, provides financial support and reduces Omega's capital burden. This partnership model is particularly valuable for smaller explorers, as it allows them to advance programs that might otherwise require dilutive capital raises.
The joint venture economics are worth examining closely. With Omega holding 45% of the venture, the company's share of any discovery would be proportionally reduced, but so is its capital commitment. This risk-sharing model is common in frontier exploration and allows smaller companies to participate in high-cost drilling programmes without bearing the full financial burden.
Investment Risks
Exploration-stage companies inherently carry significant risk. There is no guarantee that drilling will encounter commercially viable hydrocarbon resources, and unsuccessful results could materially impact the share price.
Regulatory and environmental risks are also relevant. Changes to government policy on gas exploration, environmental approvals, or community opposition could delay or prevent project advancement.
Investors should also consider the risk of stranded assets. The global energy transition, while supportive of gas in the near term, introduces long-term uncertainty about the demand outlook for fossil fuels. Funding constraints for capital-intensive, long-cycle exploration projects remain an ongoing consideration.
Currency risk is an additional factor. As an Australian company exploring for hydrocarbons that will ultimately be priced in global markets, fluctuations in the AUD/USD exchange rate can impact the realised value of any future production. Hedging strategies can mitigate but not eliminate this exposure.
Future Growth Drivers
The most immediate growth driver is the upcoming drilling program. A four-well drilling campaign is planned across 2026 and 2027, with the initial results expected to be the most market-moving. Successful results could trigger a fundamental revaluation of the company.
Resource-to-reserve conversion represents another significant value catalyst. If exploration success is followed by positive feasibility studies, the pathway to commercial production could unlock substantial value for shareholders.
The anticipated East Coast gas supply shortfalls provide a favourable market backdrop. Companies that can demonstrate commercially viable gas resources in accessible locations are likely to attract premium interest from both strategic partners and the market.
Long-Term Investment Perspective
Omega Oil & Gas represents a classic exploration-stage opportunity with asymmetric risk-reward potential. A successful drilling campaign could establish the company as a significant player in Australia's gas supply chain, while unsuccessful results would likely result in material share price declines.
For investors with appropriate risk tolerance and a constructive view on Australian gas demand, OMA offers exposure to a well-partnered exploration story in a basin with genuine potential. The Beach Energy joint venture reduces execution risk and provides operational expertise.
Position sizing is critical for investments of this nature. The binary outcome potential of upcoming drilling results means investors should ensure OMA represents an appropriately sized allocation within a diversified portfolio.
For portfolio construction purposes, exploration-stage gas companies like OMA can serve as high-beta satellite positions around core energy holdings. The potential for step-change value creation from successful drilling provides portfolio optionality that is difficult to achieve through larger, more established energy companies.
Conclusion
Omega Oil & Gas stands at a pivotal moment in its development journey. The combination of a credible joint venture partnership with Beach Energy, an approaching high-impact drilling program, and a favourable macro backdrop for Australian gas makes OMA one of the more closely watched exploration stories on the ASX.
The stock's trajectory over the coming months will be largely determined by drilling outcomes. Positive results could unlock a fundamental revaluation, while unsuccessful exploration would test investor patience. For those with appropriate risk appetite and conviction in the Taroom Trough thesis, OMA presents a compelling speculative opportunity.
This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own research and consult a qualified financial adviser before making investment decisions.


 Nov 12, 2026





 Please wait processing your request...