
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
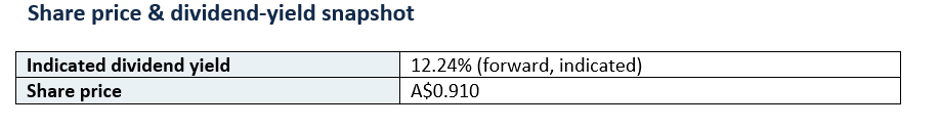
Latitude Group Holdings (ASX:LFS), a consumer finance and sales-finance business operating across Australia and New Zealand, screens with a high indicated dividend yield around 12%. The company returned to profitability in the past year and reported record loan growth in the first half of 2025, but market data indicates its dividend payout ratio is very high, near 99%, and not well covered by free cash flow. For income investors, the central question is whether this dividend is sustainable given the stretched payout and the company's recent earnings history.
A high yield from a recovering lender can reflect genuine improvement or a payout that has outpaced a still-fragile earnings base. The sustainable answer depends on Latitude's profitability trend, funding costs, credit quality and capital position. With a payout ratio near 99%, coverage is a clear focus.
Company overview: Consumer and sales finance
Latitude Group engages in sales finance and consumer lending across Australia and New Zealand, operating through pay and money segments that provide personal loans, motor loans, credit cards and instalment products. Its revenue is driven by lending volumes, net interest margins, funding costs and credit performance. As a consumer lender, it is exposed to interest-rate conditions, the cost and availability of funding, household credit demand, and arrears and credit losses, all of which influence profitability and dividend capacity.
For dividends, the relevant drivers are the trend in profitability, funding costs, credit quality and the capital position. Consumer finance earnings can be cyclical and sensitive to the economic environment, so the durability of the dividend depends on sustaining profitable lending through varying conditions.
Dividend history: A high payout against recovering earnings
Latitude pays dividends, and the company returned to profitability in the past year after a period of declining earnings, with reports of record loan growth and improved profitability in the first half of 2025. However, market data indicates that dividend payments have decreased over a longer multi-year horizon and that the current payout ratio is around 99%, meaning the dividend consumes almost all of earnings, with the company reported as having no free cash flow on the relevant measure. This high payout against a recovering earnings base is the defining feature of Latitude's dividend profile.
For income investors, the key consideration is that a payout ratio near 99% leaves virtually no buffer. While the return to profitability and loan growth are encouraging, a dividend that absorbs essentially all earnings is vulnerable to any setback in profit, funding costs or credit performance. The longer-term decline in dividends also signals that the payout has not been stable over time.
Dividend sustainability: Coverage is the key constraint
Assessing Latitude's dividend sustainability centres on the high payout ratio. With the dividend reported at around 99% of earnings and limited free cash flow, the payout appears only thinly covered, leaving little room for reinvestment, buffer or error. The recent return to profitability and record loan growth are positive, but they need to translate into durable, growing earnings to comfortably support the dividend. A consumer lender's earnings can be sensitive to credit losses and funding costs, which adds to the uncertainty.
The dividend may be more sustainable if Latitude sustains its return to profitability, grows earnings, manages funding costs and keeps credit losses contained, thereby reducing the payout ratio over time. The dividend may be vulnerable if earnings stall, funding costs rise, credit losses increase, or the economic environment weakens household credit quality. The stretched payout ratio means the dividend has limited resilience to adverse developments.
Payout ratio and earnings coverage
A payout ratio near 99% is among the highest in this high-yield cohort and indicates that the dividend is barely covered by earnings, with no meaningful free cash flow buffer. This is a clear caution. Income investors should watch closely for any reduction in the payout ratio as earnings recover, which would signal improving coverage, or any increase, which would heighten the risk to the dividend. Coverage, rather than the headline yield, is the decisive consideration here.
Balance sheet and funding position
As a consumer lender, Latitude relies on wholesale funding and securitisation, so its funding structure, capital position and access to funding markets are central to both profitability and dividend capacity. Funding costs directly affect net interest margins, and the capital position underpins the ability to absorb credit losses. Income investors should examine the company's capital adequacy, funding costs and credit-loss provisioning, as these determine the resilience of earnings and, in turn, the dividend. A stretched payout leaves less internal capital to strengthen the balance sheet.
Sector context: Consumer finance and the credit cycle
Consumer finance is closely tied to the credit cycle, interest rates, household financial health and funding conditions. Lending volumes and margins can be pressured when funding costs rise or competition intensifies, and credit losses tend to increase when unemployment rises or households come under financial stress. Dividend reliability across the sector depends on stable funding, disciplined credit standards and the ability to maintain margins. A high payout ratio reduces the cushion available to navigate a downturn.
Latest news and company updates
The most relevant recent updates for income investors are Latitude's return to profitability and reports of record loan growth and improved profitability in the first half of 2025, set against a high payout ratio and limited free cash flow. Income investors should follow full-year results, the trend in earnings and the payout ratio, funding costs and credit performance in subsequent announcements, as these will determine whether the dividend can be sustained or improved.
Risks to future dividends
Key risks to Latitude's dividend include a very high payout ratio near 99% that leaves little buffer, the possibility that the earnings recovery stalls, rising funding costs, increasing credit losses, a weaker consumer credit environment, and the longer-term decline in dividends evident in the company's history. Any setback in profitability or cash flow could pressure a payout that already absorbs almost all earnings. The stretched coverage is the central risk.
What could support future dividends
Future dividends could be supported by a durable return to profitability, continued loan and earnings growth, contained funding costs, low credit losses, a strengthened capital position, and a reduction in the payout ratio over time. If Latitude grows earnings faster than the dividend, coverage would improve and the payout would become more secure. The record loan growth and return to profit are constructive starting points, provided they prove durable.
Investor watch points
Income investors may wish to watch Latitude's earnings trend and whether profitability is sustained; the payout ratio and free cash flow; net interest margins and funding costs; arrears and credit losses; the capital position; loan growth; and each dividend declaration and its franking. A falling payout ratio would be the clearest sign of an improving dividend outlook.
Outlook: Sustainability hinges on durable earnings recovery
The outlook for Latitude's dividend depends on whether its return to profitability proves durable and whether earnings can grow enough to reduce the stretched payout ratio. On current evidence, with a payout near 99% and limited free cash flow, the dividend appears only thinly covered and exposed to any setback. The sustainability of future payments will depend on earnings, funding costs, credit quality and capital. Future dividends will depend on company performance, cash flow and board decisions.
Conclusion: A recovering lender with a thinly covered dividend
On balance, Latitude Group offers a high yield against a backdrop of improving profitability and record loan growth, but its dividend is only thinly covered, with a payout ratio reported near 99% and limited free cash flow. The dividend cannot be confidently assessed as comfortably sustainable on current information, and that caution is the key conclusion for income investors. A more secure payout would require a durable earnings recovery that reduces the payout ratio over time. Income investors should focus on the payout ratio, earnings durability, funding costs and credit quality, and remember that all future dividends remain subject to board approval, company performance, cash flow and market conditions.


 Nov 12, 2026





 Please wait processing your request...