
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
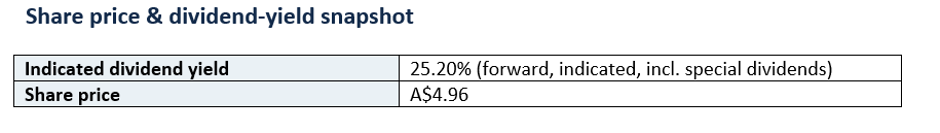
Helia Group (ASX:HLI), Australia's listed lenders mortgage insurance specialist, stands out among high-yield names because, unlike many stocks at the top of dividend screens, it is solidly profitable. With trailing diluted earnings per share around A$0.89 and a price-to-earnings ratio near 5.56, Helia is not a loss-making business propping up a payout from capital. Yet its indicated yield in the low-to-mid 30s is still extraordinary and demands careful scrutiny, because much of it is being driven by special dividends tied to a specific and time-limited situation.
The central question for income investors is whether Helia's distributions are sustainable, and what investors can realistically expect in future years. The answer requires separating the company's recurring, ordinary dividend from the large special dividends it has been paying as it returns surplus capital following the loss of major customer contracts. These are two very different income streams with very different durability.
Company overview: The economics of lenders mortgage insurance
Helia Group provides lenders mortgage insurance (LMI) in Australia. LMI protects a lender if a borrower defaults on a home loan and the proceeds from selling the secured property fall short of the outstanding debt. Lenders typically require LMI when a borrower has a smaller deposit, and the premium is usually paid by the borrower. Helia's revenue is therefore tied to the volume of high loan-to-value-ratio mortgage lending, the credit quality of that lending, and the relationships it holds with major banks and lenders.
A defining feature of the LMI model is its sensitivity to a small number of large lender contracts. When a major bank chooses Helia as its LMI provider, that single relationship can represent a substantial share of the company's gross written premium. The flip side is concentration risk: losing a major contract removes a large slice of new business at once, which is exactly the dynamic now shaping Helia's earnings and dividend trajectory.
Dividend history: Ordinary dividends plus sizeable specials
Helia has a track record of paying fully or partly franked ordinary dividends, supported by the profitability of its insurance book, and supplementing them with special dividends and buybacks when it holds surplus capital. In its recent results the company declared an ordinary dividend together with a large special dividend, with a final ordinary dividend reported around 16 cents per share alongside a special dividend reported around 67 cents per share, and an interim period featuring an ordinary dividend near 16 cents plus a special near 27 cents. Franking has been a feature of the ordinary component, enhancing the after-tax value for many Australian investors.
This pattern is the crux of the Helia dividend story. The ordinary dividend reflects recurring profitability, while the special dividends reflect a deliberate return of excess capital. The very high screened yield is heavily inflated by those specials, which are explicitly extraordinary and should not be assumed to continue indefinitely at the same scale.
Dividend sustainability: Why the specials are the key variable
Helia's ordinary dividend appears reasonably supported by its earnings, given a healthy trailing profit and a low payout ratio relative to earnings on the ordinary component. The sustainability question really concerns the special dividends. Those are being funded by surplus capital that has been freed up as Helia writes less new business following the loss of major contracts. When an insurer's book runs off and less new business is written, it needs less regulatory capital to support that book, releasing capital that can be returned to shareholders.
The important implication is that the special dividends are, by their nature, a finite capital-return story rather than a permanent income stream. They may persist for a period while excess capital is distributed, but as the in-force book matures and the capital release runs its course, the scope for further large specials is likely to diminish. The dividend may therefore look far more sustainable on its ordinary component than on the headline figure that includes the specials.
Payout ratio and earnings coverage
On the ordinary dividend, earnings coverage looks comfortable: with trailing diluted earnings per share around A$0.89 and an ordinary dividend well below that level, the recurring payout is covered by recurring profit. Once special dividends are included, however, the total distribution can exceed current-year earnings, because specials draw on accumulated surplus capital rather than annual profit. Income investors should distinguish clearly between the well-covered ordinary dividend and the capital-funded specials when assessing coverage.
Balance sheet and capital position
Capital strength is central to an LMI insurer, which must hold regulatory capital against the risk in its book. Helia's recent special dividends reflect a position of surplus capital, which is a sign of balance-sheet strength rather than weakness. As the company writes less new business, the capital required to support its shrinking new-business pipeline falls, releasing capital for return to shareholders. The key forward consideration is how much surplus remains to be distributed and over what period, since this determines the durability of the special-dividend stream.
Sector context: Housing, credit quality and contract concentration
The LMI sector is closely tied to the Australian housing market, the volume of high loan-to-value mortgage lending, and borrower credit quality. Rising unemployment or falling house prices could increase claims, while a strong, well-employed borrower base supports low claims and healthy underwriting profits. The sector's defining structural feature is contract concentration: a handful of major lender relationships drive the bulk of premium. The recent decisions by major customers not to renew with Helia illustrate how quickly the new-business outlook can change, even as the existing in-force book continues to generate earnings for years.
Latest news and company updates
The most consequential recent developments for Helia's dividend outlook are the confirmations that major customers would not renew their LMI arrangements: a major bank customer representing a very large share of gross written premium chose not to renew beyond the end of 2025, and a further significant customer also moved to an alternative provider. These losses materially reduce future new business, but they simultaneously free up capital, which is being returned through the special dividends that inflate the current yield. This combination — lower future growth but elevated near-term capital returns — defines the present investment situation.
Risks to future dividends
The principal risk to Helia's total dividend is that the special-dividend component is finite and will likely diminish once surplus capital has been returned. Beyond that, risks include a smaller in-force book over time as new business falls, a deterioration in the housing market or borrower credit quality that lifts claims, regulatory capital changes, and the broader challenge of replacing the lost contract volumes. The ordinary dividend is more resilient, but even it depends on the ongoing profitability of a book that is no longer being replenished at previous rates.
What could support future dividends
Supportive factors include the continued profitability of the existing in-force LMI book, which generates earnings for years after policies are written; a benign claims environment underpinned by employment and stable house prices; the franking attached to ordinary dividends, which enhances after-tax returns for eligible investors; and the remaining surplus capital still available for return. New lender relationships or product initiatives could also help offset lost volumes over time, though the central near-term support is the orderly return of surplus capital.
Investor watch points
Income investors may wish to watch the split between ordinary and special dividends in each results announcement; the level of surplus and regulatory capital and how much remains to be returned; gross written premium and new-business volumes following the contract losses; claims experience and the housing and employment backdrop; franking levels; and any management commentary on the expected duration of the special-dividend programme and the long-run shape of the ordinary dividend.
Outlook: Strong near-term returns, a thinner long-term stream
The realistic outlook is that Helia can likely sustain an ordinary dividend supported by the profitability of its in-force book, while the very large total distributions of recent periods are unlikely to persist indefinitely because they rely on returning finite surplus capital. As new business falls and capital is distributed, the headline yield is likely to normalise towards a level reflecting the ordinary dividend. Future payments will depend on earnings, claims experience, capital levels and board decisions.
Conclusion: A high yield with a clear distinction beneath it
Helia Group offers income investors a genuinely profitable business with a well-covered ordinary dividend and, currently, very large special dividends funded by surplus capital released as it writes less new business. The headline yield is therefore sustainable in part and temporary in part: the ordinary dividend appears reasonably supported by earnings, while the specials are a finite capital-return story tied to the loss of major contracts. The dividend may be more durable than the loss of customers first suggests, because the in-force book keeps earning, but the extraordinary total payout should not be assumed to continue at the same scale. Income investors should focus on the ordinary dividend's coverage and the remaining surplus capital, and remember that all future payments remain subject to board approval, earnings, capital and market conditions.


 Nov 12, 2026





 Please wait processing your request...