
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
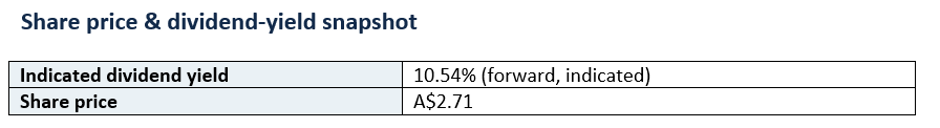
Lendlease Group (ASX:LLC), the well-known Australian property development, construction and investments group, screens with a high indicated distribution yield around 10% as it undertakes a major turnaround. The company has been simplifying its business, recycling capital and reducing costs, and has returned to operating profitability, but its statutory results have been affected by impairments and restructuring. For income investors, the central question is whether Lendlease can sustain distributions as it executes its transformation, and what investors can realistically expect.
A high yield on a company in the midst of a turnaround can be misleading if the distribution is being supported through a transitional period rather than by stable, recurring earnings. The sustainable answer depends on Lendlease's operating profit, cash generation, debt reduction and the success of its simplification strategy. Recent results show a return to operating profitability and a resumed distribution, but against a backdrop of significant change.
Company overview: An integrated property group
Lendlease operates an integrated property model spanning development, construction and investments, with a diversified portfolio across multiple markets. Its earnings are generated from developing and constructing major projects, and from managing and investing in property assets. The group has been undertaking a significant strategic simplification, reducing its international footprint, recycling capital, cutting costs and focusing on its core Australian operations. Its statutory results have been affected by impairments and restructuring charges associated with this transformation.
For distributions, the relevant drivers are operating profit, cash generation from capital recycling and asset sales, debt reduction, and the progress of the simplification strategy. A return to sustainable operating profitability and a stronger balance sheet would support distributions, while the transitional nature of the turnaround introduces uncertainty.
Distribution history: Resumed amid transformation
Lendlease has a long history of paying distributions to security holders, though payments have been affected by the challenges and restructuring of recent years. The company announced a distribution of around 17 cents per stapled security in 2025, with an ex-date in August 2025, reflecting a resumption of returns to security holders as it returned to operating profitability, with operating profit after tax reported around A$122 million for the relevant half and a focus on cost reduction, capital recycling and simplification. A reported payout ratio around 70% suggests the distribution is set with reference to operating earnings.
For income investors, the resumption of distributions alongside a return to operating profitability is encouraging, but the context of an ongoing turnaround, statutory losses from impairments, and a major strategic reset means the durability of the distribution depends on the success of the transformation. The distinction between operating profit, which supports the distribution, and statutory results, which include one-off charges, is important here.
Distribution sustainability: Tied to the turnaround
Assessing Lendlease's distribution sustainability requires separating operating performance from statutory results affected by impairments and restructuring. The distribution appears to be set with reference to operating profit, with a reported payout ratio around 70%, rather than statutory earnings. The sustainability of the distribution therefore depends on the group sustaining and growing operating profitability, generating cash from capital recycling, and reducing debt. The turnaround introduces execution risk, but a successful simplification would strengthen the basis for distributions.
The distribution may be more sustainable if Lendlease delivers on its simplification, cost-reduction and capital-recycling strategy, sustains operating profit, and reduces debt. The distribution may be vulnerable if the turnaround stalls, asset sales disappoint, the property and construction markets weaken, or further impairments and charges arise. The distribution is best viewed as dependent on the successful execution of the transformation.
Payout ratio and earnings coverage
With statutory earnings per security negative due to impairments, conventional coverage analysis against statutory profit is not meaningful. The reported payout ratio around 70% appears to be measured against operating earnings, which is the more relevant basis for a company in transition. Income investors should focus on operating profit, cash generation and the payout relative to operating earnings, rather than statutory results, and monitor whether operating profitability is sustained and grows as the turnaround progresses.
Balance sheet and debt position
The balance sheet and debt reduction are central to Lendlease's distribution outlook. The group's strategy emphasises capital recycling, asset sales and simplification, with the proceeds used to reduce debt and strengthen the balance sheet. A stronger balance sheet would support the sustainability of distributions by reducing financing pressure and freeing capital. Income investors should follow net debt, the progress of asset sales and capital recycling, and gearing, as these are key to both the turnaround and the distribution. Elevated debt or delayed asset sales would heighten risk to distributions.
Sector context: Property development and construction cycles
Property development and construction are cyclical, capital-intensive activities exposed to interest rates, property valuations, construction costs, project execution and demand for new developments. Earnings can be lumpy, depending on project timing and completions. The investments segment provides more recurring, rent-based income. Distribution reliability for an integrated property group depends on balancing the lumpier development and construction earnings with steadier investment income, and on prudent balance-sheet management. Lendlease's simplification aims to create a more resilient, focused model.
Latest news and company updates
The most relevant recent updates for income investors are Lendlease's return to operating profitability, with operating profit after tax around A$122 million for the relevant half, its progress on cost reduction, capital recycling and simplification, and the resumption of a distribution of around 17 cents per stapled security in 2025. These developments point to a turnaround taking effect. Income investors should follow operating profit, debt reduction, asset sales and any further restructuring charges in subsequent results.
Risks to future distributions
Key risks to Lendlease's distribution include execution risk in the turnaround, weaker property and construction markets, delays or disappointing pricing in asset sales and capital recycling, further impairments or restructuring charges, elevated debt, and the cyclicality and lumpiness of development and construction earnings. While the resumption of distributions is positive, the transformation introduces uncertainty, and a stalling of the turnaround could pressure distributions.
What could support future distributions
Future distributions could be supported by the successful execution of the simplification and cost-reduction strategy, sustained and growing operating profitability, strong cash generation from capital recycling and asset sales, debt reduction, and a recovery in property and construction markets. If Lendlease delivers on its turnaround and strengthens its balance sheet, the distribution would rest on a firmer footing. The return to operating profit is a constructive early signal.
Investor watch points
Income investors may wish to watch Lendlease's operating profit and the payout ratio against operating earnings; progress on capital recycling and asset sales; net debt and gearing; any further impairments or restructuring charges; the performance of the development, construction and investments segments; and each distribution declaration. The execution of the turnaround and debt reduction are the key signals for the distribution outlook.
Outlook: Distribution depends on turnaround execution
The outlook for Lendlease's distribution is cautiously constructive, given the return to operating profitability and the resumption of distributions, but it is tied to the successful execution of a major turnaround, including capital recycling, cost reduction and debt reduction. The sustainability of future distributions will depend on operating profit, cash generation, the balance sheet and property-market conditions. Future distributions will depend on company performance, cash flow, the turnaround and board decisions.
Conclusion: A resumed distribution tied to a major transformation
On balance, Lendlease has resumed distributions alongside a return to operating profitability, but its high screened yield and the durability of its distribution must be understood in the context of a significant ongoing turnaround. The distribution appears to be set against operating earnings and is supported by the early progress of the simplification strategy, though statutory results have been affected by impairments, and execution risk remains. Income investors should focus on operating profit, debt reduction, capital recycling and the progress of the transformation, and remember that all future distributions remain subject to board decisions, company performance, cash flow, property valuations and market conditions.


 Nov 12, 2026





 Please wait processing your request...