
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Crypto scams have become a serious concern for Australian SMSF trustees. ASIC, the ATO and the National Anti-Scam Centre have all warned that fraudsters are targeting SMSFs with sophisticated fake platforms, romance scams, fake advisory firms and bogus crypto Investment opportunities.
This article outlines the red flags trustees should watch for and the steps to take if a scam is suspected.
Common Scam Patterns
- Fake trading platforms that show false profits to encourage further deposits.
- Impersonation of legitimate Brokers, exchanges or government bodies.
- Social Media and messaging app groups promising stock or crypto 'tips'.
- Cold calls or unsolicited emails offering exclusive opportunities.
- Romance scams that evolve into investment requests.
- Recovery scams targeting victims of previous Fraud.
Red Flags to Spot
- Guaranteed or unrealistic returns, particularly high and 'consistent' performance.
- Pressure to act quickly or 'before the opportunity closes'.
- Requests for additional fees, taxes or 'verification' payments to release funds.
- Platforms not listed on AUSTRAC's public register.
- Reluctance to provide written terms or regulatory disclosures.
- Encouragement to roll over an APRA-regulated super into an SMSF for crypto investing.
Pattern: The Fake Trading Platform
A common scam involves a polished website with login, trading dashboards and apparent profits. Initial small withdrawals work, building trust, but larger withdrawals are blocked behind manufactured fees or 'compliance verification' demands. The platform is fake, the trades are not real, and the money is gone.
Pattern: WhatsApp and Telegram Stock Tip Groups
ASIC has warned that scammers invite victims into messaging app groups disguised as legitimate stock or crypto tip communities. Group members may include other scammers posing as successful investors. Eventually members are directed to fake platforms or asked to send crypto.
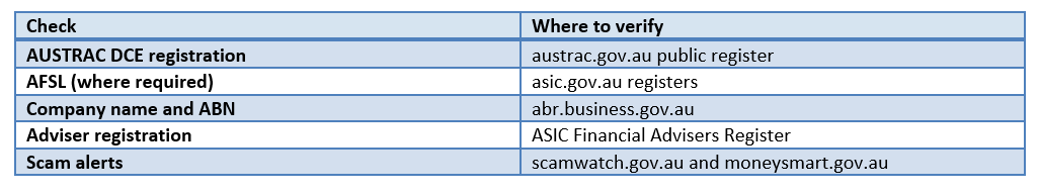
Verifying a Platform
If You Suspect a Scam
Stop all payments immediately. Contact your bank to halt transfers. Report the scam to Scamwatch via the National Anti-Scam Centre, the ATO if super has been targeted, and ASIC where relevant. Notify your SMSF Accountant and approved SMSF auditor.
Protecting the SMSF
- Adopt a 'verify before transferring' rule for every new platform.
- Use multi-Factor authentication on all crypto and bank accounts.
- Avoid sharing balance or holdings information in public forums.
- Treat unsolicited investment offers with strong scepticism.
- Educate co-trustees and family members on common scam patterns.
Recovery Realities
Recovering funds sent to scammers is difficult, especially for crypto sent to offshore wallets. Be wary of 'recovery agents' who promise to retrieve lost funds for an upfront fee — many are themselves scammers.
Why This Matters for Australian SMSF Trustees and Retirement Savers
Self-managed super funds collectively hold more than a trillion dollars of Australians' retirement savings. Decisions taken by individual trustees ripple through their members' financial futures. Cryptocurrency is unlike any other asset super funds have historically held: it trades 24/7, settles on global infrastructure, is highly volatile and is governed by rules that are still evolving. The cost of getting these decisions wrong is paid not just in compliance penalties but in lost retirement security.
For the average Australian Trustee, the practical question is not whether crypto is interesting in the abstract — it is whether the fund's compliance posture, members' time horizons and risk tolerances support the choice being considered. Even where the answer is yes, the size and structure of the allocation matter. Most SMSF specialists encourage trustees to start small, build experience, and scale only when records, custody and governance are demonstrably robust.
Members approaching or in retirement face additional pressure. Sequence-of-returns risk — the danger that poor returns early in retirement permanently damage the fund's ability to support drawdowns — is amplified by volatile Assets. Pension-phase funds carrying meaningful crypto exposure can find themselves selling at the worst possible moment to meet minimum drawdown obligations. These risks do not disappear because cryptocurrency has performed well over particular historical windows.
Illustrative Scenario
Consider a hypothetical four-member SMSF with $1.8 million in assets, comprising listed Australian shares, international Equity ETFs, cash and a small commercial property. Two of the members are in accumulation phase in their early 40s; two are in pension phase in their late 60s. The trustees decide they want to introduce a modest allocation to digital assets.
Working with their SMSF specialist accountant and lawyer, they update the trust deed to expressly authorise cryptocurrency, refresh the investment strategy to include a 0% to 4% crypto allocation range, and document the rationale, risk considerations and review cadence. They open an AUSTRAC-registered exchange account in the SMSF's full legal name, link it to the fund's dedicated bank account, and acquire a single, dedicated hardware wallet to hold long-term balances. They start with a small purchase of Bitcoin, document every transaction and capture a 30 June valuation in their first year of holding.
The trustees brief their approved SMSF auditor in advance, share the wallet ownership evidence, and provide the exchange statements at audit time. The fund does not stake or use DeFi. The trustees revisit the strategy a year later and decide whether to expand, hold or wind back the allocation. The example is illustrative only and does not reflect the situation of any specific fund.
Key Takeaways
- Scams targeting SMSFs are growing in sophistication.
- Red flags include guaranteed returns, pressure tactics and unregistered platforms.
- Always verify platforms with AUSTRAC, ASIC and ABR before investing.
- Report suspected scams to Scamwatch, the ATO and your bank.
- Be sceptical of recovery services that ask for upfront fees.


 Nov 03, 2026





 Please wait processing your request...