
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Cryptocurrency in an SMSF is not just about potential returns. It comes with a complex risk profile that touches markets, technology, behaviour, regulation and tax. ASIC has explicitly warned that SMSFs investing in crypto can suffer significant losses, and the ATO has reported ongoing Fraud and theft targeting funds.
This article maps the main SMSF crypto risks and outlines mitigation ideas for Australian trustees.
Market Risk
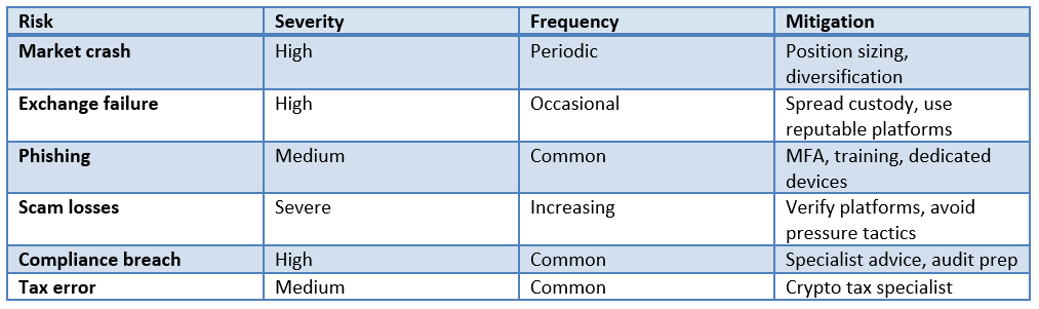
Crypto prices can swing sharply. Bitcoin and Ethereum have both experienced multiple drawdowns of more than 50% from previous peaks. Smaller Altcoins can fall further or even to zero. Trustees should size positions conservatively and consider the SMSF's Liquidity needs.
Cyber Security Risk
Phishing, malware, SIM-swap attacks and social engineering all target crypto holders. Trustees should use dedicated devices for crypto activity, hardware-based multi-Factor authentication, and avoid clicking on unsolicited links or downloading unverified apps.
Scam Risk
ASIC and the National Anti-Scam Centre have warned that fraudsters use fake trading platforms, WhatsApp and Telegram groups, and impersonation tactics to steal from SMSFs. Common red flags include guaranteed returns, pressure to act quickly, and platforms not on AUSTRAC's register.
Custody and Counterparty Risk
Exchanges can collapse, custodians can Fail, and self-custody can result in lost keys. Trustees should consider how much crypto sits with any single party and what would happen if that party failed.
Compliance Risk
- Ownership: Assets not held in the SMSF's name.
- Strategy: allocation not supported by the Investment strategy.
- Related parties: prohibited transactions with members or relatives.
- Audit: insufficient evidence or unclear records.
- Reporting: incorrect or missing data in the SMSF annual return.
Tax Risk
Misunderstood CGT events, missed staking income and untracked DeFi activity can all create unexpected tax bills. The ATO data-matching program covers crypto transactions and is expanding.
Operational Risk
Wallet migrations, exchange changes, software updates and Trustee changes all introduce operational risk. Documentation and procedures help maintain continuity.
Risk Comparison
Building a Risk Plan
Trustees should document the risks identified, planned mitigations, and review frequency. The plan can sit alongside the investment strategy and be revisited annually or after material events.
Practical Considerations for Australian Trustees
Beyond the headline rules, Australian self-managed super fund trustees should think about how the issues discussed above translate into day-to-day practice. Cryptocurrency is administered through digital systems that work around the clock, settle quickly and produce data that can be voluminous and highly granular. Trustees who treat SMSF crypto as a 'set and forget' asset often discover at audit time that the records they need were never captured.
Establish a documented procedures pack
A short procedures document — held alongside the trust deed and investment strategy — can describe how the fund opens accounts, executes trades, custodies assets, manages access, captures transactions, values holdings, prepares for audit and responds to incidents. Procedures need not be elaborate, but they should be tailored to the fund and reviewed when material changes occur.
Plan for trustee succession
Cryptocurrency access can be lost if a sole trustee becomes incapacitated, dies, or leaves the fund without handing over keys, wallets or passwords. Trustees should consider how access would be transferred in such events, including the role of enduring powers of attorney, executors and updated fund deeds. Multi-signature arrangements, custody providers and clear documentation can all reduce this risk.
Build a working relationship with specialists
SMSF crypto sits at the intersection of Superannuation law, tax law, anti-Money Laundering rules and digital asset technology. Few advisers cover all four areas deeply. Trustees often work with an SMSF specialist Accountant, a registered tax agent with crypto expertise, an approved SMSF auditor familiar with digital assets, and, where required, an SMSF lawyer. Coordinating these advisers helps ensure that decisions are properly considered before action is taken.
Illustrative Scenario
Consider a hypothetical four-member SMSF with $1.8 million in assets, comprising listed Australian shares, international Equity ETFs, cash and a small commercial property. Two of the members are in accumulation phase in their early 40s; two are in pension phase in their late 60s. The trustees decide they want to introduce a modest allocation to digital assets.
Working with their SMSF specialist accountant and lawyer, they update the trust deed to expressly authorise cryptocurrency, refresh the investment strategy to include a 0% to 4% crypto allocation range, and document the rationale, risk considerations and review cadence. They open an AUSTRAC-registered exchange account in the SMSF's full legal name, link it to the fund's dedicated bank account, and acquire a single, dedicated hardware wallet to hold long-term balances. They start with a small purchase of Bitcoin, document every transaction and capture a 30 June valuation in their first year of holding.
The trustees brief their approved SMSF auditor in advance, share the wallet ownership evidence, and provide the exchange statements at audit time. The fund does not stake or use DeFi. The trustees revisit the strategy a year later and decide whether to expand, hold or wind back the allocation. The example is illustrative only and does not reflect the situation of any specific fund.
Key Takeaways
- SMSF crypto risks span market, cyber, scam, custody, compliance, tax and operational categories.
- Operational and compliance failures often cause as much damage as market falls.
- Mitigation requires planning, documentation and ongoing review.
- Trustees should engage specialists for unfamiliar risks.
- Risk planning is integral to the investment strategy, not a separate exercise.


 Nov 03, 2026





 Please wait processing your request...