
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
SMSF Bitcoin investing has moved from a fringe topic to a mainstream question among Australian trustees. With ASX-listed Bitcoin Exchange-traded funds, regulated Australian exchanges and a growing professional ecosystem, the option is no longer obscure. The compliance and risk landscape, however, remains demanding.
Bitcoin can be held by an SMSF only when the fund's governing documents, Investment strategy, ownership arrangements and audit processes are in place. Trustees who treat BTC as a casual experiment risk breaches and losses. This article walks Australian trustees through the key issues before any Bitcoin is purchased.
Understand What Bitcoin Is — and Is Not
Bitcoin is a digital asset that operates on a global, public blockchain. It is not a share, a deposit or a regulated managed investment scheme. It carries no guarantee, no interest, no Dividend and no underlying Cash Flow. Its value is determined by what buyers will pay at any given time. Trustees should be clear that owning Bitcoin is fundamentally different from owning a productive Business or yielding asset.
Confirm the Fund Can Legally Hold Bitcoin
Before buying, trustees should confirm the trust deed permits Cryptocurrency and that the investment strategy supports a BTC allocation. The strategy should also address position sizing, Liquidity and how the trustees will manage Volatility.
Position Sizing and Volatility
Bitcoin's price has historically moved more than most traditional asset classes. Drawdowns of 50% or more from previous peaks have occurred multiple times. Trustees should consider how much of the fund's Assets they are willing to expose to such volatility and document the rationale. Conservative SMSFs commonly limit crypto exposure to a small percentage of assets.
Choosing a Platform
AUSTRAC registration
Trustees should use exchanges registered with AUSTRAC under the AML/CTF Act. From 31 March 2026, broader Virtual Asset Service Provider obligations begin under the AML/CTF Amendment Act 2024, including some platforms previously outside the registration regime.
AFSL changes
Legislation passed in 2026 progressively brings digital asset platforms within the AFSL regime under the Corporations Act. Trustees should monitor ASIC and Treasury updates and confirm that any chosen platform is on track to meet its obligations.
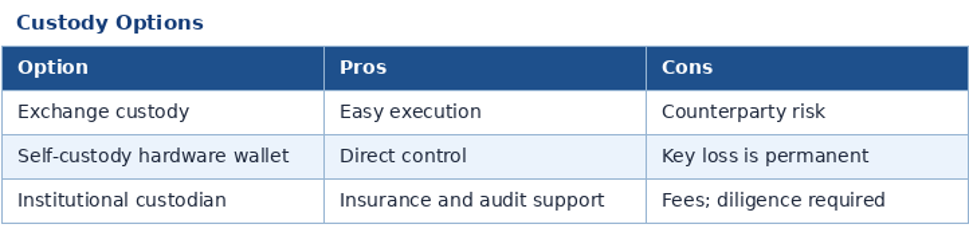
Custody Options
Tax and Reporting
Bitcoin disposals generally trigger CGT events in the SMSF. The fund must report capital gains and losses in its annual return, applying the one-third CGT discount where eligible. Detailed records of cost base, dates and fees are essential. Foreign exchange and gas-style transaction fees should also be captured.
Scams and Cyber Risks
- Verify any platform on AUSTRAC and ASIC's registers.
- Beware unsolicited investment offers via messaging apps or Social Media.
- Use strong, unique passwords and multi-Factor authentication.
- Be cautious about clicking links or downloading apps you did not seek out.
- Test Withdrawal processes with small amounts before large transfers.
Bitcoin ETFs as an Alternative
Australian Bitcoin exchange-traded funds, including VanEck's VBTC (0.45%) and DigitalX's BTXX (0.49%) on the ASX, plus Monochrome's IBTC (0.25%) on Cboe Australia, allow exposure through familiar brokerage platforms. ETFs simplify custody and audit but introduce Fund Manager fees and product structure considerations. Trustees should compare direct BTC and ETF exposure thoughtfully.
Audit Considerations
Approved SMSF auditors must verify that Bitcoin is held in the SMSF's name and properly valued. Trustees should provide account opening documents, transaction histories, wallet ownership evidence and 30 June valuations from reputable Australian exchanges.
Practical Considerations for Australian Trustees
Beyond the headline rules, Australian self-managed super fund trustees should think about how the issues discussed above translate into day-to-day practice. Cryptocurrency is administered through digital systems that work around the clock, settle quickly and produce data that can be voluminous and highly granular. Trustees who treat SMSF crypto as a 'set and forget' asset often discover at audit time that the records they need were never captured.
Establish a documented procedures pack
A short procedures document — held alongside the trust deed and investment strategy — can describe how the fund opens accounts, executes trades, custodies assets, manages access, captures transactions, values holdings, prepares for audit and responds to incidents. Procedures need not be elaborate, but they should be tailored to the fund and reviewed when material changes occur.
Plan for Trustee succession
Cryptocurrency access can be lost if a sole trustee becomes incapacitated, dies, or leaves the fund without handing over keys, wallets or passwords. Trustees should consider how access would be transferred in such events, including the role of enduring powers of attorney, executors and updated fund deeds.
Build a working relationship with specialists
SMSF crypto sits at the intersection of Superannuation law, tax law, anti-Money Laundering rules and digital asset technology. Few advisers cover all four areas deeply. Trustees often work with an SMSF specialist Accountant, a registered tax agent with crypto expertise, an approved SMSF auditor familiar with digital assets, and, where required, an SMSF lawyer.
Illustrative Scenario
Consider a hypothetical four-member SMSF with $1.8 million in assets, comprising listed Australian shares, international Equity ETFs, cash and a small commercial property. Two of the members are in accumulation phase in their early 40s; two are in pension phase in their late 60s. The trustees decide they want to introduce a modest allocation to digital assets.
Working with their SMSF specialist accountant and lawyer, they update the trust deed to expressly authorise cryptocurrency, refresh the investment strategy to include a 0% to 4% crypto allocation range, and document the rationale, risk considerations and review cadence. They open an AUSTRAC-registered exchange account in the SMSF's full legal name, link it to the fund's dedicated bank account, and acquire a single, dedicated hardware wallet to hold long-term balances. They start with a small purchase of Bitcoin, document every transaction and capture a 30 June valuation in their first year of holding.
The trustees brief their approved SMSF auditor in advance, share the wallet ownership evidence, and provide the exchange statements at audit time. The fund does not stake or use DeFi. The trustees revisit the strategy a year later and decide whether to expand, hold or wind back the allocation. The example is illustrative only and does not reflect the situation of any specific fund.
Key Takeaways
- Understand Bitcoin's character before committing fund money — it has no underlying cash flow.
- Get the deed, strategy and ownership right first.
- Use AUSTRAC-registered exchanges and monitor AFSL reforms.
- Decide between direct BTC and Bitcoin ETFs based on the fund's needs.
- Maintain meticulous tax and audit records.


 Nov 03, 2026





 Please wait processing your request...