
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Decentralised finance, or DeFi, refers to financial services delivered through blockchain-based smart contracts rather than traditional intermediaries. Lending, borrowing, Derivatives, automated market making and Yield strategies have grown into a significant ecosystem, mostly on Ethereum and similar networks.
Australian SMSF trustees sometimes ask whether DeFi can fit within a self-managed super fund. The honest answer is that DeFi is technically possible in some cases, but the compliance, tax and risk implications are significant.
What Is DeFi?
DeFi describes financial activities executed by smart contracts. Common categories include lending and borrowing, automated market making (Liquidity pools), staking derivatives, yield strategies and decentralised exchanges.
ATO DeFi Tax Guidance
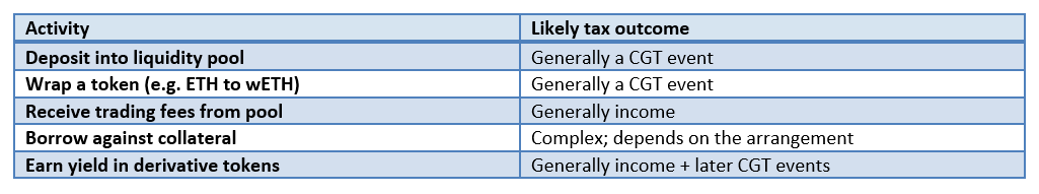
The ATO has stated that depositing crypto into a liquidity pool, wrapping a token, and similar activities involving a change of beneficial ownership are generally CGT events. Rewards distributed by DeFi protocols are typically assessable income at the time received. A single DeFi position can produce many taxable events.
Smart Contract Risk
DeFi relies on code. Bugs, exploits and oracle manipulation have caused significant losses across the industry. SMSF trustees should assume that any DeFi platform can Fail and size positions accordingly.
Custody and Ownership
Funds deposited into DeFi protocols are typically managed by smart contracts. Trustees should ensure they retain control of the wallet from which the funds are deposited and document the relationship for audit purposes.
Audit Complexity
DeFi audits are demanding. Auditors need to understand contract logic, transaction histories, reward distributions and changes in token composition. Detailed, contemporaneous records and specialist crypto tax software are typically required.
Common DeFi Activities and Tax Outcomes
Risk Management
- Limit any single DeFi position to a small percentage of fund Assets.
- Prefer audited, established protocols where possible.
- Monitor smart contract risk disclosures and exploit news.
- Plan exit procedures in advance for liquidity stress events.
- Document everything: deposits, withdrawals, rewards, fees and gas costs.
Compliance Cautions
DeFi activity can raise concerns under the in-house asset and related-party rules where related entities are involved, and may stretch the sole purpose test if benefits flow to related parties. Trustees should obtain advice before entering complex structures.
Practical Considerations for Australian Trustees
Beyond the headline rules, Australian self-managed super fund trustees should think about how the issues discussed above translate into day-to-day practice. Cryptocurrency is administered through digital systems that work around the clock, settle quickly and produce data that can be voluminous and highly granular. Trustees who treat SMSF crypto as a 'set and forget' asset often discover at audit time that the records they need were never captured.
Establish a documented procedures pack
A short procedures document — held alongside the trust deed and Investment strategy — can describe how the fund opens accounts, executes trades, custodies assets, manages access, captures transactions, values holdings, prepares for audit and responds to incidents. Procedures need not be elaborate, but they should be tailored to the fund and reviewed when material changes occur.
Plan for Trustee succession
Cryptocurrency access can be lost if a sole trustee becomes incapacitated, dies, or leaves the fund without handing over keys, wallets or passwords. Trustees should consider how access would be transferred in such events, including the role of enduring powers of attorney, executors and updated fund deeds. Multi-signature arrangements, custody providers and clear documentation can all reduce this risk.
Build a working relationship with specialists
SMSF crypto sits at the intersection of Superannuation law, tax law, anti-Money Laundering rules and digital asset technology. Few advisers cover all four areas deeply. Trustees often work with an SMSF specialist Accountant, a registered tax agent with crypto expertise, an approved SMSF auditor familiar with digital assets, and, where required, an SMSF lawyer. Coordinating these advisers helps ensure that decisions are properly considered before action is taken.
Illustrative Scenario
Consider a hypothetical four-member SMSF with $1.8 million in assets, comprising listed Australian shares, international Equity ETFs, cash and a small commercial property. Two of the members are in accumulation phase in their early 40s; two are in pension phase in their late 60s. The trustees decide they want to introduce a modest allocation to digital assets.
Working with their SMSF specialist accountant and lawyer, they update the trust deed to expressly authorise cryptocurrency, refresh the investment strategy to include a 0% to 4% crypto allocation range, and document the rationale, risk considerations and review cadence. They open an AUSTRAC-registered exchange account in the SMSF's full legal name, link it to the fund's dedicated bank account, and acquire a single, dedicated hardware wallet to hold long-term balances. They start with a small purchase of Bitcoin, document every transaction and capture a 30 June valuation in their first year of holding.
The trustees brief their approved SMSF auditor in advance, share the wallet ownership evidence, and provide the exchange statements at audit time. The fund does not stake or use DeFi. The trustees revisit the strategy a year later and decide whether to expand, hold or wind back the allocation. The example is illustrative only and does not reflect the situation of any specific fund.
Key Takeaways
- DeFi can be considered by some SMSFs but is high-risk and high-complexity.
- ATO guidance treats many DeFi steps as CGT events and rewards as income.
- Smart contract, oracle, custody and audit risks are material.
- Documentation and specialist advice are essential.
- Position sizing should reflect the elevated risks.


 Nov 03, 2026





 Please wait processing your request...