
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
- Bond Overview and Key Characteristics
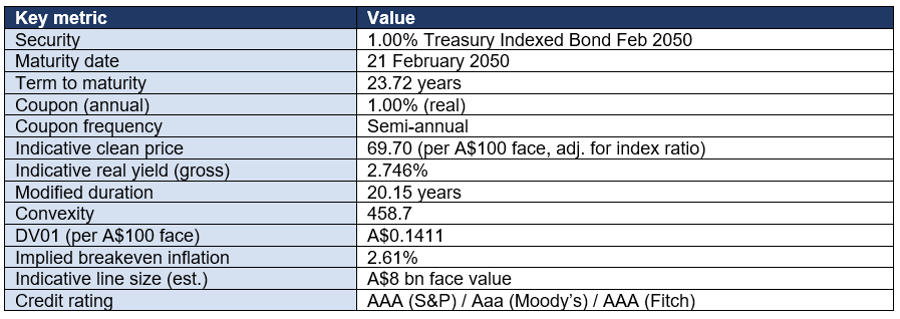
The 1.00% Treasury Indexed Bond Feb 2050 is a capital-indexed inflation-linked security issued by the Commonwealth of Australia through the Australian Office of Financial Management (AOFM). It carries a fixed annual coupon of 1.00% in real (pre-indexation) terms paid semi-annually and matures on 21 February 2050, giving a current term to maturity of approximately 23.7 years as at 11 June 2026. The line sits in the ultra long segment of the Australian Commonwealth Government Bond (ACGB) curve and is a direct, unconditional obligation of the sovereign, ranking pari passu with all other Australian Government Securities (AGS).
As a Treasury Indexed Bond (TIB), the security’s face value is adjusted for movements in the Consumer Price Index (CPI). Both the semi-annual coupon and the final principal repayment are calculated on the inflation-adjusted (indexed) capital value, so the instrument delivers a contractually protected real return rather than a fixed nominal cash flow. This is the defining structural difference from a conventional Treasury Bond and drives almost every aspect of its valuation, risk profile and portfolio role.
- Issuer Background – the Australian Government and AOFM
Australian Government Securities are issued by the AOFM on behalf of the Commonwealth of Australia. The AOFM is a specialist agency within the Treasury portfolio responsible for debt issuance, cash management and management of the Commonwealth’s debt portfolio. Issuance is conducted predominantly through competitive tenders, supplemented by syndicated transactions for new lines and very long maturities, and occasional buybacks of short-dated or off-the-run stock.
Australia retains one of a small group of sovereigns rated triple-A by all three major agencies. The credit standing reflects a credible medium-term fiscal framework, low-to-moderate general-government debt by advanced-economy standards, deep and independent institutions, a free-floating Australian dollar, and an independent central bank with a clear inflation-targeting mandate. Commonwealth gross debt remains comfortably serviceable, and the AGS market is supported by a diversified domestic and offshore investor base, including central banks and sovereign funds.
- Coupon Structure and Payment Schedule
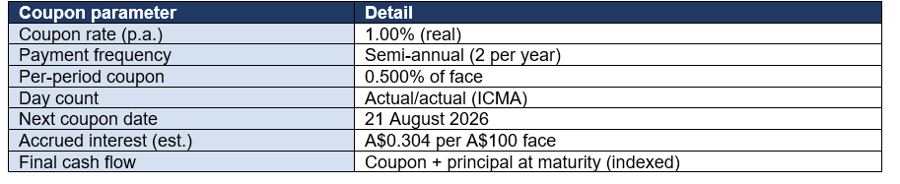
The bond pays a fixed coupon of 1.00% per annum in two equal semi-annual instalments of 0.500% of the indexed face value, on the 21st day of Feb and the corresponding month six months earlier. For this indexed bond, each payment equals the real coupon rate applied to the CPI-adjusted capital value (the nominal capital multiplied by the indexation factor for the period), so the actual cash received rises broadly in line with cumulative inflation since first issue. The next scheduled coupon falls on 21 August 2026, with approximately 48 coupon payments remaining to maturity.
- Maturity Profile and Duration Analysis
With a maturity of 21 February 2050, the bond has a Macaulay duration of approximately 20.43 years and a modified duration of about 20.15 years. Modified duration is the key first-order measure of price sensitivity: a 1 basis-point (bp) parallel rise in yield implies a price fall of roughly A$0.1411 per A$100 of face value (the DV01), or about 20.15% for a 100bp move before convexity. Convexity of approximately 459 adds a second-order, return-enhancing adjustment that becomes increasingly material for this longer-dated line.
Very high duration and convexity make this one of the most rate-sensitive instruments in the AGS complex; small yield moves translate into large price swings, rewarding conviction but demanding careful sizing.
- Historical Issuance Details
The Feb 2050 line was first established around 2019 and has since been progressively built out through the AOFM’s regular tender program and syndicated taps. Indicative face value outstanding is estimated at approximately A$8 billion (a clearly-labelled estimate; the precise current amount on issue and the line’s ISIN are published weekly on the AOFM register). Issuance into the line is now more episodic as it has either become seasoned/off-the-run or sits in the less frequently tapped part of the curve. AOFM issuance is calibrated to the Commonwealth’s financing task set out at each Budget and MYEFO update, with the program for 2025–26 emphasising smooth curve coverage and support for the 10-year futures basket and the ultra-long benchmark.
- Current Yield and Yield-Curve Positioning
As at 11 June 2026 the real yield is estimated at approximately 2.75%, derived from the constructed June 2026 ACGB real curve. For context, the RBA cash rate stands at 4.35% following the May 2026 increase, the 3-year benchmark trades near 4.42% and the 10-year near 4.90%, leaving the curve gently upward sloping with a positive 2s10s spread of roughly 1bp — among the steeper profiles in the developed world. This line sits in the ultra long segment and offers a real yield well above the RBA’s 2–3% inflation target band, an attractive entry point for locking in positive long-run real returns.
- Interest-Rate Sensitivity Analysis
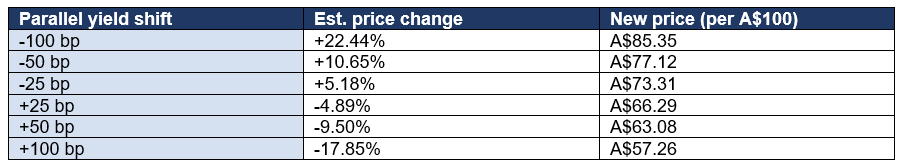
The table below stress-tests the indicative clean price for parallel shifts in the real yield, combining the modified-duration and convexity effects. With modified duration near 20.15 years, the line is highly rate-sensitive. Convexity of about 459 works in the holder’s favour, cushioning losses when yields rise and adding to gains when yields fall — an effect that is most valuable for this long-dated maturity.
- Inflation Considerations
Inflation linkage is the central feature of this security. The capital value is indexed to the CPI with the standard lag, so both coupons and the redemption amount rise with realised inflation, protecting the investor’s purchasing power. The implied breakeven inflation rate — the difference between the comparable nominal ACGB yield and this bond’s real yield — is approximately 2.61%. An investor earns a higher total return than the equivalent nominal bond if average CPI inflation over the life of the security exceeds this breakeven, and a lower return if it falls short.
With headline CPI running at 4.2% and trimmed-mean inflation at 3.4% (above the RBA’s 2-3% target band) as at April 2026, near-term indexation accruals are running well above the breakeven. The principal floor on most TIBs also protects against the tail risk of cumulative deflation. The key risk is the reverse: if inflation falls back into or below target faster than the market expects, realised returns could lag comparable nominal bonds.
- Credit Risk Assessment
Credit risk is minimal. The bond is a direct, unconditional and unsubordinated obligation of the Commonwealth of Australia, rated AAA by S&P (stable), Aaa by Moody’s (stable) and AAA by Fitch (stable). As the sovereign issuer in its own freely floating currency, the Commonwealth faces no meaningful default risk on AUD-denominated debt; the practical risks are macroeconomic and market-related (rates, inflation, liquidity) rather than credit-related. AGS therefore function as the domestic risk-free benchmark against which all other AUD fixed income is priced, and as a high-quality liquid asset for regulatory and collateral purposes.
- Liquidity and Secondary-Market Trading
Secondary-market liquidity for this line is good but somewhat thinner than the on-the-run benchmarks, with wider spreads in stressed markets. Trading is intermediated by AOFM-appointed primary dealers, cleared through Austraclear and settled T+2. Indexed bonds form a smaller, less liquid market than nominal AGS, so investors should expect wider spreads and size constraints, particularly in volatile conditions. Overall, liquidity is more than adequate for institutional position-taking, though execution costs rise with maturity and in risk-off episodes.
- Relative Value Versus Comparable Australian Government Bonds
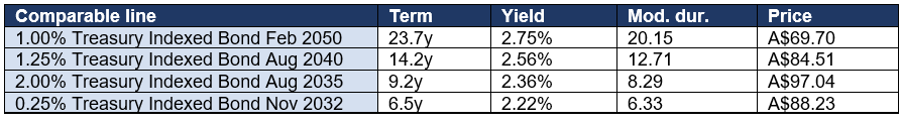
On a curve-relative basis, the 1.00% Treasury Indexed Bond Feb 2050 can be assessed against its nearest neighbours such as the 1.25% Treasury Indexed Bond Aug 2040 and 2.00% Treasury Indexed Bond Aug 2035. At an estimated 2.75% it sits broadly on the fitted real curve; richness or cheapness of a few basis points versus the interpolated curve would be the basis for a switch. Its inflation linkage provides explicit CPI protection that the nominal curve cannot replicate, while the steep slope of the curve rewards extending duration only where the investor is compensated for the additional term and volatility. Roll-down along the upward-sloping curve provides a modest positive carry-and-roll tailwind for medium-dated lines held over the coming year.
- Comparison With Australian State Government Bonds (Semis)
Semi-government bonds — issued by state treasury corporations such as NSW TCorp, Treasury Corporation of Victoria, Queensland Treasury Corporation and Western Australian Treasury Corporation — are the main higher-yielding, high-grade alternative to AGS. Semis typically carry AAA/AA+ ratings and trade at a spread over the ACGB curve of roughly 25–60bp depending on issuer and maturity, compensating for marginally weaker liquidity and slightly higher (but still very low) credit risk. Against this line’s ~2.75% yield, a comparable-maturity semi would offer a pick-up but with reduced repo eligibility depth, no Commonwealth guarantee and thinner secondary turnover. AGS remain the choice for the most liquidity-sensitive, collateral and benchmark-tracking mandates; semis suit investors able to trade modest liquidity for incremental spread.
- Portfolio Construction Considerations
Within a diversified portfolio this line is best used as long-dated liability matching for pension and insurance mandates and a high-octane expression of falling-yield views. Its DV01 of A$0.1411 per A$100 face makes duration budgeting straightforward, and its triple-A status means it adds duration without adding credit risk — valuable for barbell and laddered structures and for offsetting the equity beta of growth assets. Pairing nominal and indexed AGS allows investors to separate real-rate and inflation exposures explicitly. Negative correlation with risk assets during flight-to-quality episodes is a key reason institutions hold ACGB duration despite the steep curve.
- Investor Suitability
The bond is most suitable for long-dated liability matching and tactical duration accounts with high risk tolerance. Indexed bonds particularly suit investors with explicitly inflation-linked liabilities or a structural concern about purchasing-power erosion, such as retirees and inflation-aware endowments. It is appropriate for conservative and balanced risk profiles given its credit quality, though the price volatility of this maturity should be sized to the investor’s duration tolerance. Retail investors can access AGS via the ASX-quoted exchange-traded Treasury Bond (eTB) units or pooled bond funds.
- Key Advantages
- Triple-A sovereign credit quality – effectively risk-free in AUD terms.
- Explicit CPI protection of both coupons and principal.
- Highly liquid, repo-eligible and accepted as high-quality liquid collateral.
- Attractive real yield of ~2.75% versus recent history, with a steep curve rewarding selective duration.
- Diversification and negative correlation with risk assets in flight-to-quality episodes.
- Transparent pricing, deep dealer support and standard T+2 settlement via Austraclear.
- Key Risks
- Interest-rate risk – modified duration of ~20.15 years means price falls if yields rise.
- Real-rate risk – even with inflation protection, rising real yields lower the price.
- Reinvestment risk – coupons may be reinvested at lower rates if yields fall.
- Liquidity risk – spreads can widen in stressed markets, more so for longer/off-the-run lines.
- Opportunity cost – higher returns are available from credit and equity in benign conditions.
- Policy/fiscal risk – shifts in RBA policy, the issuance program or the fiscal outlook can move yields.
- Deflation/disinflation risk – returns lag nominal bonds if inflation undershoots the breakeven.
- Five-Year Outlook
Over a five-year horizon the dominant question is the path of the RBA cash rate from its current 4.35%. The May 2026 hike and still-elevated trimmed-mean inflation of 3.4% leave the Board balancing inflation persistence against slowing growth. The base case is that inflation gradually returns toward the 2-3% band, allowing the cash rate to ease modestly from 2027, which would support long-end valuations, though term premium and heavy duration supply may temper the rally at the very long end. Carry and roll-down on an upward-sloping curve add to expected return for this maturity. Total return over five years will be driven mainly by the realised rate path and reinvested coupons.
- Ten-Year Outlook
Over ten years, structural forces dominate cyclical ones. Australia’s favourable demographics relative to peers, contained public debt, credible institutions and an inflation-targeting central bank argue for yields settling around a neutral nominal range of roughly 3.75–4.75% once the current inflation episode is resolved, with real yields near 1.5–2.0%. For this longer maturity, a decade of holding captures multiple cycles; the steep starting curve, high carry and the diversification value of duration support a constructive total-return case, though supply from sustained deficits and global term-premium trends are the main swing factors. Sustained demand for inflation protection from liability-driven investors should keep structural support under the indexed market.
- Scenario Analysis (Bull, Base, Bear)
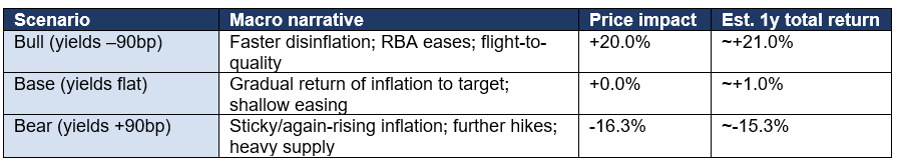
The following one-year scenarios combine the duration/convexity price response with the 1.00% real coupon income as a simplified total-return proxy (excluding reinvestment and, for the indexed bond, indexation uplift, which would add to the bull and base cases when inflation runs above breakeven).
- Conclusion and Investment Considerations
The 1.00% Treasury Indexed Bond Feb 2050 is an efficient duration and liability-matching instrument for investors who can tolerate its price volatility. It combines triple-A sovereign credit, genuine inflation protection, deep liquidity and a real yield of approximately 2.75% that is attractive relative to the past decade. The principal considerations are interest-rate risk (modified duration ~20.15 years), the still-elevated inflation backdrop, and the opportunity cost relative to credit and equity in benign markets. For inflation-aware and liability-driven investors the explicit CPI linkage is the decisive advantage, especially with current inflation running above the breakeven. On balance, the line warrants a place in diversified AUD fixed-income portfolios sized to each investor’s duration and inflation views as at 11 June 2026.


 Nov 12, 2026





 Please wait processing your request...