Duolingo Inc
Duolingo, Inc. (NASDAQ: DUOL) is a technology company. The Company is engaged in offering a mobile learning platform, as well as a digital English language proficiency assessment exam. It operates a freemium business model, namely, the app and the Website are accessible free of charge, although Duolingo also offers premium services for a subscription fee. Its solutions consist of the Duolingo App, Super Duolingo, Duolingo Max, Duolingo English Test: AI-Driven Language Assessment, Duolingo for Schools, and Duolingo ABC.
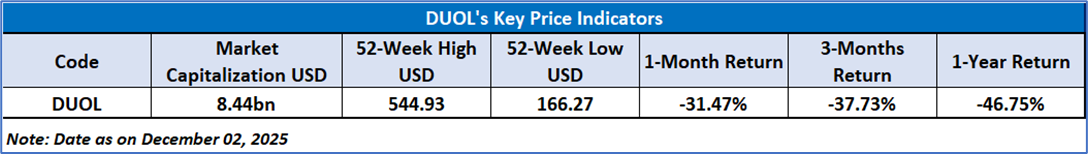
Key Business and Financial Updates:
- User Growth, Engagement Trends, and Platform Momentum: Duolingo reported strong user metrics in Q3 2025, with Daily Active Users increasing 36% year over year to 50.5 million and Monthly Active Users rising 20% to 135.3 million. Paid subscribers grew 34% to 11.5 million, resulting in a paid penetration rate of 9.0% of LTM MAUs. Management highlighted continued momentum in 2025, noting that DAUs and revenue for the first nine months rose more than 40% compared to the prior year, supported by product engagement improvements, new subject expansion such as chess, and brand visibility initiatives including partnerships and platform integrations. While Q3 user growth moderated relative to Q2 due to adjustments in social media strategy, increased marketing investments and enhanced content strategies contributed to a renewed improvement in impressions and user activity.
- Strategic Product Priorities and Long-Term Operating Philosophy: The Company reiterated its commitment to its core operating principle of “taking the long view,” emphasizing a balanced approach across monetization, user growth, and instructional quality. Management noted that improvements across these three dimensions influence financial performance on different timelines, with monetization initiatives driving immediate effects, user growth contributing over a longer horizon, and teaching enhancements influencing outcomes over the longest period. During Q3, Duolingo intentionally shifted investment priorities toward long-term initiatives, including increased focus on pedagogical improvements and user growth-oriented A/B testing, reflecting the Company’s view that advancements in AI have the potential to meaningfully expand the effectiveness and reach of its learning platform.
- Financial Performance, Profitability Trends, and Operational Metrics: Duolingo delivered another strong financial quarter, with Q3 2025 revenue growing 41% to USD 271.7 million and total bookings rising 33% to USD 281.9 million. Net income increased significantly to USD 292.2 million, primarily due to the release of valuation allowances related to deferred tax assets. Adjusted EBITDA reached a record USD 80.0 million, representing a 29.5% margin, driven by operating leverage and a continued shift toward higher-priced subscription tiers, including Max and family plans. Gross margin declined modestly by approximately 40 basis points to 72.5%, reflecting higher generative AI and hosting costs, though overall profitability continued to expand. The Company also emphasized strong ARPU performance, supported by the mix shift toward premium offerings.
- Forward Outlook and Product Pipeline for Q4 and FY 2025: Management expressed confidence in the outlook for Q4 and the full year, citing a robust product roadmap that includes player-versus-player features for chess, new flashcard exercises, and guided video call formats aimed at increasing adoption of Max. The Company also highlighted its Year in Review and New Year’s Promotion as major global engagement catalysts. For Q4 2025, Duolingo expects bookings of USD 329.5–335.5 million and revenue of USD 273–277 million, with Adjusted EBITDA projected at USD 75.4–78.8 million. Full-year 2025 guidance anticipates bookings of USD 1.151–1.157 billion, revenue of USD 1.0275–1.0315 billion, and Adjusted EBITDA of USD 296.9–300.2 million, with margins approaching 29%. These projections reflect confidence in sustained user expansion, continued subscription mix improvements, and disciplined execution across strategic initiatives.
Technical Observation (on the daily chart):
- Price Trend, Structure, and Moving Averages: DUOL has remained in a steady downtrend through 2025, falling from above USD 500 to the USD 166–185 area, with the price consistently below the 21-day and 50-day moving averages. Both MAs continue to slope downward, reflecting sustained bearish momentum and only a mild stabilization near recent lows.
- Momentum Indicators and RSI Behaviour: The RSI is near 40, indicating weak momentum without entering extreme oversold territory. It has trended lower since mid-year, showing persistent selling pressure, though recent readings suggest momentum is stabilizing rather than accelerating downward.
- Volume Trends and Market Participation: Volume has generally been moderate, with spikes during sharper sell-offs in late September and October. Recent volume levels are quieter, consistent with price consolidation, and show no clear signs yet of strong accumulation or trend reversal.
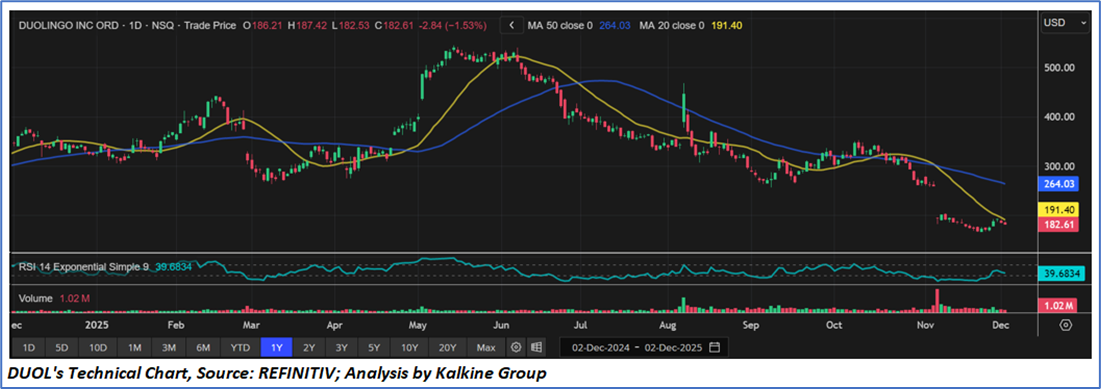
Duolingo, Inc. (NASDAQ: DUOL) is a technology company offering a freemium mobile learning platform and AI-driven language assessment solutions, and in Q3 2025 it reported strong operational momentum with DAUs rising 36% year over year to 50.5 million, MAUs increasing to 135.3 million, and paid subscribers expanding 34% to 11.5 million. Management emphasized long-term strategic priorities across monetization, user growth, and instructional quality, highlighting increased investment in teaching improvements and user-centric initiatives supported by advancements in AI. Financial performance remained robust, with revenue up 41% to USD 271.7 million, bookings up 33%, record Adjusted EBITDA of USD 80.0 million, and higher ARPU driven by mix shifts toward premium tiers, despite a modest decline in gross margin due to AI and hosting costs. The Company’s Q4 and FY2025 outlook reflects continued expansion, supported by new product features such as PvP chess, enhanced learning tools, and major seasonal engagement events. Technically, the stock continues to trend downward, trading well below its 21-day and 50-day moving averages, with an RSI near 34 and muted volume activity indicating ongoing bearish momentum with signs of stabilization near recent lows.
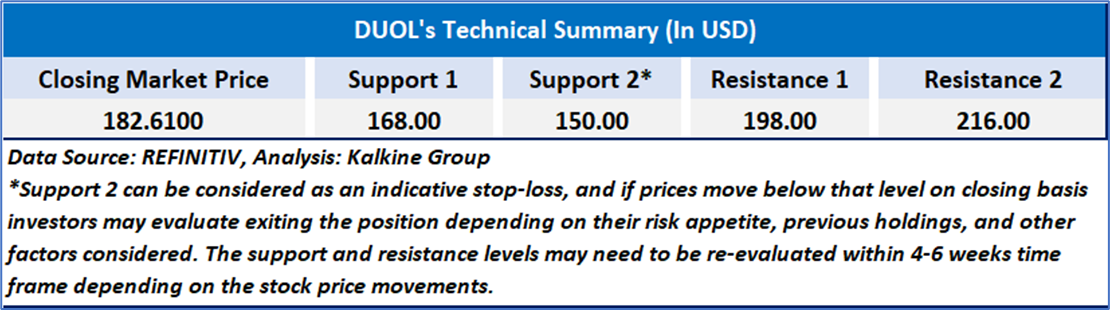
As per the above-mentioned price action, important resistance near USD 190.00-USD 200.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Duolingo, Inc. (NASDAQ: DUOL) at the closing price of USD 182.61, as of December 02, 2025.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is December 02, 2025. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU
 Please wait processing your request...