Apogee Therapeutics
Apogee Therapeutics (NASDAQ: APGE) is a clinical-stage biotechnology company focused on developing novel biologics for inflammatory and immunology conditions such as atopic dermatitis, asthma, COPD, and eosinophilic esophagitis. Its lead candidate, APG777, is primarily targeted for atopic dermatitis, while the broader pipeline includes multiple antibody-based therapies designed for enhanced efficacy and less frequent dosing. Key programs include APG990 (targeting OX40L), APG333 (targeting TSLP), APG808 (targeting IL-4Rα), and combination therapy APG279, reflecting a strategy centered on both monotherapies and combination approaches across validated immune pathways.

Key Growth Aspects
- Robust and Differentiated Clinical Pipeline; Apogee Therapeutics is advancing a diversified pipeline of biologics targeting large inflammatory and immunology markets, including atopic dermatitis, asthma, COPD, and eosinophilic esophagitis. The company’s lead asset, zumilokibart (APG777), has demonstrated strong clinical efficacy in Phase 2 trials, including significant improvements in EASI scores and other dermatological endpoints. The breadth of the pipeline, spanning both monotherapies and combination therapies, positions the company to address multiple high-value indications with a unified scientific approach.
- Strong Clinical Efficacy and Safety Signals: Clinical data from the APEX Phase 2 trial indicates that zumilokibart achieved superior efficacy compared to placebo, with meaningful improvements across key endpoints such as EASI-75, EASI-90, and itch reduction. Additionally, the therapy demonstrated a favorable safety profile with low discontinuation rates and minimal serious adverse events. These results highlight the potential for best-in-class positioning, particularly in a competitive biologics landscape where both efficacy and tolerability are critical differentiators.
- Innovative Antibody Engineering and Extended Half-Life Advantage: The company’s core technological advantage lies in its antibody engineering platform, which incorporates half-life extension technologies such as YTE and LS modifications. These innovations enable less frequent dosing—potentially every three to six months—compared to existing therapies that require more frequent administration. This reduced injection burden directly addresses a key limitation of current biologics, improving patient compliance and potentially enhancing long-term treatment outcomes.
- Large Market Opportunity with High Unmet Need: Apogee is targeting diseases with substantial global prevalence and unmet medical needs, particularly in atopic dermatitis and asthma. Despite existing biologics, a significant proportion of patients remain inadequately controlled, highlighting the need for more effective and convenient therapies. Market research cited in the report indicates strong physician and patient interest in therapies offering improved efficacy and less frequent dosing, reinforcing the commercial potential of the company’s pipeline.
Growth Challenges
- Early-Stage Development and Regulatory Uncertainty: Apogee remains a clinical-stage biotechnology company with no approved products, making its future revenue generation highly dependent on successful clinical trial outcomes and regulatory approvals. All product candidates are still under investigation, and there is no assurance that they will achieve approval or commercial viability. The inherent uncertainty associated with clinical development timelines and regulatory pathways presents a significant risk to the company’s long-term prospects.
- Dependence on External Funding and Cash Burn: The company’s operations are heavily reliant on external funding to support ongoing clinical trials and pipeline expansion. As a pre-revenue entity, Apogee is expected to continue incurring significant operating losses, with capital requirements tied to expensive late-stage trials and commercialization efforts. Any disruption in access to capital markets or unfavorable financing conditions could materially impact its development plans.
- High Execution Risk in Clinical and Commercial Strategy: The success of Apogee’s strategy depends on its ability to execute across multiple complex areas, including clinical development, manufacturing, regulatory approval, and eventual commercialization. Delays in trial timelines, failure to replicate early-stage efficacy in later trials, or challenges in scaling manufacturing could hinder progress. Additionally, combination therapies such as APG279 and APG273 introduce further complexity in development and regulatory approval pathways.
- Intense Competitive Landscape and Market Adoption Risk: The inflammatory and immunology space is highly competitive, with established biologics such as DUPIXENT and emerging therapies targeting similar pathways. Even if approved, Apogee’s therapies must demonstrate clear differentiation in efficacy, safety, or dosing convenience to gain market share. Furthermore, physician prescribing behavior and payer reimbursement dynamics could impact adoption, particularly in a market with multiple well-entrenched treatment options.
Key Risks:
- Clinical Development Uncertainty: Pipeline success remains contingent on favorable outcomes in ongoing and future trials, with risk of delays or failure to replicate early efficacy.
- Regulatory Approval Risk: Product candidates may face challenges in securing timely approvals or meeting evolving regulatory requirements.
- Funding and Cash Burn Pressure: Continued reliance on external capital to finance operations and late-stage trials may lead to dilution or funding constraints.
- Competitive Intensity: Established biologics and emerging therapies in inflammatory diseases could limit market share and pricing power..
Technical Observation (on the daily chart):
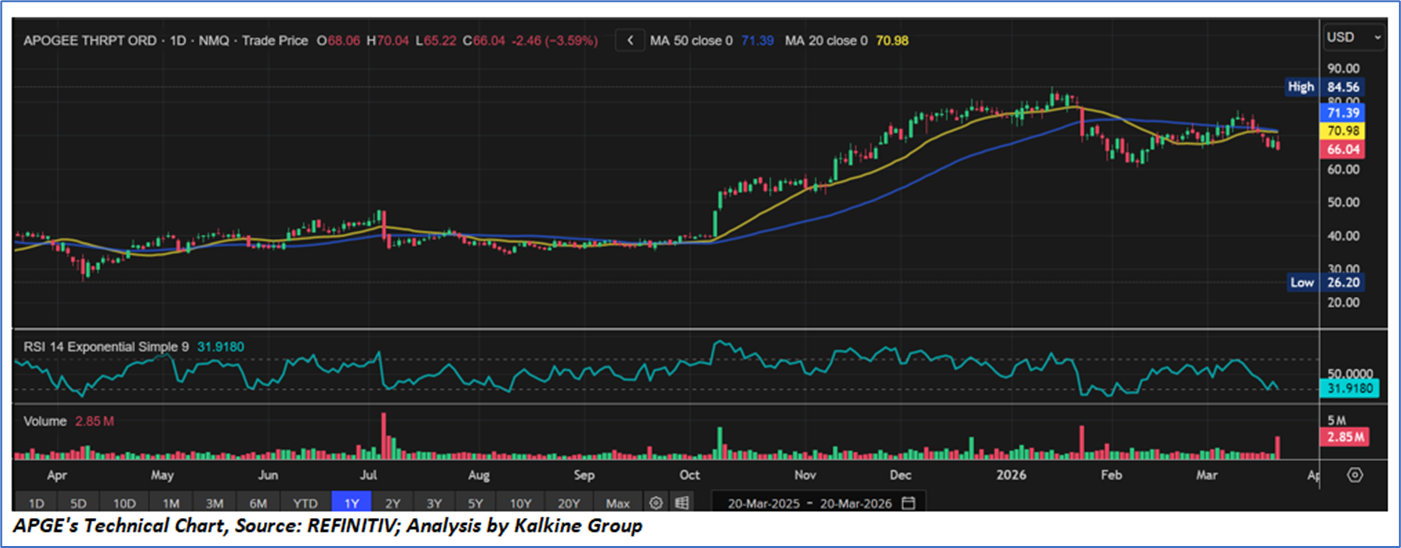
- Trend Structure: The stock witnessed a strong uptrend from October to January, forming higher highs and higher lows, but has since transitioned into a sideways-to-down consolidation phase.
- Moving Averages Signal: Price has slipped below both the 20-day (USD 70.98) and 50-day (USD 71.39) moving averages, indicating a short-term bearish crossover and loss of upward momentum.
- RSI Momentum: RSI is trending near 32, approaching oversold territory, reflecting weak momentum but potential for a near-term technical bounce.
- Volume Trends: Increased volume during recent declines indicates distribution, suggesting selling pressure is currently stronger than buying interest.
Apogee Therapeutics presents a balanced investment case, supported by a differentiated biologics pipeline demonstrating strong early clinical efficacy, a scalable antibody engineering platform enabling extended dosing, and exposure to large unmet markets in inflammatory diseases. However, these strengths are counterbalanced by its pre-revenue status, reliance on continued external funding, and significant execution and regulatory risks inherent in clinical-stage biotech development. Additionally, competitive intensity from established biologics may challenge future market penetration, making the company’s outlook highly dependent on successful late-stage trial outcomes and clear clinical differentiation.
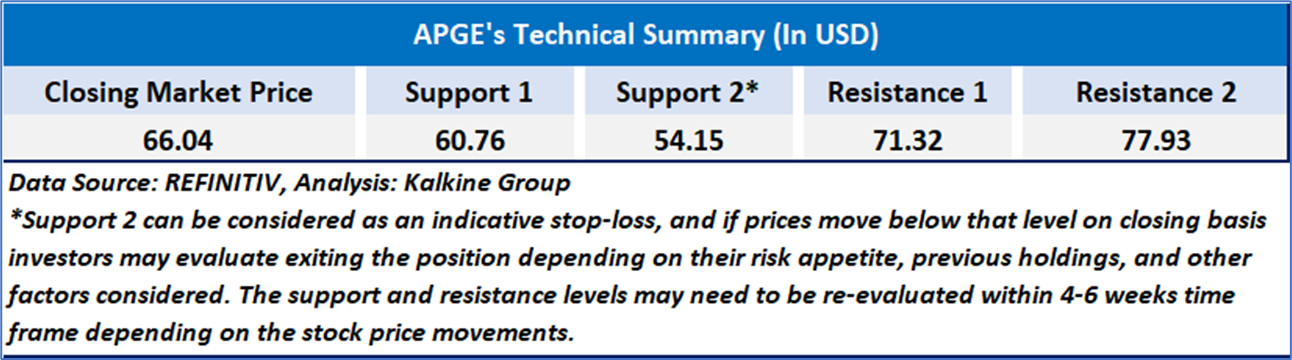
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Apogee Therapeutics (NASDAQ: APGE) at the closing market price of USD 66.04 as of March 20,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 20,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...