
Frontline PLC
Frontline PLC (NYSE: FRO), headquartered in Cyprus, operates in the global marine transportation sector, specializing in the seaborne transport of crude oil and refined petroleum products. The Company operates a diversified international fleet of VLCC, Suezmax, and LR2/Aframax tankers, supporting worldwide crude and product tanker operations.
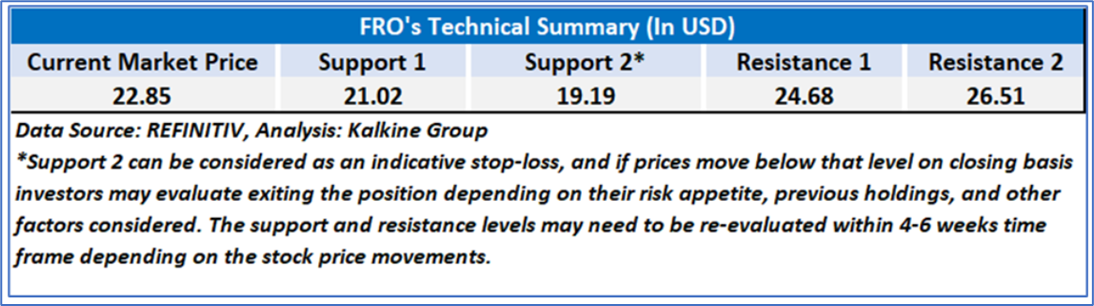
As per US Dividend Income Report published on ‘FRO’ on Jan 07, 2026, Kalkine provided an ‘Buy’ stance on the stock at USD 22.85 based on fundamental analysis and the stock price has now moved up by ~ 15.05% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Sustained Profitability and Earnings Visibility: Frontline reported a profit of USD 40.3 million in Q3 2025 and an adjusted profit of USD 42.5 million, demonstrating continued earnings generation despite seasonal softness. The company also declared a cash dividend of USD 0.19 per share, reinforcing confidence in distributable profits.
- Strong Spot Market Exposure with Multi-Year High Freight Rates: Spot TCE earnings remained robust, with VLCCs at USD 34,300/day, Suezmax at USD 35,100/day, and LR2/Aframax at USD 31,400/day, while Q4 spot TCEs already contracted are materially higher.
- Structural Improvement in Cost Base via Debt Optimization: The conversion of USD 405.5 million of term loans into revolving reducing credit facilities, followed by USD 374.2 million of prepayments, reduced fleet cash breakeven rates by ~USD 1,300 per day over the next 12 months. This structural cost reduction enhances embedded profitability.
- Realized Asset Value Uplift and Capital Recycling: The sale of the oldest Suezmax vessel generated a USD 5.9 million accounting gain and ~USD 23.7 million of net cash proceeds, validating higher second-hand asset values amid rising freight markets. This transaction provides a market-based benchmark supporting valuation gains across the remaining fleet.
- Strong Cash Flow Generation and High Implied Free Cash Flow Yield: The fleet generates approximately 30,000 earnings days annually, and at current spot rates implies a free cash flow yield of ~33%. Such elevated cash generation capacity supports the economic justification for asset and earnings valuations.
- Favorable Industry Fundamentals and Asset Re-Pricing Momentum: Record levels of oil in transit, longer trade routes, sanctions-driven demand for compliant tonnage, and a constrained orderbook through 2028 have driven multi-year high freight rates and early signs of tanker asset re-pricing. These macro and sector tailwinds materially enhance the notional value of Frontline’s modern, compliant fleet.
- Modern, Efficient Fleet with Limited Replacement Risk: Frontline operates a 100% ECO fleet with an average age of ~7 years, while a significant portion of the global tanker fleet exceeds 15–20 years. With no newbuilding commitments and limited effective fleet growth industry-wide, the company’s vessels benefit from scarcity value.
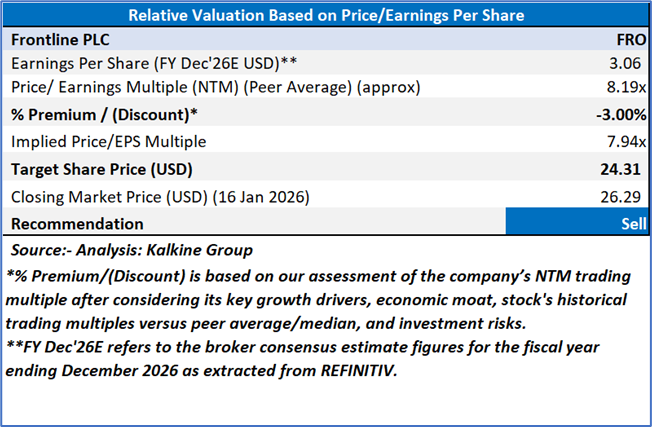
Valuation (Using Price/Earnings Multiple)
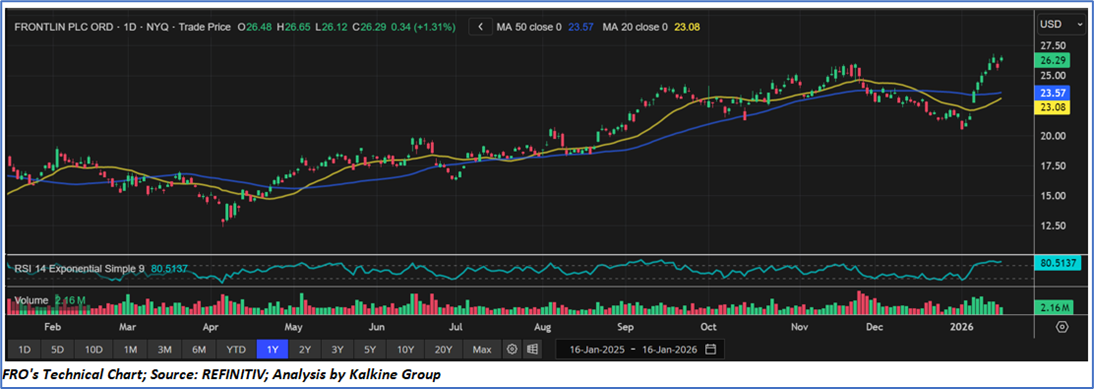
Share Price Chart
Conclusion
Frontline’s outperformance is supported by company’s consistent earnings generation, strong forward visibility, and improving structural fundamentals. In Q3 2025, the company delivered USD 40.3 million in net results and USD 42.5 million on an adjusted basis, supported by solid spot TCE rates across vessel classes and higher Q4 rates already secured. Balance sheet optimization through material debt prepayments has structurally reduced cash breakeven levels by approximately USD 1,300 per day, strengthening underlying cash flow capacity. In addition, asset transactions provide evidence of firmer tanker values, while favorable industry conditions—record oil in transit, longer trade routes, sanctions-driven demand for compliant tonnage, and limited effective fleet growth—continue to support rate strength and asset value normalization.
Considering improved earnings visibility, a structurally lower cost base, firm forward freight rates, and strengthening tanker asset values driven by favorable industry dynamics, a "Sell" recommendation on Frontline PLC (NYSE: FRO) has been given at the closing market price of USD 26.29 as on 16 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 16 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...