GeoPark Ltd
GeoPark Ltd (NYSE: GPRK) is a Colombia-based energy company engaged in the exploration, production, and consolidation of oil and gas assets. The Company maintains operations and growth platforms across Colombia, Ecuador, Chile, and Brazil. It holds working interests in 42 hydrocarbon blocks, encompassing both natural gas and crude oil exploration and production activities. Its portfolio spans onshore and offshore acreage totaling more than 700,000 acres.

GPRK’s Fourth Quarter 2025 Operational Update for the period ended December 31, 2025 (Q4FY25)
- Production Outperformance and Portfolio Optimization: GeoPark delivered full-year 2025 production of 28,233 boepd, exceeding the upper end of its guidance range of 26,000–28,000 boepd, supported by resilient base output in Colombia and Argentina. Fourth-quarter production averaged 28,351 boepd, reflecting stable sequential growth and new volumes from recently integrated Vaca Muerta assets. During the year, the company streamlined its portfolio by divesting non-core assets in Ecuador and Brazil, including the Manati gas field and the Espejo and Perico blocks, reinforcing its focus on core, higher-return operations.
- Llanos 34: Secondary Recovery and Polymer Injection Progress: The Llanos 34 Block remained the principal production hub, delivering 16,137 boepd net in 4Q2025 despite a modest sequential decline linked to maintenance and water management constraints. Waterflooding contributed approximately 18% of gross output, while a 28-well workover campaign added incremental volumes and significantly reduced water production. Importantly, the polymer injection project commenced in late December, marking a strategic step to enhance secondary recovery and support long-term reservoir performance.
- Operational Challenges and Regional Developments: Production at the non-operated CPO-5 Block declined 13% quarter-on-quarter due to temporary blockades, though volumes normalized following their resolution. In Argentina, GeoPark successfully completed the operational transition of newly acquired Vaca Muerta assets, establishing a local operating base and achieving early production gains, including a 25% uplift from artificial lift optimization at Pad 1020. Meanwhile, exploration and appraisal success in the Llanos 123 Block drove a 26% sequential production increase, partially offset by an unsuccessful exploratory well in Llanos 104.
- Near-Term Activity and Strategic Direction: Looking ahead to 1Q2026, GeoPark plans to drill five to six wells in Colombia, focusing on development opportunities in Llanos 34 and Llanos 123, while advancing rig mobilization and drilling preparations in Argentina. The company also announced a board transition with the departure of a long-serving director, with succession planning underway. Overall, the quarter underscored disciplined execution, portfolio optimization, and continued investment in enhanced recovery initiatives to sustain production stability.
Operational Performance for the quarter ended September 30, 2025 (Q3FY25)
- Stable Production Delivery: During the third quarter of 2025, GeoPark reported consolidated average production of 28,136 boepd, reflecting consistent operational execution across its core assets and positioning output within the upper end of full-year guidance. The Company maintained steady volumes from its operated and non-operated fields, supported by disciplined field management and improved efficiencies. This stable production base underpinned overall quarterly performance despite a relatively softer year-on-year commodity price environment.
Financial Performance for the quarter ended September 30, 2025 (Q3FY25)
- Revenue Growth and Margin Stability: Revenue for the quarter reached $125.1 million, marking a 4% sequential increase driven by improved volumes and steady realized pricing. Adjusted EBITDA totaled $71.4 million, delivering a strong 57% margin and remaining broadly stable compared to the prior quarter. Operating costs were maintained at $12.5 per boe, reflecting continued cost discipline and operational efficiency. Net income amounted to $15.9 million, reversing the loss recorded in 2Q2025 and highlighting the Company’s earnings resilience.
Capital Allocation and Operational Efficiency
- Focused Investment and Cost Optimization: Capital expenditures during the quarter totaled $17.5 million, primarily directed toward sustaining and enhancing production at the Llanos 34 Block and advancing exploration activities in the Llanos Basin. Five rigs were active at quarter-end, supporting drilling and workover programs across key assets. The Company also continued to implement efficiency initiatives, contributing to structural cost savings and reinforcing its commitment to disciplined capital deployment.
Balance Sheet Strength and Shareholder Returns
- Liquidity, Debt Optimization, and Dividend Policy: GeoPark ended 3Q2025 with cash and cash equivalents of $197.0 million, supported by solid operating cash flow generation. Net debt stood at $373.4 million, with a conservative leverage ratio of 1.2x and no principal maturities until 2027. During the quarter, the Company repurchased $33.0 million of its 2030 Notes below par, enhancing capital structure efficiency and reducing future interest obligations. In parallel, a revised dividend program was introduced, aligning shareholder distributions with upcoming investment requirements while preserving financial flexibility.
Key Risks:
- Commodity Price Volatility: Earnings and cash flows remain highly sensitive to fluctuations in Brent crude prices, despite partial hedging coverage, potentially impacting margins and capital plans.
- Execution Risk in Vaca Muerta Development: Scaling unconventional operations in Argentina requires timely permitting, infrastructure build-out, and drilling performance consistency, which may affect projected returns and timelines.
- Operational and Reservoir Performance Risk: Enhanced recovery initiatives such as polymer injection and waterflood optimization in Llanos 34 carry subsurface and execution uncertainties that could influence production sustainability.
- Geopolitical and Regulatory Exposure: Concentrated operations in Colombia and Argentina expose the company to changes in fiscal regimes, environmental regulations, social disruptions, and local permitting processes.
Technical Observation (on the daily chart):
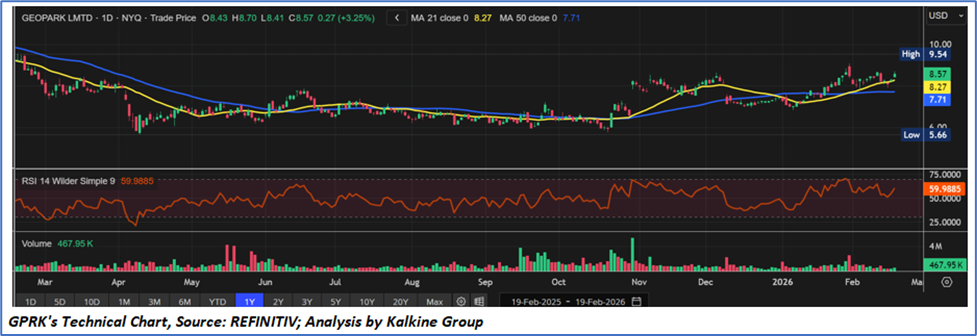
- The stock has shifted from a prolonged consolidation phase into a developing uptrend, forming higher highs and higher lows since late Q4, indicating strengthening bullish sentiment.
- The 21-day moving average (USD8.27) is positioned above the 50-day moving average (USD7.71), maintaining a positive crossover. The current price (USD8.57) trades above both averages, supporting a constructive short-term bias.
- The RSI (14) is near 60, reflecting positive momentum without entering overbought territory. This suggests scope for additional upside, though momentum appears to be stabilizing near current levels.
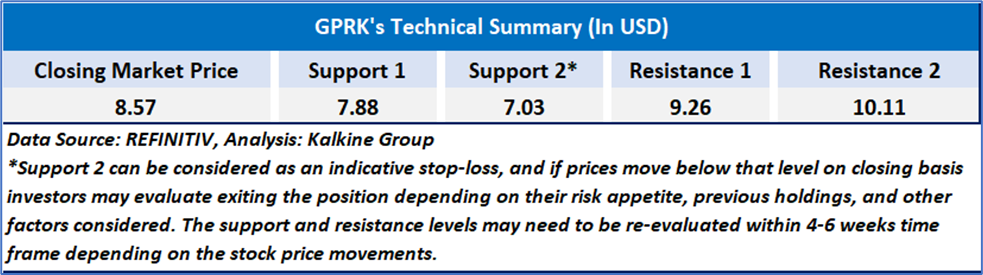
- Immediate resistance is seen around 9.50–9.60 (recent swing high). A breakout above this zone could extend gains.
- Initial support lies near 8.25–8.30 (21-day MA), followed by stronger support around 7.70 (50-day MA). A breakdown below 7.70 would weaken the current bullish setup.
- Volume activity has been moderate, with periodic spikes accompanying upward moves, suggesting selective accumulation. Stronger volume on a breakout would confirm continuation strength.
GeoPark delivered a resilient operational and financial performance through late 2025, exceeding full-year production guidance with stable output across Colombia and early contributions from its Vaca Muerta assets in Argentina. The company strengthened its portfolio by divesting non-core assets, advanced enhanced recovery initiatives such as polymer injection at Llanos 34 and demonstrated disciplined cost control with strong EBITDA margins and positive net income recovery in Q3FY25. Supported by solid liquidity, proactive debt optimization, and a balanced capital allocation strategy, GeoPark appears well-positioned to fund near-term growth while maintaining financial flexibility and operational stability.
Based on above-guidance production during Q4FY25, disciplined cost management, portfolio optimization, and strengthened balance sheet, a ‘Buy’ rating has been given GeoPark Ltd (NYSE: GPRK) at the closing market price of USD 8.57 as of Feb 19,2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is February 19,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...