
Target Corporation
Target Corporation (NYSE: TGT) operates as a general merchandise retailer, serving customers through an integrated network of physical stores and digital channels. The company offers a broad assortment of everyday essentials alongside differentiated, design-led merchandise, positioned at accessible and value-oriented price points.
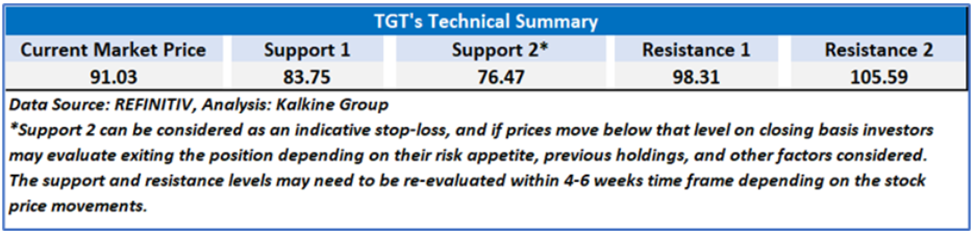
As per US Inflation Report published on ‘TGT’ on Nov 28, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 91.03 based on fundamental analysis and the stock price has now moved up by ~ 15.92% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Persistent Top-Line Pressure and Weak Comparable Sales: Target continued to face revenue headwinds during the quarter, reflecting ongoing pressure on consumer discretionary spending. Comparable sales declined by 2.7% in Q3 FY2025, with store comps down approximately 4%, underscoring reduced in-store traffic and cautious consumer behavior. While digital sales posted modest growth, it was insufficient to offset broader softness, particularly in discretionary categories such as Home and Apparel. Management acknowledged that the business remains below its potential and has yet to return to sustained positive comparable sales growth.
- Margin Compression from Markdowns and Cost Pressures: Profitability remained under strain despite operational improvements. Gross margin declined to 28.2%, around 10 basis points lower year-on-year, primarily due to higher markdown activity as the company worked through discretionary inventory. Although improvements in inventory shrink and supply chain productivity provided partial offsets, these benefits were not enough to fully counterbalance pricing pressure and sales deleveraging. As a result, earnings performance remained subdued relative to historical levels.
- Elevated Operating Expenses and Restructuring Impact: Target’s operating cost structure reflected ongoing transformation challenges. SG&A expense rate rose to 21.9%, about 60 basis points higher than the prior year, driven largely by one-time business transformation and restructuring costs. The company eliminated approximately 1,800 headquarters roles, highlighting internal complexity and the need to simplify decision-making. While management positioned these actions as necessary for long-term agility, they weighed on near-term earnings and underscored execution risk during the transition period.
- Earnings Decline and Cautious Forward Outlook: Bottom-line performance weakened compared to last year, with GAAP EPS declining to USD 1.51 from USD 1.85 and adjusted EPS falling around 4% year-on-year. Continued volatility in monthly sales trends and subdued consumer confidence prompted management to narrow full-year guidance and move adjusted EPS expectations toward the lower end of the prior range. The outlook reflects uncertainty around demand recovery and highlights that a return to consistent, profitable growth remains a work in progress.
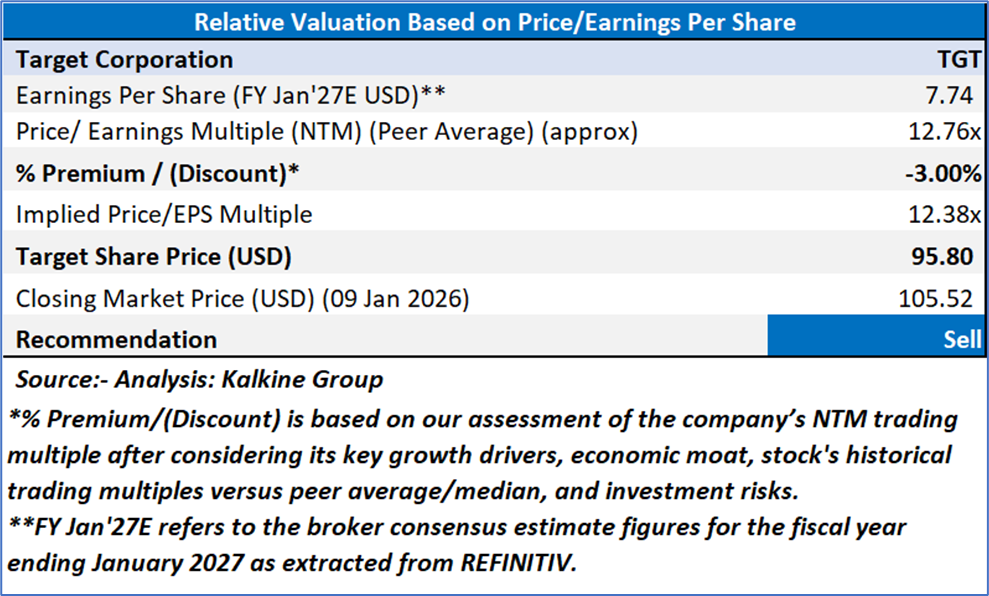
Valuation (Using P/E Multiple)
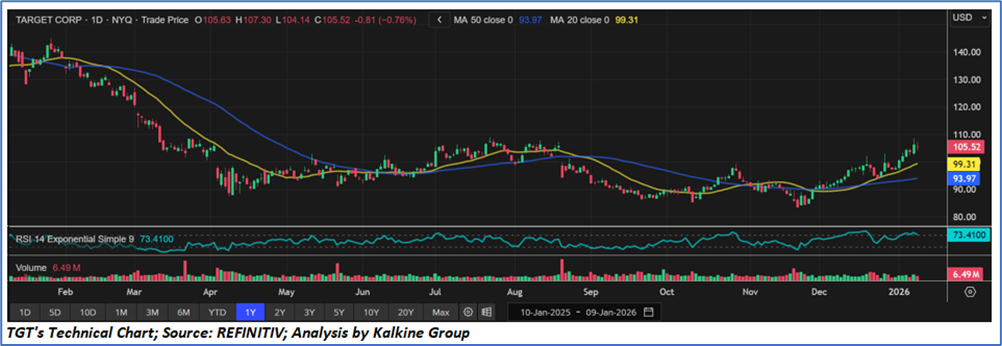
Share Price Chart
Conclusion
Target’s recent performance reflects a challenging operating environment marked by sustained pressure on discretionary demand, margin headwinds, and elevated execution risk. Comparable sales remain negative, driven by weak store traffic and softness in categories such as Home and Apparel, while increased markdowns have constrained gross margins. Although cost restructuring and operational initiatives are underway, they have introduced near-term expense pressure and weighed on earnings. With adjusted EPS declining year-on-year and management guiding cautiously amid volatile consumer behavior, the company has yet to demonstrate a clear and durable return to profitable growth.
Moreover, Target’s expansion of its wellness assortment by 30% for 2026, supported by the introduction of thousands of new, affordable and on-trend products and reinforced by promotional initiatives such as Target Wellness Week, represents a near-term positive catalyst that could drive investor optimism and share price appreciation. Given this potential sentiment-driven upside and the stock’s sensitivity to category-specific growth narratives, a "Sell" recommendation on Target Corporation (NYSE: TGT) has been given at the closing market price of USD 105.52 as on 09 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 09 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...