
JPMorgan Chase & Co.
JPMorgan Chase & Co. (NYSE: JPM) is a diversified financial holding company that provides a broad range of banking and financial services. Its activities span investment banking, consumer and small business banking, commercial lending, payment and transaction services, and asset and wealth management. The firm reports results across three primary business segments: Consumer & Community Banking (CCB), Commercial & Investment Bank (CIB), and Asset & Wealth Management (AWM).
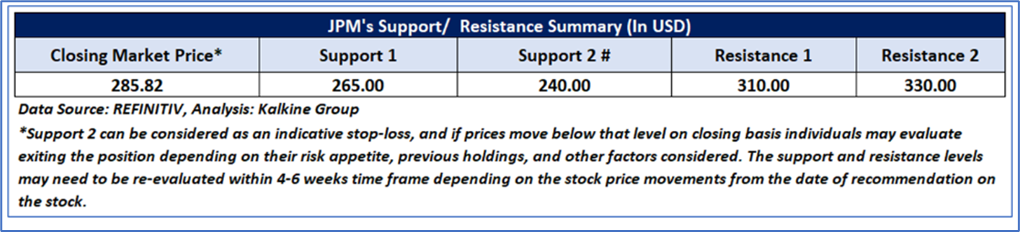
As per Kalkine’s Diversified Opportunities Report published on ‘JPM’ on Jul 17, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 285.82 based on fundamental analysis and the stock price has now moved up by ~ 17.33% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Rising Credit Costs and Emerging Risk Events: The company is experiencing a clear uptick in credit costs, reflecting both normalization and emerging stress in certain portfolios. Total credit costs reached USD 3.4 billion in 3Q25, including USD 2.6 billion of net charge-offs and an USD 810 million net reserve build, with wholesale charge-offs elevated by instances of borrower-related collateral irregularities in secured lending facilities. Management also highlighted that isolated fraud-related incidents—such as the Tricolor exposure—contributed materially to losses, signaling that risk controls continue to be tested in the current environment.
- Expense Growth Outpacing Operating Leverage: Expenses continue to rise meaningfully, pressuring operating efficiency. Total expense increased 8% year-on-year to USD 24.3 billion in 3Q25, driven primarily by higher compensation, brokerage and distribution costs, auto lease depreciation and marketing expense. Management acknowledged structural cost pressures such as labor inflation and healthcare expense escalation, while also noting that higher investment and performance-linked spending are likely to persist. This indicates that moderating the growth trajectory of expenses may remain challenging in the medium term.
- Margin Compression and Rate-Driven Profit Headwinds: Despite revenue growth, the firm continues to face rate-related profit headwinds. Net interest income excluding Markets was broadly flat year-on-year, as lower interest rates and deposit margin compression offset balance growth and increased card revolving volumes. Management also emphasized that forward interest-rate expectations remain a headwind to future earnings, particularly as the company remains asset-sensitive and credit card revolve growth begins to normalize. This dynamic limits upside from traditional balance-sheet spread income.
- Potential Vulnerability to Macro and Credit Cycle Shifts: While current consumer credit trends remain resilient, management continues to flag elevated macro uncertainty and the risk of labor-market deterioration. They cautioned that any weakening in employment conditions would likely translate into worsening consumer credit performance, particularly given the normalization under way in revolving credit and wholesale portfolios. Additionally, exposure to non-bank financial institutions and structured credit is acknowledged as an area where losses may prove more volatile in a downturn, even if current risk controls are judged adequate.
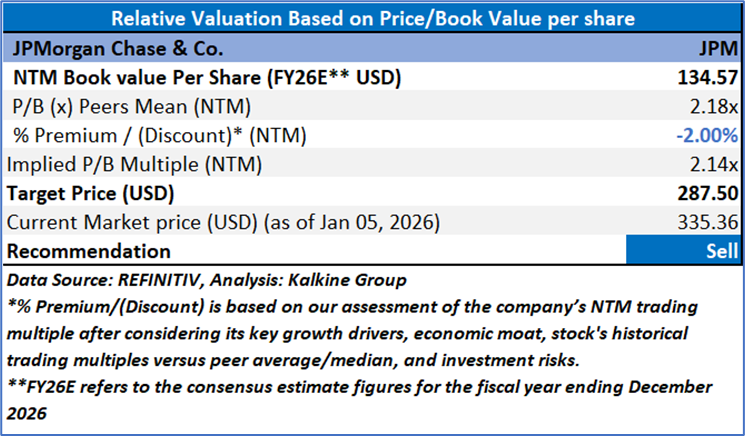
Valuation (Using Price/Book Multiple)
Share Price Chart
Conclusion
The company faces mounting financial pressures despite solid top-line performance, as rising credit costs and emerging loss events signal increasing risk across both consumer and wholesale portfolios. Total credit costs rose to USD 3.4 billion in 3Q25, including elevated wholesale charge-offs linked to borrower collateral irregularities, highlighting vulnerability in parts of the lending book. At the same time, expense growth of 8% year-on-year continues to erode operating leverage, driven by structurally higher labor, compensation and marketing costs. Furthermore, rate-driven margin compression has constrained growth in net interest income outside Markets, limiting earnings upside even as balance-sheet volumes expand. Taken together, these trends underline a less favorable risk-reward profile and growing sensitivity to macro and credit-cycle deterioration.
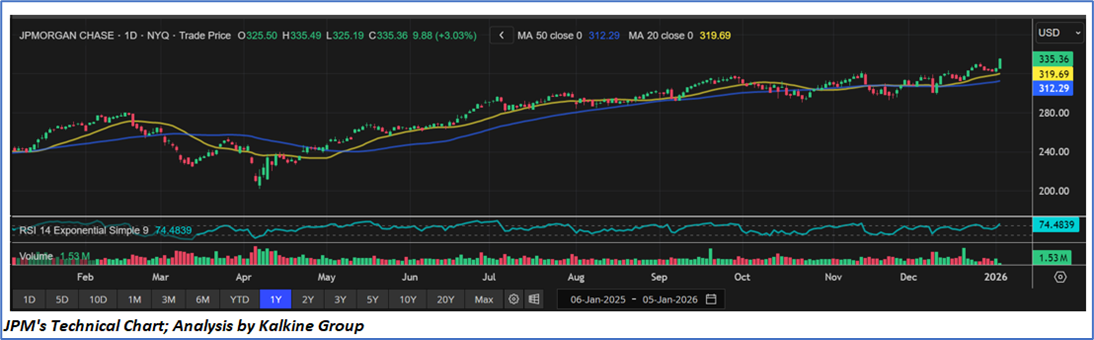
Based on the notional gains, valuation downside and price action stance, a "Sell" recommendation on JPMorgan Chase & Co. (NYSE: JPM) has been given at the current market price of USD 335.36 as on 05 January 2026 at 8:20 am PST.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 05 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...