
Citizens Financial Group, Inc.
Citizens Financial Group, Inc. (NYSE: CFG) offers a wide range of banking products and services across both retail and commercial markets, serving individuals, small businesses, mid-sized companies, large corporates, and institutional clients. The company organizes its activities into two main divisions: Consumer Banking and Commercial Banking.
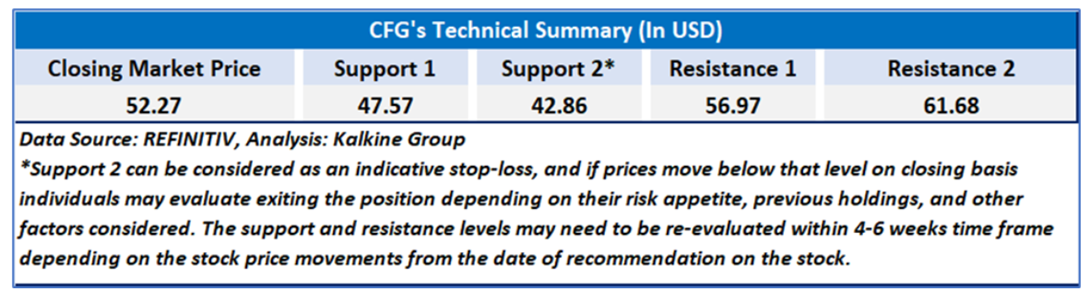
As per previous Kalkine’s Diversified Opportunities Report published on ‘CFG’ on Sep 18, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 52.27 based on fundamental analysis and the stock price has now moved up by ~ 18.88% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Rationale:
- Rising Operating Costs and Efficiency Pressure: Citizens Financial Group continues to grapple with rising operating expenses that are outpacing historical trends. Noninterest expense increased 7% year-over-year to USD 1.34 billion, driven mainly by higher salaries and benefits tied to Private Bank and Capital Markets expansion, as well as increased technology and vendor spending. While management points to productivity initiatives, the efficiency ratio—at 63%—remains elevated versus best-in-class peers. This signals that cost discipline still has room to improve even as the bank scales newer initiatives.
- Persistent Exposure to Commercial Real Estate Weakness: The bank remains meaningfully exposed to stress within the Commercial Real Estate (CRE) sector—particularly general office properties. Although Citizens has increased reserve coverage to 12.4% on this portfolio, cumulative charge-offs since early 2023 total roughly USD 527 million, and the portfolio continues to shrink through paydowns and losses. Management’s allowance continues to factor in recessionary stress scenarios, underscoring that credit normalization and CRE weakness remain ongoing headwinds that could pressure earnings if macro conditions deteriorate.
- Margin and Funding Cost Sensitivity: Despite modest improvement in net interest margin to 3.00%, Citizens remains highly sensitive to funding costs and deposit competition. Interest-bearing deposit costs stand at 2.35%, weighing on profitability relative to prior cycles. Although the bank reports stabilization in deposit betas, the shift toward higher-yielding products and the runoff of non-core portfolios signal that the institution must continue carefully managing pricing and balance-sheet mix to sustain earnings momentum. Any reversal in rate trends or competitive pricing pressure could compress margins.
- Execution Risk in Strategic Growth Initiatives: The company continues significant investment in strategic businesses such as the Private Bank and expanded Capital Markets platform. While these initiatives are contributing to earnings, they also introduce execution risk, including elevated expense levels, talent acquisition costs, and the need to successfully scale new markets. Performance targets assume continued customer growth and favorable capital markets conditions—both of which may prove volatile. Sustained delivery will be critical to justify the higher operating base now embedded in the cost structure.
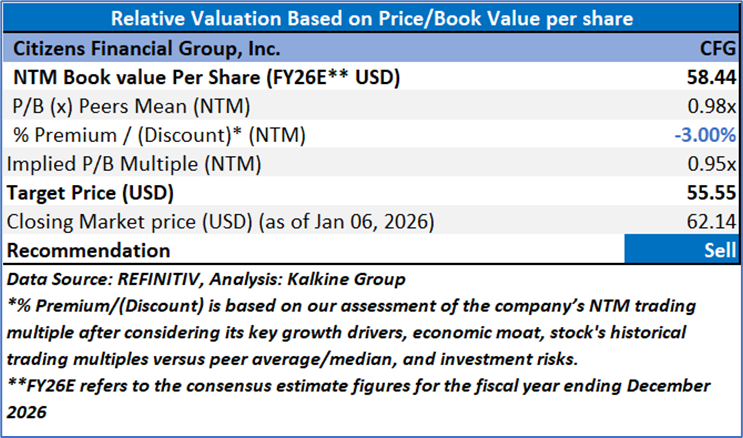
Valuation (Using Price/Book Multiple)
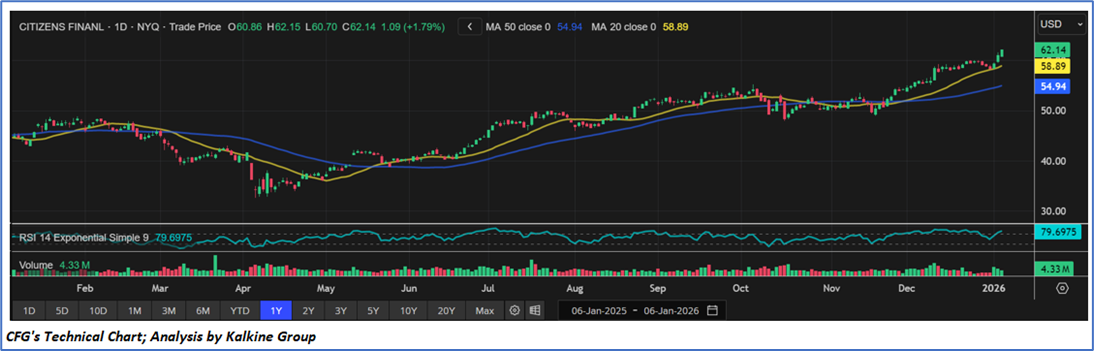
Share Price Chart
Conclusion
Citizens Financial Group still faces meaningful headwinds despite solid headline results. Operating costs continue to trend higher due to hiring, technology spending and expansion initiatives, keeping the efficiency ratio elevated at 63% and signaling ongoing pressure on profitability. At the same time, the bank retains exposure to stressed commercial real estate—particularly the general office segment—where elevated loss reserves and prior charge-offs highlight continued credit risk. Funding costs also remain structurally higher, with interest-bearing deposits costing 2.35%, leaving earnings sensitive to competitive pressures and rate trends. Finally, the bank’s heavy investment in growth platforms such as the Private Bank adds execution risk, as these strategies must scale successfully to justify the higher cost base already embedded in operations.
Based on the notional gains, valuation downside and price action stance, a "Sell" recommendation Citizens Financial Group, Inc. (NYSE: CFG) has been given at the closing market price of USD 62.14 as on 06 January 2026.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 06 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...