
SoFi Technologies Inc
SoFi Technologies Inc. (NASDAQ: SOFI) is a member-centric digital financial services company offering an integrated platform that supports borrowing, saving, spending, investing, and financial protection. The business operates through three core segments: Lending, Technology Platform, and Financial Services.
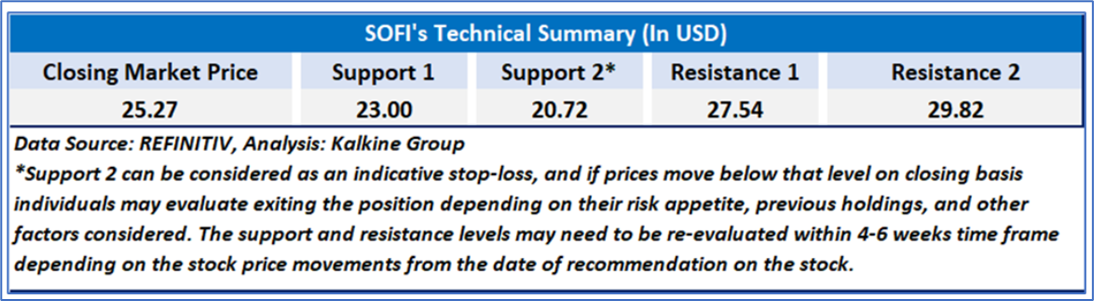
As per Kalkine’s Diversified Opportunities Report published on ‘SOFI’ on Dec 18, 2025, Kalkine provided an ‘Buy’ stance on the stock at USD 25.27 based on fundamental analysis and the stock price has now moved up by ~ 11.95% since then.
Noted below are the details of support and resistance levels provided in our previous report:
Macro-Level Developments:
- Product Innovation and Ecosystem Expansion Drive Differentiation: SoFi’s strategic focus on product innovation continues to strengthen its competitive positioning as a diversified digital financial platform. The introduction of SoFi Pay and the launch of the SoFi USD stablecoin underscore management’s intent to integrate blockchain-based solutions into mainstream financial services, expanding global payment capabilities and modernizing transaction infrastructure. The relaunch of the crypto trading platform and the rollout of SoFi Coach, an AI-powered personal finance tool, further enhance the company’s value proposition by addressing renewed interest in digital assets while delivering personalized financial insights. Together with the introduction of the SoFi Smart Card and the promotion of SoFi Plus through high-visibility marketing partnerships, these initiatives deepen customer engagement, improve ecosystem stickiness, and expand wallet share.
- Galileo Integration and Competitive Pressures Shape the Growth Outlook: The acquisition of Galileo Financial Technologies has evolved into a structural advantage for SoFi, enabling tighter integration between its consumer-facing products and core fintech infrastructure. By operating under a single corporate umbrella, SoFi benefits from improved speed to market, reduced reliance on third-party vendors, and greater control over the end-to-end customer experience across payments, lending, and digital banking. However, despite these strengths, SoFi continues to face intense competitive pressure from established banking giants such as JPMorgan and Bank of America, which are aggressively enhancing their digital and AI-driven offerings. As SoFi scales its platform, its ability to defend market share and sustain differentiation against these well-capitalized incumbents will remain a critical determinant of long-term performance.
Fundamental Standpoints:
- Reliance on Non-GAAP Metrics and Ongoing Reinvestment Requirements: The presentation highlights SoFi’s strong adjusted profitability; however, a notable limitation is the company’s heavy reliance on non-GAAP measures such as adjusted net revenue, adjusted EBITDA, and adjusted EPS. Management itself acknowledges that these metrics have analytical limitations and are not directly comparable across peers, potentially obscuring underlying GAAP volatility and true earnings quality. In addition, while margins have improved, the business model still requires sustained reinvestment in technology, marketing, and product development to maintain growth momentum, which could constrain free cash flow generation if revenue growth slows.
- Exposure to Credit Cycles and Balance Sheet Risk: Despite improving credit performance, SoFi remains materially exposed to macroeconomic conditions and credit cycles due to its sizable lending operations. The presentation shows significant growth in personal, student, and home loan originations, alongside a growing loan book retained on the balance sheet. While net charge-offs have moderated, cumulative net losses remain meaningful over the life of loans, and adverse economic conditions could pressure borrower performance, increase provisions for credit losses, and weigh on profitability. This exposure underscores an inherent sensitivity to interest rates, employment trends, and consumer financial health.
- Scaling Challenges and Segment Imbalances: Although SoFi has diversified into financial services and technology platforms, the lending segment continues to contribute a substantial share of revenue and profit, creating concentration risk. The technology platform segment, while profitable, delivers relatively modest growth compared with the rest of the business, and the financial services segment only recently transitioned from losses to positive contribution. As the company scales, maintaining balanced growth across segments, controlling operating expenses, and sustaining member acquisition efficiency will be critical challenges that could impact long-term returns if execution falters.
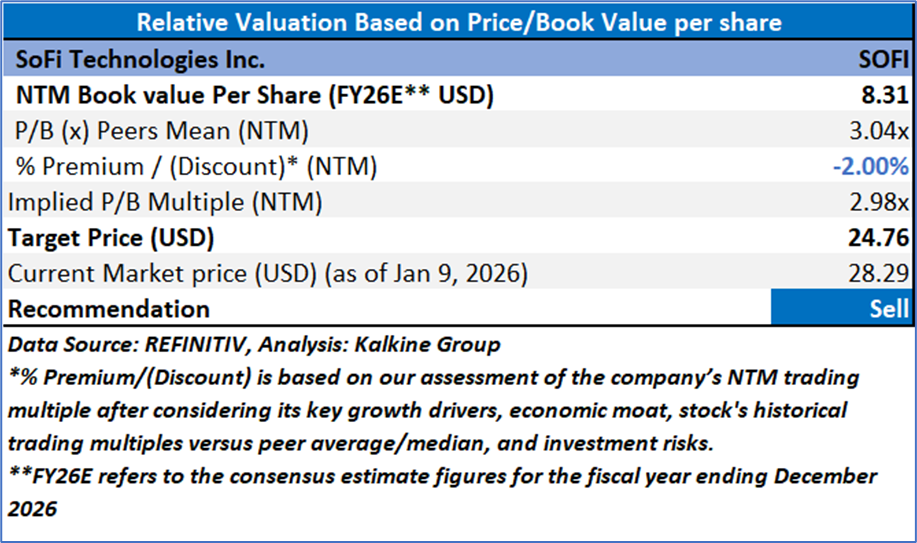
Valuation (Using Price/Book Multiple)
SOFI’s Share Price Chart
Conclusion
Overall, SoFi’s risk profile is shaped by a combination of financial transparency limitations, balance-sheet exposure, and execution challenges. The company’s heavy reliance on non-GAAP metrics may mask underlying earnings volatility and complicate peer comparisons, while continued reinvestment in technology, marketing, and product innovation remains necessary to sustain growth, potentially constraining cash generation. At the same time, SoFi’s expanding lending book exposes it to credit cycles, interest rate movements, and broader macroeconomic conditions, with cumulative loan losses posing a structural risk despite recent improvements in credit performance. Finally, the business remains unevenly balanced across segments, with lending still a major earnings driver, the technology platform delivering comparatively modest growth, and financial services only recently achieving profitability, making successful scaling and disciplined execution critical to sustaining long-term returns.
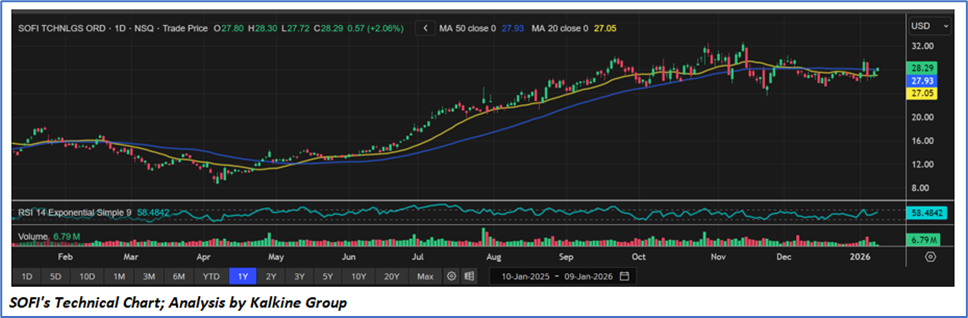
Based on sustained earnings momentum, expanding fee-based revenues, improved balance-sheet resilience, recent share price appreciation, and external risks, a "Sell" recommendation on SoFi Technologies Inc. (NASDAQ: SOFI) has been given at the current market price of USD 28.29 as on 9 January 2026 at 7:09 am PST.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is 9 January 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level which the stock is expected to reach as per the relative valuation method and/or technical analysis taking into consideration both short-term and long-term scenario.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the London Stock Exchange (LSE) and or REFINITIV. Typically, both sources (LSE and or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.’
Note 6: Dividend Yield may vary as per the stock price movement.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...