Northrop Grumman Corporation (NYSE: NOC)
Northrop Grumman Corporation (NYSE: NOC) is a global aerospace and defence technology company. Its segments include Aeronautics Systems, Defence Systems, Mission Systems, and Space Systems. Aeronautics Systems is engaged in the design, development, production, integration, sustainment and modernization of military aircraft systems for the United States Air Force, the United States Navy, other United States government agencies, and international customers.

Key Business and Financial Updates:
- Strong Backlog and Revenue Visibility: Northrop Grumman reported a robust USD 96 billion backlog at quarter-end, providing more than two years of sales coverage and reinforcing long-term revenue visibility. First-quarter 2026 awards totaled USD 9.8 billion, while reported sales reached USD 9.9 billion, representing 4% year-over-year growth and 5% organic growth. Management highlighted sustained demand momentum supported by rising U.S. and allied defense budgets, modernization priorities, and an increasingly favorable geopolitical backdrop.
- Segment Performance Led by Aeronautics and Defense Systems: Operational performance was driven by strong execution across key programs. Aeronautics Systems sales increased 17%, supported by higher B-21 bomber volume and ramping restricted programs, while margins improved to 9.3% due to the absence of prior-year B-21 loss provisions. Defense Systems sales rose 5% (10% organic growth), led by Sentinel missile modernization, tactical solid rocket motors, and integrated battle command programs. Mission Systems delivered 2% sales growth with margins expanding sharply to 15.1%, benefiting from favorable program adjustments.
- Major Growth Platforms: B-21, Sentinel and Missile Defense: Northrop continues to scale its highest-priority strategic programs. The company secured the Lot 4 LRIP contract for the B-21 Raider and finalized an agreement to increase annual production rates by 25%, supported by approximately USD 2.5 billion of company-funded investments over multiple years. Sentinel remains another major growth driver, contributing low double-digit growth in the quarter, with first flight targeted in 2027 and initial operating capability in the early 2030s. Missile defense and weapons businesses now each represent nearly 10% of company sales, offering above-average long-term growth potential.
- Profitability, Cash Flow and Capital Allocation: Northrop generated solid earnings with diluted EPS of USD 6.14, supported by higher sales and stronger segment income. Segment operating income exceeded USD 1 billion, with consolidated segment margin improving to 10.8%. First-quarter free cash flow reflected a seasonal USD 1.8 billion use of cash, though management expects a meaningful ramp later in the year. The company repaid USD 527 million of fixed-rate debt during the quarter and ended with over USD 2 billion in cash, maintaining financial flexibility while continuing strategic investments.
- 2026 Outlook and Strategic Demand Environment: Management reaffirmed full-year 2026 guidance for revenue of USD 43.5 billion to USD 44.0 billion, with expectations for accelerating sales through the year and high single-digit sequential growth in Q2. Full-year segment operating margin is projected in the low-to-mid 11% range, while free cash flow guidance remains USD 3.1 billion to USD 3.5 billion despite higher CapEx of USD 1.85 billion. Leadership emphasized an “opportunity-rich environment,” citing expanding U.S. budgets, urgent Middle East and European demand, and upcoming competitive awards such as F/A-XX, which could provide upside beyond current guidance.
Key Company specific risks for NOC:
- Program Execution and Fixed-Price Contract Risk: Delays, cost overruns, or unfavorable revisions on major programs such as B-21, Sentinel, and space systems could pressure margins, cash flow, and earnings visibility.
- S. Government Budget and Procurement Dependence: A substantial portion of Northrop Grumman’s revenue is tied to U.S. defense spending, making results sensitive to budget delays, shifting priorities, contract timing, or political uncertainty.
- Supply Chain and Production Ramp Risk: Rapid scaling of missile systems, aircraft production, and modernization programs depends on supplier capacity, labor availability, and timely component deliveries, which could constrain growth execution.
Technical Observation (on the daily chart):
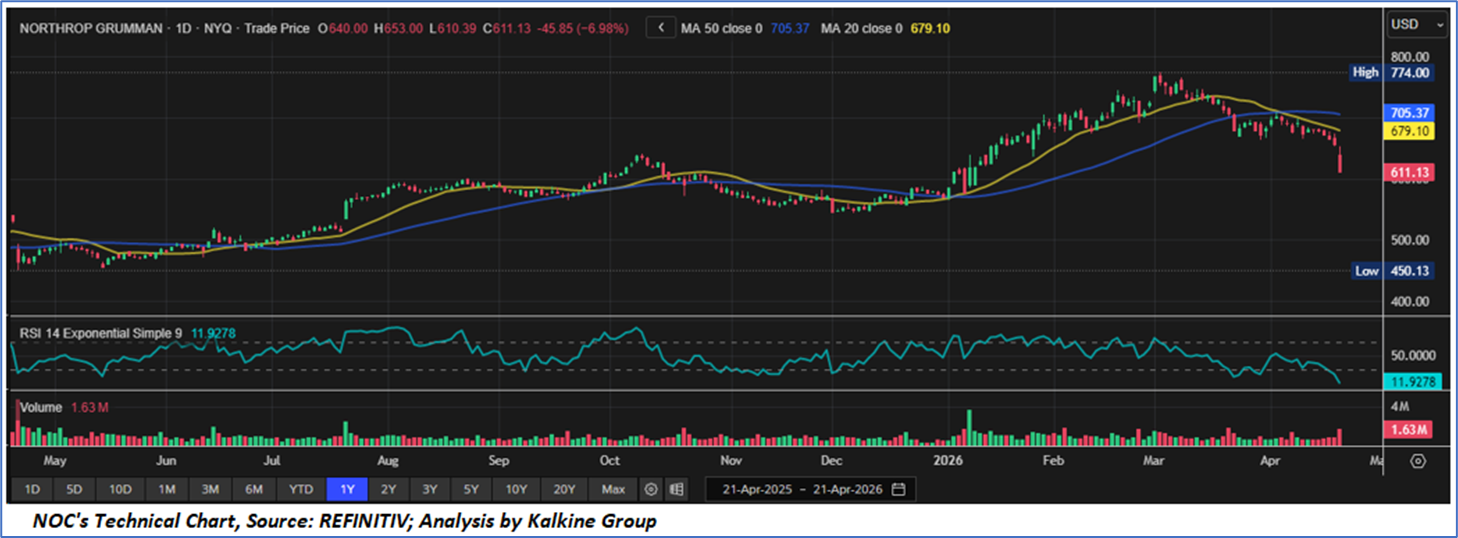
- Trend Breakdown and Structural Weakness: NOC has entered a pronounced corrective phase following its failure to sustain the prior uptrend that peaked near USD 774.00. The stock has now broken decisively below both the 20-day moving average (USD 679.10) and the 50-day moving average (USD 705.37), confirming a deterioration in intermediate-term trend structure. The steep decline toward USD 611.13 reflects aggressive distribution rather than orderly consolidation, with lower highs and lower lows now firmly established. The widening gap between spot price and declining moving averages indicates bearish momentum has accelerated materially, while the loss of prior support zones in the USD 650-660 range suggests sellers remain in control.
- Momentum, Volume and Internal Pressure: Momentum indicators have weakened sharply, with the 14-day RSI falling to approximately 11.93, an exceptionally oversold reading that signals intense downside pressure. While such compressed RSI levels can precede reflex rallies, they more immediately confirm capitulation-like selling conditions rather than durable stabilization. Volume activity has also expanded into the recent selloff, implying institutional participation in the downside move rather than low-liquidity weakness. The inability of RSI to show bullish divergence during the latest decline further suggests momentum exhaustion has not yet been conclusively established, leaving risk of additional near-term volatility elevated.
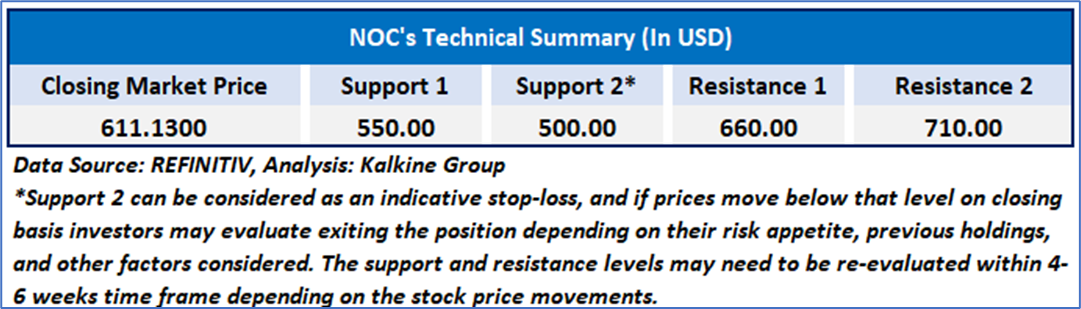
- Support Levels, Resistance Zones and Tactical Outlook: From a tactical perspective, immediate support is now concentrated near the USD 600 psychological zone, followed by stronger historical demand around USD 560–575. A decisive break below these levels could expose a deeper retracement toward the long-term reference area near USD 500. On the upside, any rebound is likely to encounter initial resistance at USD 650, followed by the more critical USD 679–705 band where the 20-day and 50-day moving averages converge. Unless NOC can reclaim these moving averages and re-establish higher lows, the prevailing bias remains defensively bearish. However, given the extreme oversold condition, a short-term technical bounce remains increasingly probable, though likely corrective rather than trend-changing at this stage.
Northrop Grumman Corporation (NYSE: NOC) reported solid first-quarter 2026 results supported by a strong USD 96 billion backlog, providing more than two years of sales coverage and reinforcing long-term revenue visibility. Quarterly sales increased 4% year-over-year to USD 9.9 billion, with growth led by Aeronautics Systems, Defense Systems, and key strategic programs such as B-21 Raider, Sentinel, missile defense, and tactical propulsion systems. Management reaffirmed full-year 2026 guidance of USD 43.5 billion to USD 44.0 billion in revenue and USD 3.1 billion to USD 3.5 billion in free cash flow, while continuing elevated capital investment to expand production capacity. Although demand trends remain favorable amid rising global defense spending, risks include execution on fixed-price programs, supply-chain scaling challenges, and dependence on U.S. government procurement timing. Technically, the stock has recently entered a corrective phase with weak momentum, though oversold conditions may support short-term stabilization.
As per the above-mentioned price action, important support near USD 580-USD 600, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for Northrop Grumman Corporation (NYSE: NOC), at the closing price of USD611.13, as of April 21, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 21, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...