Chanson International Holding
Chanson International Holding (NASDAQ: CHSN) is engaged in the production and sale of bakery, seasonal, and beverage products through its branded retail chains across China and the United States. Its China operations focus on bakery and beverage offerings along with outsourced seasonal products, while its U.S. stores provide a broader menu including meals and in-store prepared beverages, serving customers across both key markets.

Key Growth Aspects
- Margin Expansion Driven by Cost Efficiency: Chanson International Holding demonstrated notable improvement in profitability at the gross level during fiscal year 2025, supported by effective cost control measures and operational efficiencies. Gross profit increased by 14.2% year-over-year to USD 8.2 million, while gross margin expanded significantly to 45.0% from 39.5% in the prior year. This reflects enhanced inventory management, improved demand forecasting, and disciplined cost optimization strategies, which collectively strengthened the company’s underlying earnings quality despite modest revenue growth.
- Resilient Performance in Core China Operations: The company’s China segment remained a key growth driver, with revenue rising 1.3% year-over-year to USD 16.4 million. This performance was supported by strong traction in seasonal products, which grew 52.8%, aided by the establishment of a dedicated Product Planning and Promotion Department. The ability to capitalize on seasonal demand and enhance product marketing underscores the company’s adaptability to evolving consumer preferences and its focus on driving incremental revenue streams.
- Strategic Product Diversification and Innovation: Chanson continued to strengthen its product portfolio through innovation and diversification, particularly in seasonal and beverage offerings. The introduction of new cocktail variants and expanded product mix contributed to increased beverage sales in certain markets, especially in the U.S. segment. Additionally, the company’s emphasis on healthy and nutritious products aligns with shifting consumer trends, positioning it for long-term growth through differentiated offerings.
- Strengthened Balance Sheet and Capital Position: The company reported a significant increase in total assets to USD 82.0 million from USD 41.8 million in the prior year, driven by investments and capital inflows. Financing activities generated USD 39.1 million in cash, reflecting successful capital raising initiatives that support expansion plans, including new store openings and long-term investments. This improved capital base enhances financial flexibility and supports future growth initiatives.
Growth Challenges
- Muted Revenue Growth Reflecting Demand Challenges: Despite operational improvements, overall revenue growth remained largely stagnant, increasing only 0.2% year-over-year to USD 18.3 million. This limited growth highlights underlying demand challenges, particularly in bakery products, where revenue declined due to cautious consumer spending and a shift toward online consumption trends. The inability to generate stronger top-line momentum may constrain scalability in the near term.
- Weakness in U.S. Operations and Store Closures: The U.S. segment experienced a notable decline, with revenue falling 8.4% year-over-year to USD 1.9 million. This was primarily driven by store closures and suspension of operations in key locations due to competitive pressures. Reduced bakery and eat-in service revenues further indicate challenges in sustaining market share and profitability in international markets.
- Rising Operating Expenses Impacting Profitability: Operating expenses increased significantly to USD 10.1 million from USD 7.7 million in the prior year, largely due to higher selling and administrative costs. Increased rental, staffing, and online platform expenses, along with higher professional fees and credit loss provisions, weighed on operating performance. This cost escalation offset gains from gross margin expansion and limited overall earnings growth.
- Decline in Net Income and Cash Position: Net income declined sharply to USD 0.2 million from USD 0.8 million in fiscal year 2024, reflecting margin pressure at the operating level. Additionally, cash and cash equivalents decreased to USD 8.6 million from USD 12.1 million, indicating increased cash outflows, particularly from investing activities. The substantial cash usage of USD 45.8 million in investing activities further highlights elevated capital deployment, which may pressure liquidity in the near term.
Key Risks:
- Geographic Concentration Risk – Heavy reliance on China operations exposes the company to regional economic fluctuations and consumer demand shifts.
- Competitive Intensity – Increasing competition, particularly in beverages and bakery segments, may pressure pricing and margins.
- Cost Inflation Risk – Rising rental, labor, and platform-related expenses could continue to erode operating margins.
- Execution Risk in Expansion – Aggressive investments and store expansion may strain cash flows and impact return efficiency if not executed effectively
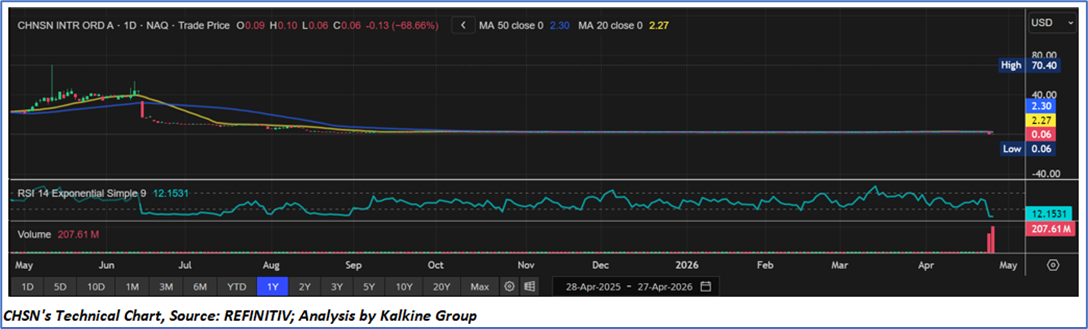
Technical Observation (on the daily chart):
- The stock has exhibited a persistent and steep downtrend over the past year, declining from significantly higher levels to near USD 0.06, indicating sustained selling pressure and erosion of investor confidence.
- Recent price action shows prolonged consolidation at the lower band, suggesting the stock is trading near its all-time lows with limited upward momentum and weak demand support.
- Moving Averages Indicate Bearish Bias: Both the 20-day and 50-day moving averages remain well above the current price and continue to slope downward, reinforcing a strong bearish trend with no signs of reversal.
- RSI Reflects Weak Momentum: The RSI is hovering around 12, indicating deeply oversold conditions. While this may hint at a potential technical bounce, it also reflects extremely weak momentum and lack of buying interest.
- A recent spike in trading volume suggests heightened market activity, possibly due to capitulation selling or speculative trading at depressed levels.
- Although oversold conditions could trigger a short-term rebound, the overall structure remains bearish unless the price sustains above key moving averages with improved volume support.
Chanson International Holding exhibited improved operational efficiency and margin expansion in fiscal year 2025, supported by cost discipline and product innovation. However, subdued revenue growth, rising operating expenses, and weakness in U.S. operations offset these gains, resulting in lower net profitability and a decline in cash reserves, indicating a balanced but cautious performance outlook.
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Watch’ rating has been Chanson International Holding (NASDAQ: CHSN) at the current market price of USD 0.06 as of April 27,2026 at 10:30 am PDT.
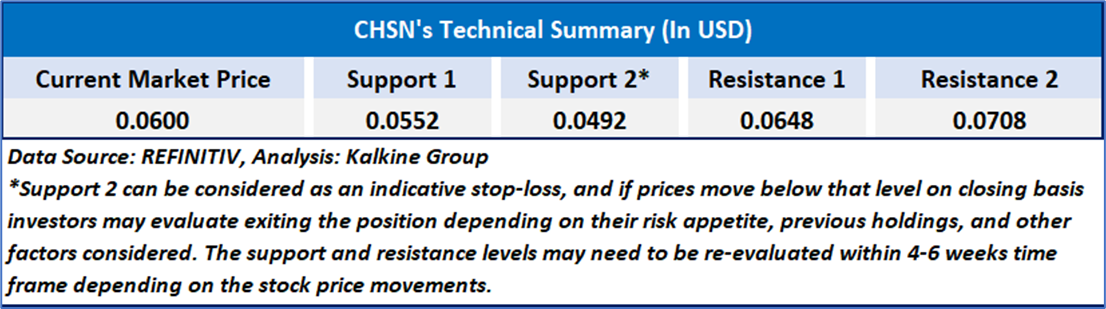
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 27,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...