indie Semiconductor, Inc
indie Semiconductor, Inc (NASDAQ: INDI) develops automotive semiconductor and software solutions focused on advanced driver assistance systems (ADAS), vehicle automation, in-cabin experience, connectivity, and electrification. The company specializes in edge sensing technologies across LiDAR, radar, ultrasound, and computer vision, offering integrated analog, digital, and mixed-signal ICs with embedded software. Its products support a wide range of applications, including vision and radar processing, wireless charging, connectivity interfaces, and high-speed data systems, with deployments across major global automotive manufacturers through Tier 1 suppliers.

Financial Performance Overview
- Revenue Growth and Execution Momentum: The company delivered a solid financial performance in the fourth quarter, with revenue reaching USD 58 million, reflecting an 8% sequential increase and surpassing the midpoint of its guidance. This growth was primarily driven by steady execution across key programs and initial contributions from new product ramps, indicating improving demand visibility and operational traction.
- Profitability Trends and Margin Expansion Efforts: Despite remaining in a loss-making phase, the company demonstrated notable improvement in profitability metrics. Non-GAAP operating loss narrowed compared to the prior year, highlighting progress toward cost optimization and operating leverage. This improvement reflects disciplined expense management alongside scaling revenues, even as the business continues to invest ahead of major program ramps.
- Cost Discipline and Operating Efficiency: The company maintained strong control over its cost base, with non-GAAP operating expenses at approximately USD 36.8 million during the quarter, aligning with its targeted savings of USD 8–10 million. This reflects a continued focus on efficiency measures and resource optimization, supporting a more sustainable cost structure as the company transitions toward higher revenue scale.
- Liquidity Position and Balance Sheet Strength: The company ended the quarter with a robust liquidity position, holding total cash, cash equivalents, and restricted cash of approximately USD 155.7 million. This strong cash base provides financial flexibility to support ongoing investments in innovation, program ramps, and strategic initiatives, while also cushioning near-term losses during the growth phase.
Operational Performance and Strategic Progress
- Product Commercialization and Shipment Milestones: Operationally, the company achieved a key milestone by commencing radar chipset shipments to a Tier 1 partner following a successful customer product launch. This transition from design to commercialization marks a critical step in revenue realization and validates the company’s technological capabilities within advanced driver-assistance systems (ADAS).
- Design Wins and Future Revenue Visibility: The company secured significant design wins, including the iND880 platform with a Chinese electric vehicle manufacturer for camera monitoring systems, expected to ramp by mid-2026. Such wins enhance long-term revenue visibility and reinforce the company’s positioning in high-growth automotive sensing markets.
- Ecosystem Expansion and Strategic Partnerships: Further strengthening its ecosystem, the company completed the integration of emotion3D technology and entered into a strategic perception software partnership with Mahindra for next-generation electric SUVs. These developments expand its software capabilities and deepen relationships with global OEMs, supporting a more integrated hardware-software value proposition.
- Diversification and Innovation in Adjacent Technologies: The company continued to diversify beyond core automotive applications, securing a design win for DFB lasers in non-automotive LiDAR and achieving its largest LXM laser booking. Additionally, upcoming Qi 2.0 wireless charging production with Ford underscores its expansion into adjacent high-growth segments, enhancing long-term growth optionality.
- Outlook and Near-Term Operational Trajectory: Looking ahead, the company expects Q1 FY26 revenue in the range of USD 52–58 million, with growth in its core business partially offset by a decline in contributions from its Wuxi subsidiary. While near-term performance may reflect transitional dynamics, the underlying growth in core operations and ongoing program ramps indicate a constructive trajectory toward scaling and improved financial performance.
Key Risks:
- Execution and Ramp Risk: Delays in converting design wins into large-scale production or slower-than-expected program ramps could impact near-term revenue realization.
- Sustained Loss-Making Phase: Continued operating losses and high investment requirements may pressure profitability timelines and cash utilization.
- Customer and Industry Concentration: Heavy reliance on automotive OEM programs and Tier 1 partners exposes the company to demand cyclicality and customer-specific risks.
- Supply Chain and Technology Risks: Dependence on outsourced manufacturing and evolving semiconductor technologies could lead to disruptions, cost volatility, or competitive pressures
Technical Observation (on the daily chart):
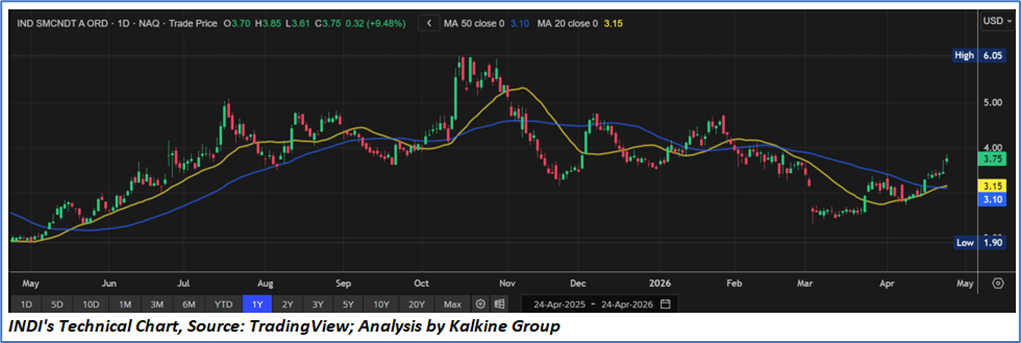
- The stock has transitioned from a prolonged downtrend into an early-stage recovery, after peaking near USD 6.0 and bottoming around USD 1.9–2.0.
- Recent price action shows formation of higher lows, indicating improving trend structure and a potential reversal.
- The price has moved above both the 20-day (USD 3.15) and 50-day (USD 3.10) moving averages, signaling strengthening short-term momentum.
- The upward slope in short-term averages reflects a gradual shift toward bullish sentiment.
- Overall trend suggests early recovery, though confirmation of a sustained uptrend requires a decisive breakout above resistance with stronger volume.
The company delivered a strong quarter marked by sequential revenue growth, disciplined cost management, and improving operating efficiency, reflecting steady progress toward scalability and profitability. Key operational milestones, including initial radar chipset shipments, strategic design wins, and expanding partnerships with global OEMs, have strengthened revenue visibility and reinforced its position in high-growth automotive and adjacent technology markets. Supported by a solid liquidity base and continued ecosystem expansion, the company remains well-positioned to benefit from upcoming program ramps and sustained demand momentum.
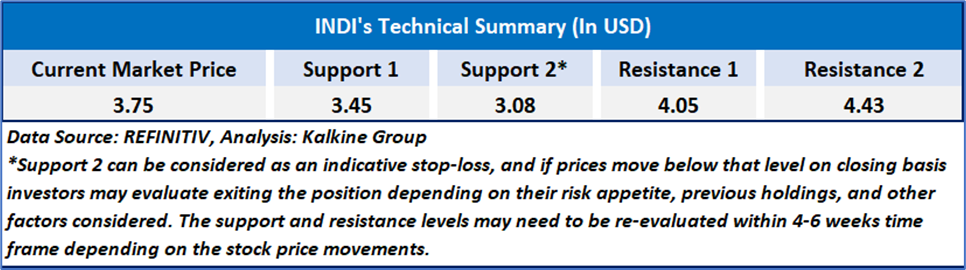
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Speculative Buy’ rating has been given to indie Semiconductor, Inc (NASDAQ: INDI) at the current market price of USD 3.75, as of April 24,2026 at 8:05 am PDT.

Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is April 24,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...