BioCryst Pharmaceuticals, Inc
BioCryst Pharmaceuticals, Inc (NASDAQ: BCRX) is a biotechnology company focused on developing treatments for hereditary angioedema (HAE) and other rare diseases. Its primary commercial product is ORLADEYO, an oral therapy for preventing HAE attacks, along with RAPIVAB, an injectable treatment for acute influenza in the United States, with additional peramivir-based products marketed internationally. The company’s pipeline includes BCX10013, a Factor D inhibitor, and navenibart, a late-stage long-acting therapy targeting plasma kallikrein for HAE. It is also advancing early-stage programs such as STAR0310 for atopic dermatitis, highlighting its broader focus on rare and immunological conditions.

From Story Stock to Earnings Story: BioCryst Pharmaceuticals has crossed a threshold that many small-cap biotechs fail to reach. After years of investment-led growth, the company has delivered sustained profitability, anchored by the commercial success of its hereditary angioedema treatment, ORLADEYO. Yet just as fundamentals begin to stabilise, the stock is being pulled into a different narrative. Takeover rumours and elevated retail activity have added a speculative overlay, complicating what might otherwise be a straightforward earnings-driven rerating.
Sector Backdrop:
- Rare Disease Economics Remain Compelling: The rare disease segment continues to attract disproportionate capital within biotechnology. The rationale is structural rather than cyclical. High pricing power, regulatory support and limited competition create resilient revenue pools once a product is established. Hereditary angioedema sits firmly within this category. Treatments are long-term, patient adherence is high and switching costs are meaningful. For companies like BioCryst, this translates into predictable cash flows once scale is achieved. This is precisely the stage BioCryst now appears to be entering.
Earnings Momentum:
- ORLADEYO Drives the Inflection: The company’s Q4 2025 results marked a clear break from its historical profile. Earnings per share of $1.12 exceeded expectations by a wide margin, while revenue of $163.28 million reflected continued strength in ORLADEYO demand. Full-year revenue of roughly $602 million confirms that the drug is no longer a growth experiment but a commercially established asset. Guidance for 2026, set at $625 million to $645 million, implies continued expansion, albeit at a more measured pace. More importantly, BioCryst reported its first full year of operating profitability. This alters the analytical lens through which the company is viewed. Valuation can now incorporate earnings durability rather than relying solely on pipeline optionality.
Strategic Positioning:
- Deepening Rather Than Diversifying: The acquisition of Astria Therapeutics reinforces a focused strategy. Rather than branching into adjacent therapeutic areas, BioCryst is doubling down on hereditary angioedema. This approach is both efficient and defensive. It leverages existing commercial infrastructure while strengthening the pipeline within a single disease category. At the same time, it acknowledges rising competitive pressure, as new therapies aim to improve convenience and efficacy. The implication is clear. BioCryst is positioning itself not as a one-product company, but as a franchise builder within a defined niche.
Market Behaviour:
- Speculation Versus Fundamentals: Recent price action suggests that the market is not solely focused on fundamentals. Takeover speculation has driven bursts of buying activity, particularly in after-hours trading, accompanied by a sharp rise in retail engagement. Strategically, BioCryst would be a logical acquisition target. It offers a derisked asset, improving margins and a clear therapeutic focus. These are precisely the characteristics larger pharmaceutical companies seek in bolt-on deals. However, the absence of confirmed interest leaves the current valuation exposed to sentiment shifts. Insider selling adds a further layer of nuance. While not unusual in isolation, a pattern of sales without corresponding purchases may temper institutional enthusiasm, particularly in a momentum-driven environment.
Key Risks:
- Product Concentration Risk: Heavy reliance on ORLADEYO for the majority of revenue exposes the company to demand, pricing, or competitive pressures within a single asset.
- Competitive Landscape Intensification: Advancements in HAE therapies, particularly those offering improved efficacy or dosing convenience, could impact market share and long-term growth.
- Pipeline Execution Uncertainty: Late-stage and early-stage candidates, including navenibart and BCX10013, face clinical, regulatory, and commercialization risks that may delay or limit future value creation.
- Sentiment and Ownership Overhang: Ongoing insider selling and takeover speculation may increase stock volatility and influence investor perception independent of underlying fundamentals.
Technical Observation (on the daily chart):
- The chart structure supports a constructive view, though not an overheated one.
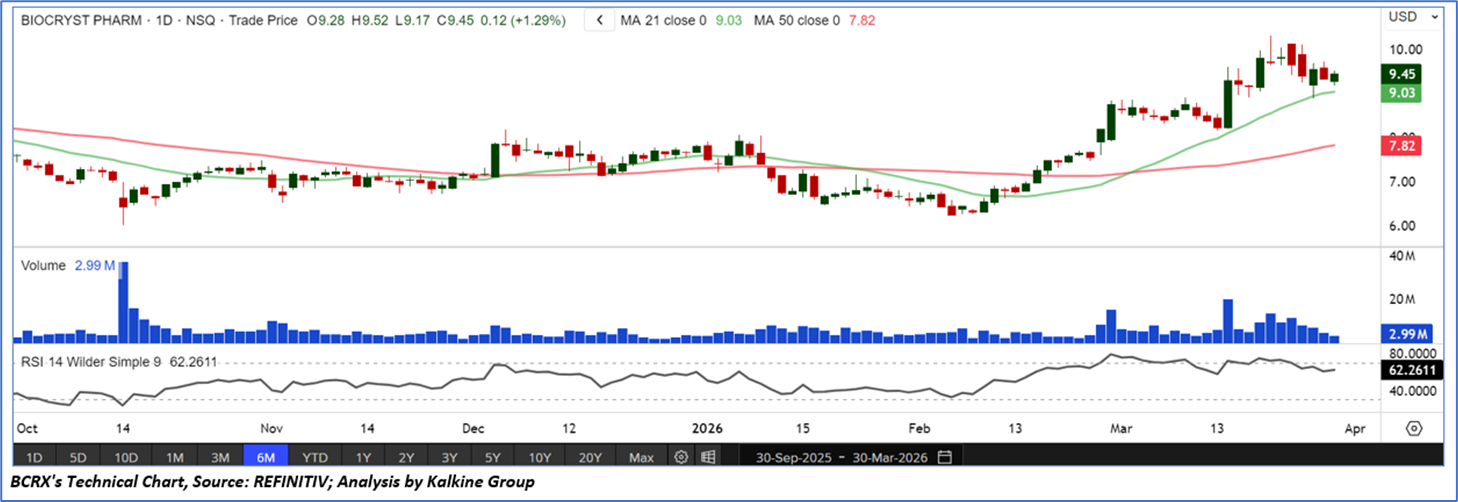
- BioCryst is trading above both its 21-day and 50-day simple moving averages, signaling alignment across timeframes and pointing to the potential start of a sustained uptrend. The recent breakout from an extended consolidation range further supports this bullish shift.
- Momentum remains supportive. The 14-day RSI is near 62, having pulled back from around 73 before stabilising. This reset indicates that bullish control remains intact without entering overbought territory.
- Volume expansion during upward moves points to improving participation, lending credibility to the trend. Near-term consolidation is possible, but the broader structure suggests accumulation rather than distribution.
BioCryst’s investment case has evolved materially. It is now a profitable biotech with a commercially validated product and a strategy centred on depth rather than breadth. At the same time, the stock has become noisier. Takeover rumours and insider activity have introduced variables that sit outside the core fundamentals. For investors, the distinction is critical. The underlying business is becoming more predictable, even as the share price becomes less so.
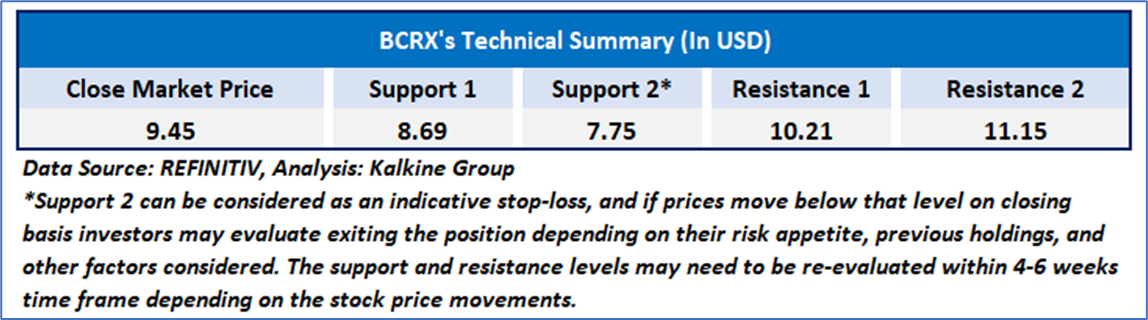
As per the above-mentioned price action, recent key business and financial updates, momentum in the stock over the last month, and technical indicators analysis, a ‘Speculative Buy’ rating has been given to BioCryst Pharmaceuticals, Inc (NASDAQ: BCRX) at the close market price of USD 9.45, as of March 30, 2026.

Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is March 30,2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice

 CA
 NZ
 UK
 US
 IND

 AU

 Please wait processing your request...