AGNC Investment Corporation
AGNC Investment Corp. (NASDAQ: AGNC) is an internally managed real estate investment trust (REIT). The Company provides private capital to the United States housing market, enhancing liquidity in the residential real estate mortgage markets and, in turn, facilitating home ownership in the United States. The Company invests primarily in Agency residential mortgage-backed securities (Agency RMBS) on a leveraged basis.

Key Business and Financial Updates:
- Strategic Overview: A Pure-Play Agency MBS Platform Positioned for Rate and Spread Stability: AGNC Investment Corp. (Nasdaq: AGNC) reported fourth quarter 2025 results that reflect a constructive operating environment for Agency mortgage-backed securities (Agency MBS), supported by declining interest rate volatility and an improving policy backdrop around government-sponsored enterprise (GSE) reform. As the largest pure-play Agency MBS mortgage REIT, AGNC’s performance continues to be driven by its actively managed portfolio of Agency MBS and hedging program, with the company benefiting from tightening mortgage spreads and a more accommodative rate regime. Management highlighted that these macro dynamics provide a favourable foundation entering 2026, with potential catalysts—such as increased Agency MBS purchases by Fannie Mae and Freddie Mac—supporting further spread tightening and enhanced risk-adjusted return potential.
- Q4 2025 Shareholder Outcomes: Strong Comprehensive Income and Book Value Accretion: AGNC produced comprehensive income of USD 0.89 per common share in Q4 2025, comprised of USD 0.83 net income per share and USD 0.06 of other comprehensive income (OCI). Tangible net book value increased meaningfully to USD 8.88 per share, up USD 0.60 per share (+7.2%) versus the prior quarter, demonstrating strong mark-to-market portfolio performance. The company declared USD 0.36 per share in dividends for the quarter, and generated an 11.6% economic return on tangible common equity, combining cash distributions and book value appreciation. Net spread and dollar roll income—the firm’s key earnings indicator—was USD 0.35 per share, reflecting steady run-rate earnings generation, excluding the modest impact of catch-up premium amortization adjustments tied to prepayment assumptions.
- Portfolio Composition and Funding Profile: Scale, Liquidity, and Controlled Leverage: As of December 31, 2025, AGNC maintained a USD 94.8 billion investment portfolio, primarily composed of USD 81.1 billion in Agency MBS and USD 13.0 billion net forward TBA positions, with a limited allocation to CRT and non-Agency securities. The portfolio remains heavily concentrated in 30-year fixed-rate Agency exposure, representing approximately 95% of holdings, reflecting high conviction in the sector’s relative value. Leverage was managed conservatively within AGNC’s operating framework, with 7.2x tangible net book value “at risk” leverage at quarter-end. Liquidity remained a notable strength, with USD 7.6 billion of unencumbered cash and Agency MBS, representing 64% of tangible equity, providing meaningful flexibility in a rate-sensitive market and supporting balance sheet resilience through volatility regimes.
- Interest Rate Economics and Prepayment Dynamics: Stable Spreads with Moderating Funding Costs: Core portfolio economics remained stable during the quarter. AGNC’s annualized net interest spread (including TBA position and interest rate swaps) was 1.81%, slightly higher than the prior quarter, supported by lower funding costs and steady asset yields. Repurchase agreement funding costs declined, with the weighted average repo rate at 4.13% (versus 4.43% in Q3), while the firm’s combined cost of funds, inclusive of swaps, was 3.10%. Prepayment behavior increased modestly, with projected portfolio CPR rising to 9.6% and actual CPR at 9.7%, resulting in premium amortization costs consistent with expectations. The company continued to actively manage interest rate risk through a robust hedge program, with hedges representing approximately 69% of funding liabilities, underscoring AGNC’s focus on controlling exposure in an evolving monetary environment.
- Full-Year 2025 Performance and Capital Markets Execution: Strong Total Return and Accretive Equity Issuance: AGNC reported an exceptional full-year 2025 outcome, generating comprehensive income of USD 1.74 per share, declaring USD 1.44 per share in dividends, and producing an economic return on tangible common equity of 22.7%. Tangible net book value increased 5.6% year-on-year to USD 8.88 per share, and the company delivered a 34.8% total stock return (including dividend reinvestment), materially outperforming broad equity benchmarks. Capital markets activity remained a key driver of shareholder value creation, as AGNC issued equity via ATM programs at a premium to tangible book value—resulting in accretive issuance dynamics and enhanced common shareholder positioning. Overall, AGNC’s Q4 and FY2025 performance validates the firm’s active Agency MBS strategy, emphasizing its ability to generate attractive yield-based returns while maintaining disciplined leverage, liquidity strength, and robust hedging execution.
Key Company specific risks for AGNC:
- Interest Rate Volatility and MBS Spread Widening Risk: AGNC’s core returns are highly sensitive to interest rate movements and Agency MBS spread dynamics. A sudden rise in rate volatility or a widening of mortgage spreads versus Treasuries can lead to mark-to-market losses, tangible book value declines, and weaker economic returns, even if long-term fundamentals remain intact.
- Prepayment (CPR) and Extension/Convexity Risk: As an Agency MBS investor, AGNC is exposed to changes in mortgage prepayment speeds (CPR). Faster-than-expected prepayments can increase premium amortization and reduce asset yields, while slower prepayments can create extension risk and duration mismatch. Either scenario can pressure earnings, hedging effectiveness, and book value.
- Leverage, Funding, and Liquidity Risk (Repo Dependence): AGNC operates with meaningful leverage and relies heavily on repurchase agreement (repo) funding. Any tightening in repo markets, higher funding costs, collateral stress, or reduced financing availability could negatively impact net interest spreads, force portfolio adjustments at unfavorable prices, and increase downside risk during market dislocations.
Technical Observation (on the daily chart):
- Trend Structure: Steady Uptrend in Place: AGNC continues to trade in a constructive medium-term uptrend, with higher highs and higher lows following the April drawdown. The stock is currently around USD ~11.97, indicating sustained buyer control. Summary: Price action remains trend-positive with a stable recovery structure.
- Moving Average Confirmation: Bullish Support from Key Averages: AGNC is holding above the 21-day MA (~USD 11.49) and 50-day MA (~USD 10.89), both rising, which confirms a bullish trend regime. These levels now act as dynamic supports on pullbacks. Summary: Trend strength is supported as long as price stays above key moving averages.
- Momentum Profile: Strong RSI with Limited Short-Term Cooling Risk: The RSI near ~68 reflects strong bullish momentum, though it is approaching overbought levels, implying the possibility of short-term consolidation. Volume remains stable, supporting trend credibility. Summary: Momentum is strong, but mild near-term consolidation risk exists.
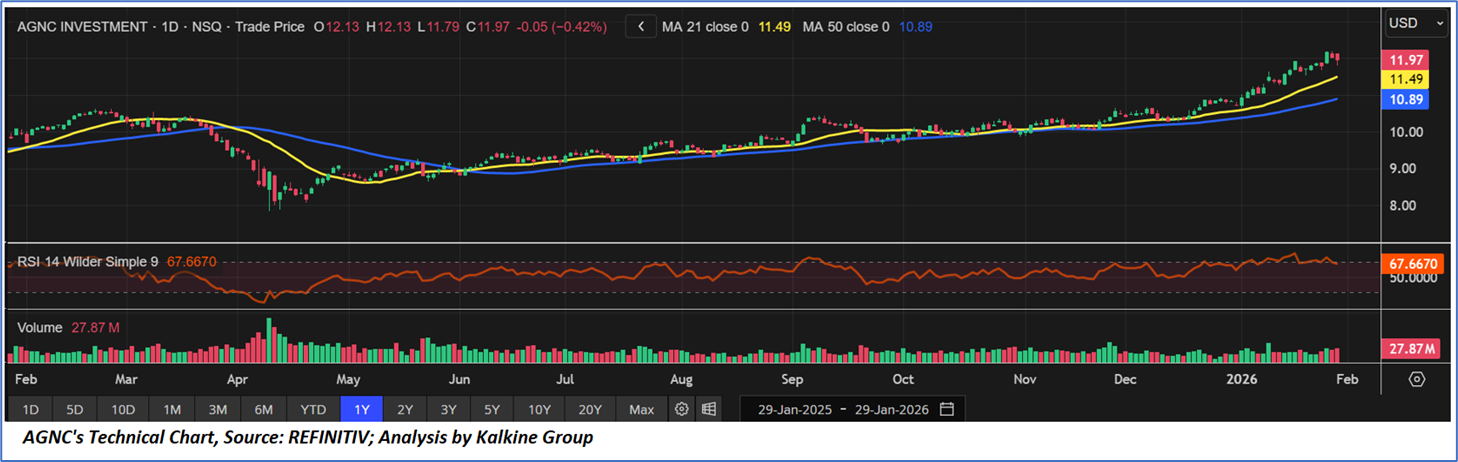
AGNC Investment Corp. (NASDAQ: AGNC) is an internally managed mortgage REIT providing leveraged exposure to Agency residential mortgage-backed securities, with shareholder outcomes primarily driven by Agency MBS spreads, hedging execution, and funding costs. Q4 2025 reflected a supportive operating backdrop, with the company delivering USD 0.89 comprehensive income per share, tangible book value rising to USD 8.88 (+7.2% QoQ), and maintaining steady earnings power through USD 0.35 net spread and dollar roll income, alongside USD 0.36 dividends. The portfolio remains large and liquid (USD 94.8 billion) with controlled leverage (7.2x “at risk”) and strong unencumbered liquidity (USD 7.6 billion, ~64% of tangible equity), supporting resilience in a rate-sensitive asset class. However, AGNC’s risk profile remains structurally tied to interest rate volatility, mortgage spread widening, and prepayment/extension dynamics, which can rapidly pressure book value and returns. Technically, AGNC is trending constructively near USD ~11.97, supported by rising moving averages and strong momentum, though mild consolidation risk exists after recent strength.
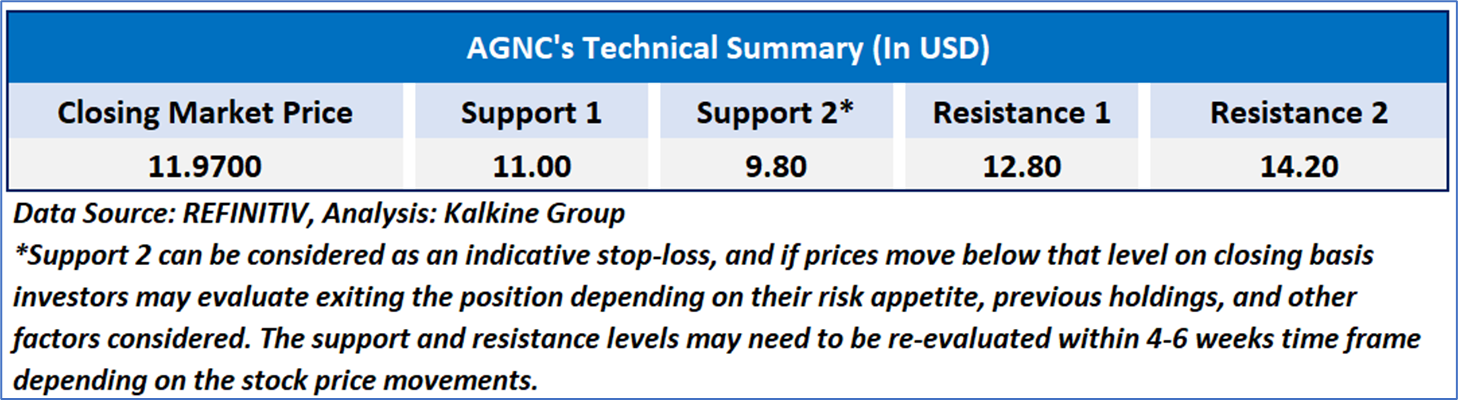
As per the above-mentioned price action, important support near USD 10.50- USD 11.00, momentum in the stock over the last month, and technical indicators analysis, a ‘WATCH’ rating has been given for AGNC Investment Corp. (NASDAQ: AGNC), at the closing price of USD11.97, as of January 29, 2026.
Individuals can evaluate the stock based on the support and resistance levels provided in the report in case of keen interest taking into consideration the risk-reward scenario.
Markets are trading in a highly volatile zone currently due to certain macro-economic issues and prevailing geopolitical tensions. Therefore, it is prudent to follow a cautious approach while investing.
Related Risk: This report may be looked at from a high-risk perspective, and a recommendation is provided for a short duration. This report is solely based on technical parameters, and the fundamental performance of the stocks has not been considered in the decision-making process. Other factors which could impact the stock prices include market risks, regulatory risks, interest rates risks, currency risks, social and political instability risks etc.
Note 1: Past performance is not a reliable indicator of future performance.
Note 2: The reference date for all price data, currency, technical indicators, support, and resistance level is January 29, 2026. The reference data in this report has been partly sourced from REFINITIV.
Note 3: Investment decisions should be made depending on an individual's appetite for upside potential, risks, holding duration, and any previous holdings. An 'Exit' from the stock can be considered if the Target Price mentioned as per the Valuation and or the technical levels provided has been achieved and is subject to the factors discussed above.
Note 4: Target Price refers to a price level that the stock is expected to reach as per the relative valuation method and or technical analysis taking into consideration both short-term and long-term scenarios.
Note 5: ‘Kalkine reports are prepared based on the stock prices captured either from the New York Stock Exchange (NYSE), NASDAQ Capital Markets (NASDAQ), and or REFINITIV. Typically, all sources (NYSE, NASDAQ, or REFINITIV) may reflect stock prices with a delay which could be a lag of 15-20 minutes. There can be no assurance that future results or events will be consistent with the information provided in the report. The information is subject to change without any prior notice.

 CA
 NZ
 UK
 US
 IND

 AU
 Please wait processing your request...