The Offer

Company Overview
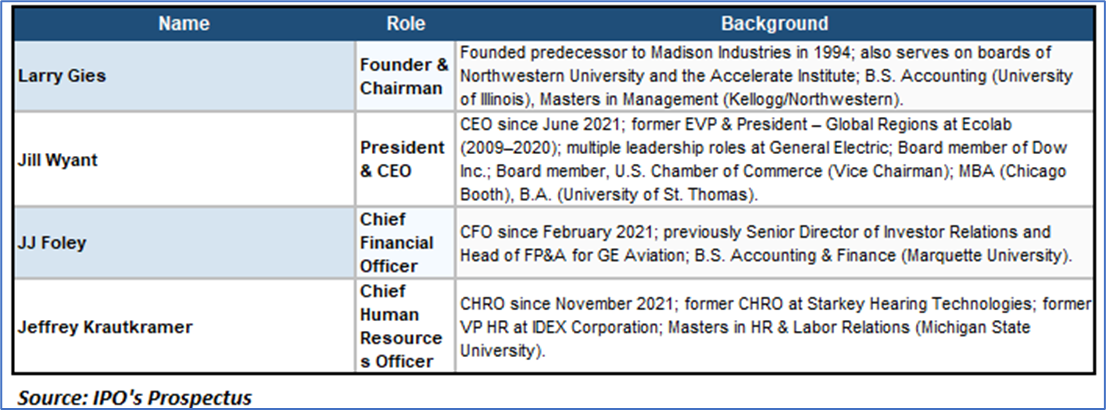
Madison Air Solutions Corporation is a leading provider of mission-critical indoor air quality (IAQ) solutions, headquartered in Chicago, Illinois, with operations spanning two strategically important and complementary segments: Commercial and Residential. The company serves highly demanding environments where air quality has a direct impact on operational efficiency, regulatory compliance, human health, and productivity. Its portfolio comprises several established and respected brands, including Nortek Data Center Cooling, Nortek Air Solutions, AprilAire, and Big Ass Fans, each holding strong positions within their respective categories. For the fiscal year ended December 31, 2025, Madison Air reported net sales of USD 3.3 billion and net income of USD 124.3 million, supported by an Adjusted EBITDA margin of 26.7% and a workforce of more than 8,650 employees. The company addresses an estimated USD 40 billion North American total addressable market that is differentiated from the broader traditional HVAC sector, while its current market share of approximately 8% suggests meaningful long-term growth potential. Madison Air’s proposed initial public offering represents a spin-off from its parent company, Madison Industries, controlled by founder Larry Gies, following a period of significant strategic acquisitions, most notably the purchase of AprilAire, a leading residential IAQ brand that materially expanded the company’s scale and market opportunity.
Key Highlights
Primary Offering:
Madison Air Solutions Corporation is offering 82,692,308 shares of Class A Common Stock at an indicative price range of USD 25.00 to USD 27.00 per share, with an additional over-allotment option for up to 12,403,846 shares, while Madison Industries Holdings LLC has committed to purchase USD 100.0 million of Class B Common Stock through a concurrent private placement at the IPO price. Following the transaction, the company will maintain a dual-class governance structure under which founder Larry Gies is expected to retain approximately 95.2% of total voting power, while cornerstone investors including Counterpoint Global, Durable Capital Partners LP, and HRTG GPE, LLC have expressed interest in acquiring up to USD 525.0 million of Class A shares, underscoring strong institutional support for the offering.
Use of proceeds:
- Primary Application of Proceeds – Strategic Debt Deleveraging: Madison Air Solutions Corporation estimates net proceeds of approximately USD 2,073.1 million from the base offering, or approximately USD 2,385.1 million if the underwriters’ over-allotment option is exercised in full, based on an assumed offering price of USD 26.00 per share, representing the midpoint of the indicated price range. When combined with the concurrent private placement of USD 100.0 million, total gross proceeds are expected to approximate USD 2,173.1 million. The primary objective of the transaction is to materially strengthen the company’s balance sheet through a significant reduction in leverage.
- Debt Repayment and Interest Cost Reduction: Substantially all net proceeds, estimated at approximately USD 2,173.1 million, are intended to repay outstanding borrowings under the initial Term Loan Facility, including accrued and unpaid interest obligations. As of December 31, 2025, this facility carried an effective interest rate of approximately 5%. The planned deleveraging is expected to meaningfully reduce the company’s annual financing burden, with Pro Forma Adjusted interest obligations projected to decline to approximately USD 208.9 million on an annualized basis.
- Residual Proceeds and Capital Allocation Flexibility: Any proceeds remaining after the planned debt repayment will be allocated toward general corporate purposes. Management retains broad discretion regarding the deployment of such residual capital, including any incremental proceeds arising from the exercise of the underwriters’ over-allotment option. Until deployed, unused proceeds may be invested in short-term, investment-grade, interest-bearing instruments, thereby preserving liquidity and financial flexibility.
- Post-Offering Residual Indebtedness Profile: Management has indicated that, on a Pro Forma Adjusted basis following repayment of the initial Term Loan Facility, the company is expected to retain aggregate principal indebtedness of approximately USD 3,583.3 million. This balance will consist of the Incremental Term Loan Facility of USD 1,545.6 million, Secured Notes of USD 700.0 million, and Unsecured Notes of USD 1,035.0 million, alongside up to USD 334.3 million of available revolving credit capacity. While the IPO proceeds materially improve leverage metrics, the company will continue to operate with a meaningful debt structure post-transaction.
Dividend Policy:
Madison Air Solutions Corporation has indicated that it does not expect to declare or pay cash dividends on its common stock for the foreseeable future, as management intends to retain available capital and future earnings to fund ongoing business development, support both organic and inorganic growth initiatives, and facilitate the repayment of outstanding indebtedness. Any future decision regarding dividend distributions will remain subject to the sole discretion of the Board of Directors, applicable provisions of Delaware corporate law, and the restrictive covenants contained within existing or future financing arrangements. Consequently, prospective shareholder returns are expected to be driven principally by capital appreciation rather than recurring dividend income.
Madison Air Solutions Corporation – Business Model, Market Opportunity and Strategic Competitive Positioning
- Diversified Mission-Critical Air Quality Platform with Recurring Demand Characteristics: Madison Air Solutions Corporation operates as a diversified industrial platform focused on delivering highly engineered indoor air quality solutions across two core segments: Commercial and Residential. The Commercial segment serves mission-critical environments such as data centers, semiconductor fabrication facilities, pharmaceutical cleanrooms, healthcare institutions, and commercial buildings, where precision air management is essential for uptime, regulatory compliance, and operational efficiency. The Residential segment addresses the growing needs of health-conscious homeowners through established brands such as AprilAire, offering whole-home healthy air systems, humidity management, ventilation, and filtration solutions. Importantly, approximately half of fiscal year 2025 net sales were derived from replacement and upgrade demand, while approximately 10% originated from aftermarket parts and services, providing a meaningful degree of recurring revenue and resilience through economic cycles.
- Substantial Addressable Market Supported by Long-Term Structural Growth Drivers: Madison Air competes within a North American indoor air quality market estimated by management at approximately USD 40 billion, distinct from the broader traditional HVAC market exceeding USD 200 billion. Since 2021, the company estimates that its targeted total addressable market has expanded by approximately USD 28 billion, supported by several enduring secular drivers, including heightened awareness of human health and clean air, aging residential housing stock, refurbishment needs across older commercial buildings, accelerating AI and data center development, reshoring of advanced manufacturing, energy resilience and electrification trends, industrial productivity enhancement, and evolving building codes and IAQ regulatory standards. With an estimated current market share of approximately 8%, the company believes it remains in the early stages of a significant long-term growth runway.
- Strong Competitive Positioning Driven by Brands, Innovation and Scale Advantages: Madison Air’s competitive positioning is underpinned by four principal advantages: a portfolio of trusted brands with strong channel recognition, deep application expertise in technically demanding environments, a robust patent-protected innovation pipeline, and entrenched customer and distribution relationships. In addition, the company benefits from a decentralized manufacturing footprint and enterprise-scale procurement capabilities that support cost efficiencies difficult for fragmented smaller competitors to replicate. Madison Air competes primarily against niche regional players and, in select markets, non-core offerings of larger HVAC original equipment manufacturers. Its differentiated “Return on Air” value proposition, focused on measurable productivity and performance outcomes rather than commoditized airflow solutions, supports premium pricing power and strong customer retention.
- Disciplined Acquisition Strategy Complementing Organic Growth Momentum: The company has executed an active and strategic merger and acquisition agenda to broaden scale and category exposure. Most notably, the AprilAire acquisition completed in 2025 contributed approximately USD 178.8 million of pro forma incremental net sales while materially expanding the Residential segment’s addressable market. Madison Air has also recently completed the AcoustiFLO acquisition, which has not yet been reflected in the pro forma financial statements. Looking ahead, management has signaled continued interest in bolt-on acquisitions aligned with its core indoor air quality mission. Importantly, organic revenue growth reached 4% in fiscal year 2025, compared with 2.9% in fiscal year 2024, demonstrating that recent momentum extends beyond acquisition-led expansion.
- Robust Backlog Enhancing Revenue Visibility and Strategic Optionality: As of December 31, 2025, Madison Air reported backlog of approximately USD 2.0 billion, representing a substantial increase from USD 968.2 million in fiscal year 2024 and USD 705.5 million in fiscal year 2023. This accelerated backlog trajectory provides meaningful forward revenue visibility and supports confidence in near- to medium-term demand conditions. Combined with strong end-market exposure, recurring replacement demand, and an improving balance sheet following the proposed IPO, the company appears strategically positioned to capitalize on secular indoor air quality trends while retaining flexibility for further growth investments.
Madison Air Solutions Corporation – Industry Landscape, Structural Growth Drivers and Competitive Positioning
Large and Distinct Indoor Air Quality Market with Significant Remaining Runway: Madison Air Solutions Corporation operates within the North American indoor air quality (IAQ) solutions market, which management estimates represents approximately USD 40 billion of addressable opportunity. This market is distinct from the broader traditional heating, ventilation, and air conditioning market, which exceeds USD 200 billion in scale. Since 2021, the company estimates its targeted addressable market has expanded by approximately USD 28 billion, reflecting strong secular demand, strategic acquisitions, and entry into higher-growth end markets. Based on fiscal year 2025 net sales of USD 3.3 billion, Madison Air’s implied market share is approximately 8%, suggesting substantial room for continued organic and acquisition-led expansion.
Diverse End-Market Exposure Across Attractive High-Growth Sub-Segments: The company’s addressable market spans several structurally attractive categories. Residential indoor air quality solutions represent an estimated USD 15.0 billion opportunity, supported by low household penetration rates and aging housing stock. Data center cooling contributes an estimated USD 8.0 billion market opportunity, benefiting from accelerating investment in AI, cloud infrastructure, and hyperscale computing facilities. Additional attractive segments include semiconductor fabrication HVAC systems, commercial refurbishment demand, life sciences and cleanroom environments, balanced residential ventilation, and low-humidity industrial manufacturing applications. This broad market exposure provides Madison Air with diversified demand sources across both cyclical and secular growth industries.
Powerful Structural Megatrends Supporting Long-Term Demand: Industry demand for indoor air quality solutions is being reinforced by several long-duration macro trends. Rising awareness of health and clean air quality standards is driving adoption across residential, healthcare, education, and workplace settings. Aging residential and commercial building stock is increasing replacement and modernization demand, while new regulatory standards related to ventilation, energy efficiency, and air quality continue to raise required performance thresholds. Simultaneously, rapid growth in AI-driven data centers, reshoring of advanced manufacturing such as semiconductors and pharmaceuticals, and the need for energy-efficient building systems are expanding demand for precision air management solutions. Collectively, these trends create a durable and expanding market backdrop.
Installed Base and Aftermarket Economics Enhance Revenue Quality: Beyond original equipment sales, Madison Air benefits from an increasingly valuable installed-base business model. Approximately 50% of aftermarket component sales are derived from proprietary parts, generating attractive recurring revenue streams with potentially higher margins. Certain solutions, such as data center cooling systems and residential filtration products, can generate lifecycle aftermarket revenue multiples well above the initial equipment sale value. Combined with a record backlog of approximately USD 2.0 billion at fiscal year-end 2025, these dynamics enhance forward revenue visibility and may support stronger long-term cash flow conversion.
Durable Competitive Moat Built on Brands, Innovation and Scale: Madison Air competes primarily against smaller, fragmented niche providers and, in select markets, non-core offerings from larger HVAC manufacturers. The company’s competitive differentiation is built on a multi-layered moat comprising trusted brands, deep application-specific expertise, strong customer and distribution relationships, enterprise-scale procurement capabilities, and a substantial innovation engine supported by approximately 600 research and development engineers. In addition, Madison Air holds more than 900 issued patents and pending patent applications, strengthening pricing power and reducing commoditization risk. Its decentralized operating model further enables local responsiveness while retaining the benefits of scale, positioning the company favorably within a fragmented and growing industry landscape.
Financial Highlights (Results of Operations) (Expressed in USD)
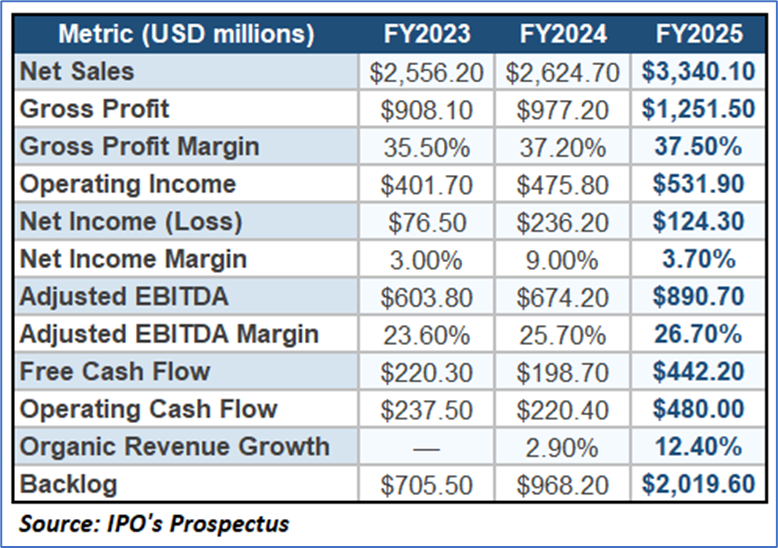
- Revenue Scale and Accelerating Growth Trajectory: Madison Air Solutions Corporation reported net sales of USD 3,340.1 million in fiscal year 2025, representing a substantial 3% year-over-year increase, compared with USD 2,624.7 million in fiscal year 2024 and USD 2,556.2 million in fiscal year 2023. The strong performance was driven by contributions from the AprilAire acquisition as well as robust underlying demand across core markets. Organic revenue growth reached 12.4% in fiscal year 2025, accelerating meaningfully from 2.9% in fiscal year 2024. On a pro forma basis, including a full-year contribution from AprilAire, net sales totaled USD 3,518.9 million for fiscal year 2025.
- Margin Expansion and Improved Gross Profitability: Gross profit increased to USD 1,251.5 million in fiscal year 2025, while Gross Profit Margin improved to 5%, compared with 37.2% in fiscal year 2024 and 35.5% in fiscal year 2023. The margin progression reflects favorable product mix, ongoing manufacturing efficiencies, and pricing discipline. On an adjusted basis, excluding technology intangible amortization and purchase accounting impacts, Adjusted Gross Profit Margin was 38.9% in fiscal year 2025, indicating continued operational quality and earnings leverage.
- Adjusted EBITDA Growth and Strengthening Profit Profile: Adjusted EBITDA rose significantly to USD 890.7 million in fiscal year 2025, compared with USD 674.2 million in fiscal year 2024 and USD 603.8 million in fiscal year 2023. Correspondingly, Adjusted EBITDA Margin expanded to 7%, continuing a three-year trend of consistent improvement from 23.6% to 25.7% and then 26.7%. On a pro forma adjusted basis, Adjusted EBITDA was USD 936.6 million, representing a margin of 26.6%, underscoring the scalability of the platform following recent acquisitions.
- Net Income Profile and Financing Cost Considerations: Net income attributable to Madison Air totaled USD 97.0 million in fiscal year 2025, while reported net income was USD 124.3 million, inclusive of non-controlling interests. Fiscal year 2024 reported net income of USD 236.2 million was elevated by USD 82.6 million of income from discontinued operations; on a continuing operations basis, fiscal year 2025 income of USD 125.7 million was broadly comparable. However, interest and financing expenses of USD 351.3 million in fiscal year 2025 continued to exert a meaningful drag on bottom-line profitability.
- Cash Flow Generation, Capital Deployment and Backlog Visibility: Free Cash Flow nearly doubled to USD 442.2 million in fiscal year 2025, compared with USD 198.7 million in fiscal year 2024 and USD 220.3 million in fiscal year 2023, while Free Cash Flow Conversion reached 8%. Operating cash flow increased to USD 480.0 million in fiscal year 2025, versus USD 220.4 million in fiscal year 2024. The company also recorded a significant investing cash outflow of USD 2,353.2 million during fiscal year 2025, primarily associated with the AprilAire acquisition. At year-end fiscal 2025, backlog reached a record USD 2.0 billion, providing substantial forward revenue visibility.
Key Management Highlights
Risk Associated (High)
Investment in the initial public offering of Madison Air Solutions Corporation (MAIR) is subject to several material risk factors, including the following:
- Founder Control and Governance Risk: Following the IPO, Larry Gies is expected to retain approximately 2% of total voting power through ownership of Class B shares. As a “controlled company” under NYSE governance standards, Madison Air will qualify for exemptions from certain corporate governance requirements. Accordingly, founder interests may not always align with those of public Class A shareholders, while Mr. Gies will retain the ability to nominate directors and exercise effective control over major corporate decisions.
- Significant Leverage Profile: On a Pro Forma Adjusted basis, the company is expected to maintain approximately USD 3,583.3 million of total indebtedness following the offering, with annual interest obligations of approximately USD 208.9 million. Although IPO proceeds are intended to reduce leverage, the company is expected to remain meaningfully levered, which may constrain financial flexibility during periods of market stress or limit capacity for acquisitions and strategic investments.
- Cyclicality and Macroeconomic Sensitivity: A meaningful portion of Madison Air’s revenue base and backlog growth is linked to data center expansion associated with AI and cloud computing, reshoring of advanced manufacturing, and residential housing replacement activity. These end markets remain sensitive to broader economic cycles, interest rate conditions, construction trends, and potential slowdowns in technology-related capital expenditure.
- Acquisition Integration Risk: Madison Air has pursued an active acquisition strategy, including the acquisitions of AprilAire and AcoustiFLO. This strategy introduces execution risk related to business integration, potential goodwill impairment, and the successful realization of anticipated synergies. Failure to effectively integrate acquired assets could adversely affect operating margins and returns on invested capital.
Conclusion
Madison Air Solutions Corporation presents an attractive industrial IPO proposition supported by a differentiated portfolio of mission-critical indoor air quality brands, strong positioning across structurally growing end markets, and exposure to an estimated USD 40 billion North American addressable market. The company delivered robust fiscal year 2025 performance, including net sales of USD 3.3 billion, Adjusted EBITDA of USD 890.7 million with a 26.7% margin, Free Cash Flow of USD 442.2 million, and a record backlog of USD 2.0 billion, reflecting healthy demand momentum and improving operating leverage . Strategic acquisitions such as AprilAire have expanded scale and residential market penetration, while recurring replacement demand, aftermarket revenue streams, and a substantial patent-backed product portfolio enhance earnings quality. In addition, strong institutional participation, including indicated cornerstone demand of up to USD 525 million, and the planned use of IPO proceeds toward deleveraging may further strengthen the company’s financial profile. Overall, Madison Air appears well positioned to benefit from long-term secular drivers such as AI-driven data center cooling demand, aging building infrastructure, clean air awareness, and reshoring of advanced manufacturing.
Hence, given the financial performance of the company, use of proceeds, and associated risks “Madison Air Solutions Corporation (MAIR)” IPO seems “Attractive" at the IPO price.
Disclaimer-
This report (“Report”) has been issued by Kalkine Pty Limited (ABN 34 154 808 312) (Australian financial services licence number 425376) (“Kalkine”) and prepared by Kalkine and its related bodies corporate who are authorised to provide general financial product advice. Kalkine.com.au and its associated pages are published by Kalkine.
Any advice provided in this Report is general advice only and does not take into account your objectives, financial situation or needs. You should therefore consider whether the advice is appropriate for your objectives, financial situation and needs before acting upon it.
There may be a Product Disclosure Statement, Information Memorandum or other offer document (“Offer Document”) for the securities or other financial products referred in this Report. You should obtain a copy of the relevant Offer Document and consider it before making any decision about whether to acquire the security or financial product.
Kalkine strongly recommends that you seek advice from a financial adviser, stockbroker or other professional (including taxation and legal advice) before acting on any of the general advice in this Report or on the Kalkine website. Not all investments are appropriate for all people.
The information in this Report and on the Kalkine website has been prepared from a wide variety of sources, which Kalkine, to the best of its knowledge and belief, considers accurate. Kalkine has made every effort to ensure the reliability of the information contained in its reports (including this Report), newsletters and websites. All information represents our views at the date of publication and may change without notice.
The information in this Report does not constitute an offer to sell securities or other financial products or a solicitation of an offer to buy securities or other financial products. Our reports contain general recommendations to invest in securities and other financial products. Kalkine is not responsible for, and does not guarantee, the performance of, or returns on, any investments mentioned in this Report.
Kalkine does not issue, sell or deal in any financial products.
This Report may contain information on past performance of particular investments. Past performance is not a reliable indicator of future performance. Returns stated do not take into account transaction costs and taxes. To the extent permitted by law, and excluding any dishonesty or gross negligence by Kalkine, Kalkine disclaims and excludes all liability for any direct, indirect, implied, punitive, special, incidental or other consequential loss or damage arising from the use of or reliance on this Report, the Kalkine website and any information published on the Kalkine website without any warranties or representations by Kalkine to you. To the extent the law prohibits or limits this exclusion, Kalkine limits its liability to the resupply of services.
Please also read our Terms & Conditions and Financial Services Guide for further information. Employees and/or associates of Kalkine and its related entities may hold interests in the securities or other financial products covered in this Report or on the Kalkine website. Any such employees and associates are required to comply with certain, procedures and disclosures as required by law.
Kalkine Media Pty Ltd, an affiliate of Kalkine Pty Ltd, may have received, or be entitled to receive, financial consideration in connection with providing information about certain entity(s) covered on its website including entities covered in this Report.
Copyright 2026 Krish Capital Pty. Ltd. (ABN 61629651510). All Rights Reserved. No part of this report, or its content, may be reproduced in any form without our prior consent.
Past performance is not a reliable indicator of future performance.

 CA
 NZ
 UK
 US
 IND

 AU
 Please wait processing your request...