The Offer

Company Overview
Encore Medical, Inc. (EMI) is a development-stage medical device company focused on minimally invasive cardiac implant technologies, particularly for conditions such as patent foramen ovale (PFO). The company is in an early commercialization phase, with ~USD 2 million in annual revenue and an ongoing emphasis on clinical validation and regulatory approvals, particularly in the U.S. The IPO aims to raise approximately USD 15–17 million, primarily to fund clinical trials and working capital, positioning EMI as a high-risk, high-upside healthcare innovation play contingent on successful regulatory execution.
Key Highlights
Primary Offering:
3,000,000 shares of common stock, which may increase to approximately 3,450,000 shares if the overallotment option is fully exercised.
Use of proceeds:
- Clinical Development as Primary Capital Allocation Priority: Encore Medical intends to deploy a substantial portion of its IPO proceeds toward advancing its clinical pipeline, with approximately USD 7.2 million allocated to stroke-related clinical trials and USD 2.0 million toward migraine indication studies. This implies that over 70% of total proceeds will be directed toward regulatory and clinical development activities, underscoring the company’s positioning as a clinical-stage, milestone-driven entity where valuation is closely linked to trial outcomes and regulatory approvals.
- Operational Expansion and Balance Sheet Optimization: In addition to clinical investments, the company plans to allocate capital toward operational scaling and financial restructuring, including approximately USD 1.0 million for sales and marketing initiatives and USD 1.2 million for equipment, production, and R&D infrastructure. Furthermore, USD 1.0–1.75 million is earmarked for debt repayment, reflecting a measured effort to strengthen the balance sheet and improve financial flexibility ahead of potential commercialization activities.
- Working Capital and Strategic Flexibility: The remaining proceeds, estimated at USD 1.0–2.5 million, are intended for general corporate purposes and working capital requirements, providing liquidity support for day-to-day operations and strategic initiatives. However, given the relatively modest allocation toward commercialization and general purposes, the company may require additional funding in the future, particularly as it progresses toward large-scale regulatory approvals and market entry.
Dividend Policy:
Encore Medical, Inc. does not intend to declare or pay dividends in the foreseeable future and expects to retain any available funds and future earnings to support business operations, clinical development, and growth initiatives; accordingly, the decision to pay dividends, if any, will remain at the discretion of the board of directors and will depend on factors such as financial condition, operating results, capital requirements, and regulatory considerations, with investor returns primarily expected to be driven by capital appreciation rather than income.
Encore Medical, Inc. – Business Model, Market Opportunity and Strategic Positioning
- Core Business Model and Product Offering: Encore Medical, Inc. is a specialized medical device company engaged in the development, manufacturing, and commercialization of septal occlusion devices designed for minimally invasive correction of cardiac defects such as patent foramen ovale (PFO) and atrial septal defects (ASD). The company has established a meaningful international footprint, with its devices implanted in approximately 35,000 patients outside the United States, and operates with full ownership of its intellectual property, regulatory approvals, and manufacturing infrastructure following its spin-off from Cardia. These devices offer a cost-effective and less invasive alternative to open-heart surgery, with procedures typically completed within 30 minutes and significantly lower lifetime treatment costs.
- Market Opportunity and Clinical Demand Drivers: The company’s primary growth driver lies in the PFO closure market, which presents substantial global opportunity given that approximately 25% of the adult population exhibits PFO, and an estimated 250,000 cases annually require immediate intervention due to cryptogenic stroke. Additionally, emerging clinical associations between PFO and migraine conditions further expand the addressable market, with over 45 million migraine sufferers in the United States and a potential multi-million patient opportunity. Pricing dynamics further support scalability, with device prices ranging from USD 2,000–4,000 internationally and ~USD 11,000 in the U.S., indicating significant revenue expansion potential upon regulatory approval and U.S. market entry.
- Regulatory Pathway and Growth Strategy: Encore’s strategic focus is centered on achieving S. FDA approval, which remains a critical catalyst for unlocking its full commercial potential. The company is currently progressing its PerFOrm clinical trial (500-patient study), with expected completion over 18–24 months, followed by a Premarket Approval (PMA) submission. In parallel, the company continues to expand its international sales network across Europe and other regions while investing in research and development to enhance product capabilities and explore new indications. This dual-track strategy—leveraging existing international revenues while advancing regulatory milestones—positions Encore for potential transition into a commercial-stage medtech company with scalable growth prospects, albeit subject to regulatory and execution risks.
Financial Highlights (Results of Operations) (Expressed in USD)
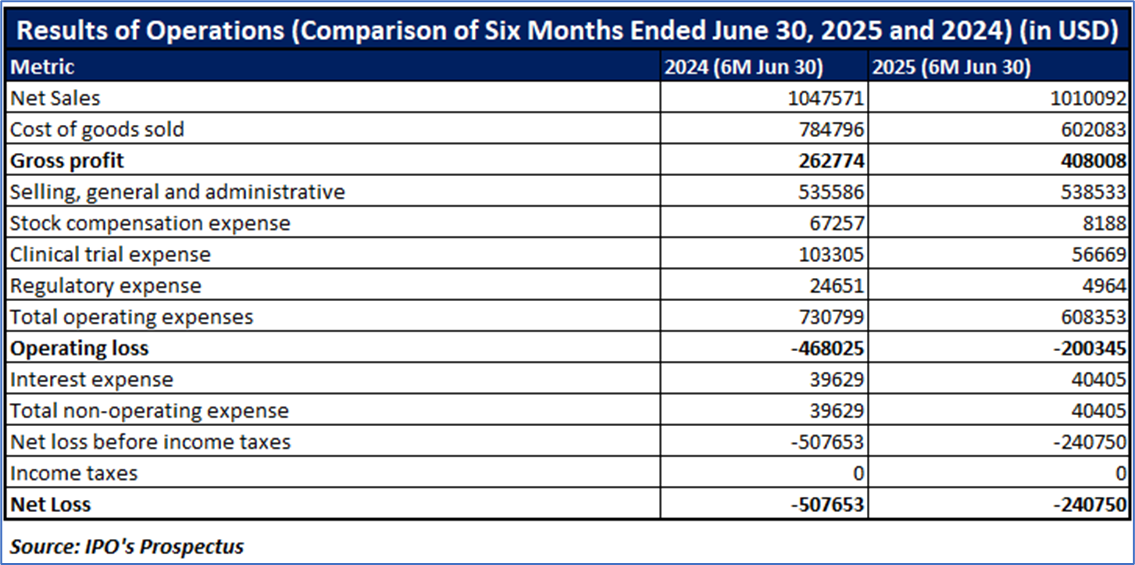
- Revenue Trends and Margin Expansion: For the six months ended June 30, 2025, the company reported net sales of USD 1.01 million, representing a 6% decline compared to USD 1.05 million in the prior-year period, primarily attributable to management’s strategic focus on IPO and fundraising activities. Despite the modest revenue contraction, profitability improved significantly, with gross profit increasing to USD 408,008 and gross margin expanding to 40.4% from 25.1%. This margin expansion was driven by a substantial 23.2% reduction in cost of goods sold to USD 602,083, reflecting lower raw material costs and enhanced manufacturing efficiencies, indicating a structurally improved cost base.
- Operating Expense Rationalization and Efficiency Gains: Operating expenses demonstrated a notable decline, driven by both structural and cyclical factors. While selling, general, and administrative expenses remained broadly stable, stock-based compensation decreased significantly by USD 59,069 to USD 8,188, due to the absence of prior-year option grants. Additionally, clinical trial expenses declined by 45.1% to USD 56,669, reflecting constrained funding availability, and regulatory expenses decreased by USD 19,687 to USD 4,964, consistent with lower regulatory activity during the period. Overall, these reductions contributed to improved operating efficiency, albeit partially reflecting reduced investment intensity in key growth areas.
- Cash Flow Dynamics and Funding Structure: From a cash flow perspective, the company continues to operate with negative operating cash flows, with USD 462,269 used in operating activities in FY2024, though significantly improved from USD 1.66 million in FY2023, primarily due to favorable working capital movements. Investing activities were minimal in FY2024, compared to modest capital expenditure in FY2023 related to equipment purchases. Financing activities remained a key liquidity source, with USD 403,826 raised in FY2024 through equity issuance, compared to USD 1.05 million in FY2023 driven by debt financing. This shift indicates a transition toward equity-based funding, supporting ongoing operations amid continued cash burn.
Key Management Highlights
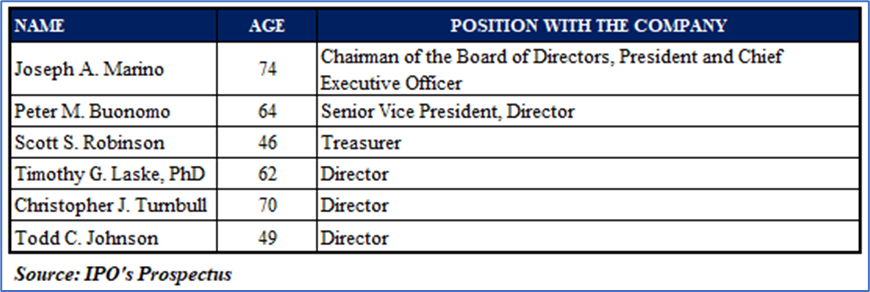
Risk Associated (High)
Investment in the IPO of “EMI” is exposed to a variety of risks such as:
- Regulatory Dependency: The company is heavily reliant on S. FDA approval, with clinical trials expected to extend into 2027, creating long lead times and binary outcomes.
- Early-Stage Financial Profile: EMI generates minimal revenue (~USD 1.9–2.0 million) and continues to operate with negative earnings and cash flows, indicating reliance on external funding.
- Dilution Risk: IPO investors face significant dilution (~USD 3.77 per share) relative to net tangible book value, highlighting a valuation premium over current assets.
- Execution Risk: Success depends on clinical trial outcomes, physician adoption, and commercialization capabilities in a competitive medtech landscape.
- Liquidity Risk: There is no existing trading history, and the prospectus highlights the possibility that an active trading market may not develop.
Conclusion
Encore Medical, Inc. presents a development-stage, high-risk medical device investment opportunity centered on minimally invasive cardiac implant technologies, with a strong global footprint but limited current revenue (~USD 2 million annually). The IPO aims to raise USD 15–17 million, with over 70% of proceeds allocated toward clinical trials, highlighting a milestone-driven growth model dependent on successful regulatory approvals, particularly from the U.S. FDA. While the company benefits from a large addressable market for PFO closure and improving gross margins driven by cost efficiencies, it continues to operate with negative cash flows and relies on external funding. The investment case is balanced by significant long-term potential from commercialization and market expansion, offset by key risks including regulatory dependency, dilution, execution challenges, and uncertain market liquidity, making returns largely contingent on future clinical and regulatory outcomes rather than near-term financial performance.
Hence, given the financial performance of the company, use of proceeds, and associated risks “Encore Medical, Inc.(EMI)” IPO seems “Neutral" at the IPO price.
Disclaimer-
This report (“Report”) has been issued by Kalkine Pty Limited (ABN 34 154 808 312) (Australian financial services licence number 425376) (“Kalkine”) and prepared by Kalkine and its related bodies corporate who are authorised to provide general financial product advice. Kalkine.com.au and its associated pages are published by Kalkine.
Any advice provided in this Report is general advice only and does not take into account your objectives, financial situation or needs. You should therefore consider whether the advice is appropriate for your objectives, financial situation and needs before acting upon it.
There may be a Product Disclosure Statement, Information Memorandum or other offer document (“Offer Document”) for the securities or other financial products referred in this Report. You should obtain a copy of the relevant Offer Document and consider it before making any decision about whether to acquire the security or financial product.
Kalkine strongly recommends that you seek advice from a financial adviser, stockbroker or other professional (including taxation and legal advice) before acting on any of the general advice in this Report or on the Kalkine website. Not all investments are appropriate for all people.
The information in this Report and on the Kalkine website has been prepared from a wide variety of sources, which Kalkine, to the best of its knowledge and belief, considers accurate. Kalkine has made every effort to ensure the reliability of the information contained in its reports (including this Report), newsletters and websites. All information represents our views at the date of publication and may change without notice.
The information in this Report does not constitute an offer to sell securities or other financial products or a solicitation of an offer to buy securities or other financial products. Our reports contain general recommendations to invest in securities and other financial products. Kalkine is not responsible for, and does not guarantee, the performance of, or returns on, any investments mentioned in this Report.
Kalkine does not issue, sell or deal in any financial products.
This Report may contain information on past performance of particular investments. Past performance is not a reliable indicator of future performance. Returns stated do not take into account transaction costs and taxes. To the extent permitted by law, and excluding any dishonesty or gross negligence by Kalkine, Kalkine disclaims and excludes all liability for any direct, indirect, implied, punitive, special, incidental or other consequential loss or damage arising from the use of or reliance on this Report, the Kalkine website and any information published on the Kalkine website without any warranties or representations by Kalkine to you. To the extent the law prohibits or limits this exclusion, Kalkine limits its liability to the resupply of services.
Please also read our Terms & Conditions and Financial Services Guide for further information. Employees and/or associates of Kalkine and its related entities may hold interests in the securities or other financial products covered in this Report or on the Kalkine website. Any such employees and associates are required to comply with certain, procedures and disclosures as required by law.
Kalkine Media Pty Ltd, an affiliate of Kalkine Pty Ltd, may have received, or be entitled to receive, financial consideration in connection with providing information about certain entity(s) covered on its website including entities covered in this Report.
Copyright 2026 Krish Capital Pty. Ltd. (ABN 61629651510). All Rights Reserved. No part of this report, or its content, may be reproduced in any form without our prior consent.
Past performance is not a reliable indicator of future performance.

 CA
 NZ
 UK
 US
 IND

 AU
 Please wait processing your request...