
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Distinct royalty model: earns income without mining costs or risks.
- Diversified portfolio across commodities and operators.
- Generates earnings with a P/E ratio ~10.19x, rare among peers.
High Peak Royalties (ASX:HPR) is a structurally distinct entity within the ASX resources sector. Rather than developing or operating mines, the company acquires royalty interests in mining and energy projects, earning revenue proportional to production without bearing the capital expenditure, operating cost, or construction risk associated with direct project development. This business model is well-established in North American markets — where companies like Franco-Nevada and Wheaton Precious Metals have demonstrated multi-decade value creation — but remains comparatively rare on the ASX.
High Peak's portfolio provides diversified exposure across commodities and projects, with revenue scaling as underlying mines produce and as commodity prices rise.
|
Metric |
Data |
|
Share Price |
A$0.065 |
|
5-Day Change |
+1.56% |
|
52-Week Range |
$0.041 – $0.071 |
|
Market Capitalisation |
~A$126 million |
|
P/E Ratio |
~10.19x |
|
Sector |
Mining Royalties |
Business Model: The Royalty Advantage
The royalty model's structural advantages relative to conventional mining companies are meaningful and worth articulating clearly:
- No capital expenditure exposure: High Peak does not fund construction, equipment, or operating costs at underlying mines
- No cost inflation risk: Rising energy, labour, and consumable costs at the mine level do not directly impact royalty income
- Diversification across commodities and operators: A portfolio of royalties distributes risk across multiple assets and management teams
- Leverage to production growth: As underlying mines expand or new discoveries are made on royalty ground, High Peak's revenue grows without additional investment
- Leverage to commodity prices: Royalty income typically rises proportionally with commodity price increases
The key limitation of the model is its dependence on third-party operators — High Peak's revenue is entirely contingent on the production decisions, operational performance, and financial health of the underlying mine operators.
Financial Profile
High Peak's reported P/E ratio of approximately 10.19x is the most distinctive financial characteristic in this report — it indicates that the company is actually generating earnings, distinguishing it from every other company covered here. A sub-10x P/E for a royalty company with a diversified portfolio and no capex exposure is a conservative valuation by sector standards, though the modest market capitalisation of A$126 million suggests the portfolio is still in its early stages of development.
Revenue is tied to royalty agreements, with income fluctuating alongside commodity prices and production volumes from underlying assets.
Share Price Performance
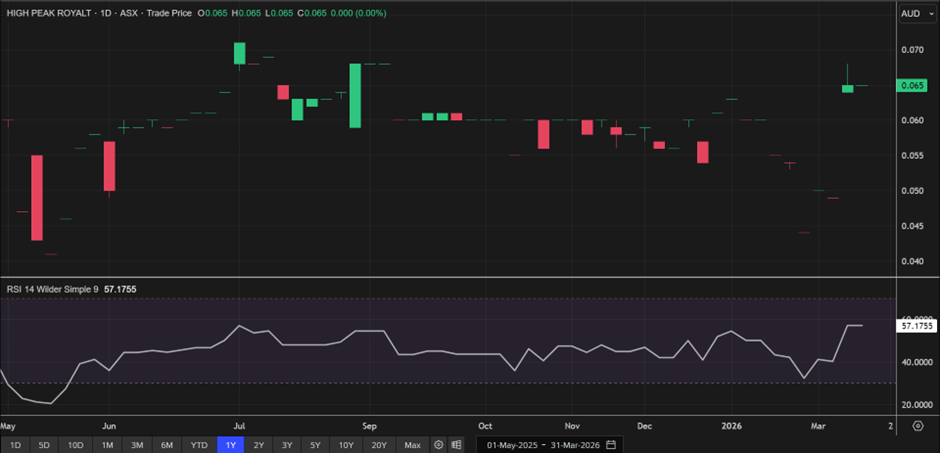
At A$0.065, High Peak is trading near the upper end of its 52-week range of $0.041 to $0.071. The gradual +1.56% appreciation over five days reflects the low-volatility, steady-accumulation trading profile typical of royalty companies — a stark contrast to the extreme daily moves seen in Lindian or Strike Resources. The stock's proximity to its 52-week high suggests the market is constructive on the current portfolio and business development trajectory.
Source: EODHD/Others
Risk Assessment
|
Risk Factor |
Description |
Severity |
|
Third-Party Operator Dependency |
Revenue requires underlying mines to produce consistently |
Moderate |
|
Portfolio Concentration |
Small portfolio increases single-asset risk |
Moderate |
|
Commodity Price Exposure |
Royalty income scales with commodity prices |
Moderate |
|
Growth Execution |
Portfolio expansion requires disciplined capital allocation |
Moderate |
|
Market Liquidity |
A$126M market cap may limit institutional participation |
Low–Moderate |
Bull & Bear Case
Bull Case: High Peak successfully acquires additional royalty interests, expanding portfolio diversification and income base. Commodity prices rise across the portfolio's exposure, amplifying royalty income. The P/E multiple re-rates toward peer royalty company benchmarks as the portfolio scale justifies institutional attention.
Bear Case: Underlying mine operators curtail production or enter financial difficulty, reducing royalty income. New royalty acquisitions are priced at unattractive economics, diluting returns. The small portfolio size limits income diversification, and a single asset underperformance has an outsized negative impact.
Investment Conclusion
High Peak Royalties is the most defensively positioned company in this report. Its royalty model, actual earnings base, and low-volatility trading profile make it structurally different from every other stock covered here. For investors seeking critical minerals exposure without development-stage binary risk, High Peak offers a genuine income-oriented alternative.
The primary limitation is scale — the portfolio and market capitalisation are modest, and significant value creation will require successful royalty portfolio expansion over time.
Best suited for: Conservative investors seeking mining sector exposure with income generation potential and lower volatility than development-stage peers.


 Nov 12, 2026





 Please wait processing your request...