
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
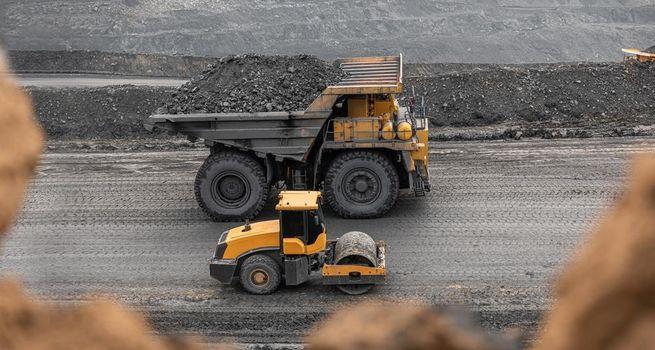
Key Highlights
- Final Investment Decision approved for transformational Doropo Gold Project in Cote d'Ivoire on March 12, 2026
- Exceptional project economics: US$2.54B NPV (5%), 72% IRR, 1.1 year payback from first production at US$4,000/oz gold
- Life of mine gold production of 2.2M ounces over 13-year mine life with average AISC of US$1,472/oz
- Construction to commence H1 2026 with average annual production of 204 koz during Years 1-5, targeting 500 koz annual production by end of 2028
- Strong balance sheet with net cash position of US$209 million as of December 31, 2025 to fund development and operations
Resolute Mining Limited (ASX:RSG) operates as an Africa-focused gold mining company with dual listing on the Australian Securities Exchange (ASX) and London Stock Exchange. Currently operating the Syama Gold Mine in Mali, Resolute executes a strategic transformation toward becoming a leading multi-asset gold producer in West Africa.
The company's strategic vision targets 500,000 ounces of annual gold production by end of 2028, representing substantial growth from current operations. This ambitious production target reflects management's conviction in West Africa's prospectivity and Resolute's capability to develop world-class assets.
CEO Chris Eger leads Resolute's transformation agenda, focused on building a diversified gold production platform across West Africa. The Doropo Gold Project FID approval marks a critical milestone in executing this strategic vision, positioning Resolute to become a tier-one regional gold producer.
Doropo Gold Project: Final Investment Decision Milestone
On March 12, 2026, Resolute Mining announced Final Investment Decision approval for the Doropo Gold Project located in the Bounkani Region of Cote d'Ivoire, approximately 480 kilometers northeast of Abidjan. This transformational milestone authorizes full-scale project development and construction commencement.
The FID approval follows completion of a comprehensive Definitive Feasibility Study detailing project technical specifications, capital requirements, and economic assumptions. The FID decision, made with board approval and management confidence, authorizes capital deployment and construction activities.
Construction is scheduled to commence during H1 2026, with anticipated mine development timeline spanning multiple years. The project development represents a substantial capital commitment reflecting management's conviction in project economics and strategic value.
Doropo Project Economics: Exceptional Value Creation Opportunity
The Doropo Gold Project demonstrates exceptional economic characteristics as revealed in the Definitive Feasibility Study at US$4,000 per ounce gold pricing. The project generates an impressive 72% internal rate of return with a project payback period of just 1.1 years from first production.
At base case gold pricing of US$4,000/oz, the project delivers net present value of US$2,543 million using a 5% discount rate. This substantial NPV reflects the project's robust economic fundamentals and exceptional value creation potential for Resolute shareholders.
Project free cash flow totals US$318 million on a life-of-mine basis and US$419 million during the first five years of production. These substantial free cash flow generation characteristics support dividend distributions, debt repayment, and reinvestment in growth opportunities.
Production Profile and Mine Life Characteristics
The Doropo Gold Project encompasses a 13-year mine life with life-of-mine ore processing of 59,102 kilotonnes. The mine operates at a 4.9 strip ratio and processes ore averaging 1.31 grams per tonne gold with 88% overall recovery, generating 2,196 kiloounces of gold production across the mine life.
Years 1-5 production averages 204 kiloounces annually, reflecting strong early production rates as the mine ramps to steady-state operations. Life-of-mine average annual production reaches 169 kiloounces, demonstrating profitable later-life operations.
The extended 13-year mine life provides earnings visibility and cash flow sustainability extending well into the future. Long mine lives reduce near-term dependence on exploration success and new project development, supporting stable operational cash flows.
Cost Structure and All-In Sustaining Cost Dynamics
The Doropo Project demonstrates competitive cost structure with life-of-mine all-in sustaining costs of US$1,472 per ounce. During Years 1-5, AISC averages US$1,360/oz, indicating strong early-life cost economics benefiting from higher production rates and operational efficiency.
Upfront capital requirements of US$516 million fund full mine development, infrastructure establishment, and operational ramp-up. Capital intensity of approximately US$235 per annual ounce reflects reasonable development costs relative to project scale and gold price assumptions.
Life-of-mine EBITDA averages US$438 million annually, with Years 1-5 averaging US$554 million. These substantial EBITDA generation characteristics demonstrate robust operational cash generation supporting shareholder distributions and growth investment.
Gold Price Sensitivity and Project Resilience
Doropo project economics demonstrate strong sensitivity to gold price movements, with NPV declining from US$3,629 million at US$5,000/oz gold to US$1,457 million at US$3,000/oz. This sensitivity reflects substantial leverage to gold price with strong returns at elevated prices and acceptable returns at lower prices.
At US$3,000/oz gold pricing, the project still generates positive NPV of US$1,457 million using 5% discount rate assumptions. This downside resilience demonstrates robust project fundamentals supporting project profitability across a wide range of gold price scenarios.
The project's strong economics at US$4,000/oz mid-cycle gold pricing provide confidence in operational returns even if gold prices decline. Project cost structure supports profitability at lower gold prices, though reduced NPV and cash flow generation at lower prices impacts shareholder returns.
Strategic Importance for Resolute Mining's Growth Agenda
The Doropo Gold Project is transformational for Resolute Mining's strategic agenda to become a leading West African gold producer. Combined with existing Syama Gold Mine operations, Doropo represents substantial production growth toward the 500 kiloounce annual production target by 2028.
Project success depends on construction execution, mine development timelines, and operational ramp-up performance. Achievement of target production levels requires effective project management and operational excellence during the critical development and startup phases.
The project positions Resolute within a growing West African gold mining region with improving geopolitical stability, mining-friendly policies, and significant mineral endowments. Successful Doropo development establishes platform for additional growth through exploration and potential acquisitions.
Mining Permit and Regulatory Framework
Resolute has secured mining permit approval from Cote d'Ivoire's Council of Ministers, providing essential regulatory authorization for project development. Permit approval represents successful navigation of Cote d'Ivoire's regulatory framework and government relationships.
Long-term mining permit provides operational certainty and resource rights protection across the 13-year mine life. Regulatory stability in Cote d'Ivoire, supported by modern mining code and established mining sector, provides favorable governance environment.
Successful permitting reflects Resolute's stakeholder engagement, government relations, and commitment to sustainable development practices. Continued positive government relationships are essential for operational continuation and future exploration expansion.
Balance Sheet Strength and Financing Capacity
Resolute maintains a strong net cash position of US$209 million as of December 31, 2025, providing substantial capital resources to fund Doropo development. This financial strength enables self-funding of US$516 million project capital without material debt financing.
The company's net cash position reflects disciplined capital management and cash generation from Syama operations. Financial flexibility supports optimal capital structure for project development while maintaining financial stability.
Strong balance sheet positions Resolute to manage operational challenges, fund growth investments, and return capital to shareholders. Financial strength reduces refinancing risk and provides optionality for strategic opportunities.
Investment Thesis: Growth Catalyst for RSG Shareholders
The Doropo FID approval represents a significant catalyst supporting Resolute's strategic transformation. Successful project development and operation positions RSG as a multi-asset West African gold producer with enhanced earnings power and shareholder value creation.
The project's exceptional economics provide confidence in management's capital allocation discipline and project selection. Strong NPV generation and cash flow characteristics support investor conviction in management's ability to execute growth strategy.
Investors should monitor project construction progress, operational achievements, and production ramp-up performance. Successful execution validates management capability and supports confidence in achieving 500 kiloounce production target by 2028.
Conclusion
Resolute Mining Limited's Final Investment Decision approval for the Doropo Gold Project in Cote d'Ivoire represents a transformational milestone in the company's strategic evolution toward becoming a leading West African gold producer. The project's exceptional economics—72% IRR, US$2.54 billion NPV, and 1.1 year payback period—reflect outstanding project quality and substantial shareholder value creation potential. With construction commencing H1 2026 and average production of 204 kiloounces annually during the first five years, Doropo positions Resolute to progress toward its 500 kiloounce annual production target by 2028.
The project's strong cost structure, demonstrated by US$1,472/oz all-in sustaining costs on a life-of-mine basis, supports profitable operations across diverse gold price scenarios. Resolute's solid balance sheet, featuring US$209 million net cash as of December 31, 2025, provides substantial financial flexibility to self-fund project development while maintaining operational stability. For investors seeking exposure to African gold mining growth and junior gold producer transformation, Resolute's FID approval and strategic positioning warrant serious consideration. Success in Doropo development and execution will validate management capability and support confidence in achieving the company's ambitious growth targets and shareholder value creation objectives.
Questions Investors Are Asking About Resolute Mining
Q: What does the Doropo FID approval mean for Resolute Mining shareholders, and why is it significant?
A: FID approval authorizes full-scale project development and construction commencement, representing confirmation of project economics and management commitment to development. The FID follows comprehensive feasibility studies and board approval, signaling high confidence in project viability and returns.
Q: How do Doropo's project economics compare to industry benchmarks and other gold projects?
A: The Doropo project demonstrates exceptional economics with 72% IRR, US$2.54B NPV, and 1.1 year payback. These metrics exceed typical gold project benchmarks, reflecting outstanding project quality and strong value creation potential. AISC of US$1,472/oz ranks favorably within industry cost structures.
Q: What is the timeline for Doropo construction and production, and when will the project contribute to earnings?
A: Construction commences H1 2026 with development timelines spanning multiple years. Initial production likely ramps during 2027-2028 period, with target average production of 204 koz annually during Years 1-5. Achievement of 500 koz annual production target depends on Doropo success and operational execution.
Q: How sensitive is Doropo's project economics to gold price fluctuations, and what happens if gold prices decline?
A: Project NPV ranges from US$3,629M at US$5,000/oz to US$1,457M at US$3,000/oz gold. The project remains economically viable across wide price ranges, though lower gold prices reduce NPV and free cash flow generation. Strong costs structure supports profitability at lower prices.
Q: Can Resolute finance Doropo development from internal cash generation, or will the company require external financing?
A: Resolute's US$209 million net cash position and Syama operational cash flows provide substantial financing capacity. The company can potentially self-fund much of the US$516 million project capital, reducing debt financing requirements and maintaining financial flexibility.
Q: What regulatory and geopolitical risks could impact Doropo development or operations?
A: Cote d'Ivoire represents a stable West African jurisdiction with modern mining code and established mining sector. While political and regulatory risks exist in any emerging market, Cote d'Ivoire has demonstrated mining-friendly policies. Resolute's successful permitting reflects positive government relationships.
Q: How does Doropo production contribute to Resolute's 500 kiloounce annual production target by 2028?
A: Doropo's 204 koz average annual production during Years 1-5, combined with Syama operations, supports the 500 koz target. Achieving target depends on both projects operating at planned production rates and potential additional growth from exploration or acquisitions.
Q: What construction and operational risks could impact Doropo project execution and timeline?
A: Project risks include construction delays, cost overruns, operational challenges during ramp-up, and staffing challenges. Successful execution depends on skilled management, effective supply chain, and operational discipline. Investors should monitor construction progress announcements.
Q: Could lower gold prices trigger suspension or deferral of Doropo construction?
A: Strong project economics across wide price ranges and Resolute's financial capacity suggest low risk of suspension at current gold prices. However, material gold price declines below US$3,000/oz could prompt management to reassess development timing, though project fundamentals remain sound.
Q: How does Doropo success impact Resolute's strategic positioning within West Africa gold mining?
A: Successful Doropo development establishes Resolute as a multi-asset West African gold producer, creating platform for additional growth through exploration expansion and potential acquisitions. Strong project execution enhances management credibility for future capital raises and growth initiatives.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own research and consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.

 Sep 18, 2026
 Please wait processing your request...